



PW Consulting: EAA Market to Reach USD 5,622.78M by 2032 at 5.38% CAGR

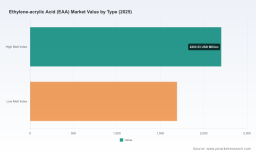
Ethylene‑Acrylic Acid (EAA) Market 2026 Preview: Strategic Signals for Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I offer this executive introduction to our comprehensive Ethylene‑Acrylic Acid (EAA) Market study. Built on a 2025 base year and extending through a 2026–2032 forecast window, the research translates complex technical, commercial and regulatory dynamics into decision‑ready intelligence. This preview highlights the macro trajectory, competitive inflection points and actionable frameworks that make the full report essential for board‑level and commercial planning in 2026—while deliberately reserving the granular, proprietary segment tables for subscribers.
Ethylene-acrylic Acid (EAA) Market
Key macro view: growth with structural continuity
The global EAA market has demonstrated steady expansion through the first half of the decade, rising from a multi‑billion dollar base in 2020 to a significantly larger market by 2025. Our modeling projects continued, moderate growth across the 2026–2032 forecast horizon at a compound annual growth rate of 5.38%. By 2032 the market is expected to be materially larger than the 2025 base, reflecting a mix of sustained demand in packaging and adhesives, incremental penetration into high‑performance coatings and continued substitution in select multilayer film applications.
Ethylene-acrylic Acid (EAA) Market
Why this matters for 2026: a 5%+ CAGR is large enough to justify capacity planning, portfolio prioritization and targeted M&A conversations, yet modest enough that returns will favor companies that combine operational efficiency with differentiated technical value. In short, volume growth alone will not guarantee outperformance—strategic positioning and feedstock resilience will.
Ethylene-acrylic Acid (EAA) Market
Why this study is strategically relevant for 2026 decision cycles
- Supply‑chain clarity in a shifting cost environment: The report synthesizes recent feedstock and pricing dynamics—highlighting late‑2025 downward pressure on EAA pricing driven by elevated inventories and regional ethylene movements—to help procurement and operations teams stress‑test sourcing strategies and feedstock hedges.
- Regulatory inflection points that drive product choices: We map the evolving regulatory landscape (FDA, EU food‑contact rules and emergent recyclable‑film mandates in the EU and Japan) onto product development and commercial strategy, enabling teams to prioritize grades and certifications in their 2026 roadmaps.
- Competitive moves and capability gaps: The benchmarking and competitive playbooks identify where global majors are consolidating advantages—feedstock security, high‑MFI formulations, recycled/renewable initiatives—and where challengers can capture share via niche technical differentiation or regional agility.
- Risk and scenario planning: The forecast workbook includes stress scenarios for raw material volatility, regulatory tightening and accelerated circularity adoption—tools that are directly usable in capex and commercial planning cycles for 2026.
Market drivers and emergent themes
Three high‑level themes shape the near‑term EAA outlook and should be at the center of 2026 strategy conversations:
- Functional differentiation drives value capture: Advances in high‑melt‑index formulations, improved adhesion without primers, and food‑contact compliant grades are steering buyer preferences away from commodity blends toward performance‑led specifications. These shifts increase the premium available to technology‑led producers.
- Circularity and feedstock security reshape investments: Recycled and renewable‑based polymer initiatives are no longer optional R&D projects; they are strategic responses to regulatory pressure and buyer demand. Recent large‑scale recycling milestones from major producers indicate the pace at which circular applications can scale, but also point to first‑mover implications for feedstock sourcing.
- Regulatory convergence and packaging targets: Tighter rules on recyclability and food‑contact migration are raising the bar for qualification cycles and supplier documentation—affecting time‑to‑market and commercialization costs for new grades.
What’s inside the full report (practical contents for teams)
The full PW Consulting report is designed as a working toolkit for executives, commercialization leads and investment committees. Key deliverables include:
- Market sizing and a forward financial model (2020–2032) with scenario toggles to run sensitivity analyses across price, volume and feedstock shocks;
- Segment‑level demand maps across region, application and product type (note: detailed numeric splits are accessible exclusively in the full dataset);
- Supplier scorecards and a strategic heatmap assessing technological strengths, feedstock agreements, sustainability roadmaps and manufacturing footprints;
- Go‑to‑market playbooks for converters and brand owners—covering grade selection, qualification pathways for food‑contact and recyclable film compliance, and cost‑to‑serve optimization;
- Capex and M&A decision frameworks including an acquisition target rubric and integration checklists tailored for EAA assets;
- Technical annex: polymer performance matrices, melt‑flow index considerations, and compatibility guidance for multilayer structures and coating applications;
- A risk register with mitigation templates for pricing volatility, regulatory delays, and supply disruptions.
Competitive landscape: reading the tactical moves
The market exhibits a concentrated structure among a few global incumbents, while a broader set of regional and specialty players compete in tailored niches. Our proprietary concentration analysis indicates a meaningful share advantage among top players, with room for strategic disruption by firms that combine technical differentiation with regional execution speed.
Core competitors examined in detail in the report include leaders across North America, Europe and APAC. Highlights from our competitive analysis:
- Major global producers have doubled down on feedstock security and premium grade development. Publicly announced supply agreements and high‑MFI launches signal a move to protect margins via volume throughput and processing advantages.
- Producers with integrated specialty portfolios (adhesives, coatings and barrier resins) are leveraging cross‑sell opportunities, reducing qualification friction for brand owners seeking fewer single‑source suppliers for multilayer structures.
- Regional champions in Asia are scaling capacity and aligning with converter networks to capture fast‑growing local demand; their advantage is speed‑to‑market and localized formulation blends.
- Specialty formulators and dispersion houses target higher‑value niches—inks, paper coatings and migration‑sensitive food applications—where technical expertise and small‑batch agility command premium margins.
We document and analyze recent corporate events—such as expanded ethylene supply agreements, high‑MFI product launches, recycled polymer scale‑ups and enhanced metal‑adhesion series—to show how these moves materially shift competitive positioning and affect supplier selection criteria for converters and brand owners.
Pricing, raw materials and regulatory signals you cannot ignore
Late‑2025 dynamics showed downward rate pressure on EAA list prices in major regions amid stable to lower feedstock costs and higher inventories. Average market pricing indicators and regional QoQ movements are charted in the model so clients can simulate margin impacts under alternative procurement strategies.
Regulatory compliance—especially food‑contact certifications and recyclability mandates—now directly informs product roadmaps. The report maps regulatory requirements against likely certification timelines, exposing potential bottlenecks and suggesting mitigation pathways (e.g., pre‑qualification partnerships with major converters, early engagement with compliance labs).
Actionable strategic playbook for 2026
For executive teams preparing 2026 plans, the research supports three concrete actions:
- Prioritize feedstock and logistics resilience: Secure contractual flexibility (take‑or‑pay vs optional volume), diversify suppliers across regions and model the cash‑flow impact of inventory swings.
- Invest selectively in high‑value grades and certifications: Focus R&D and capex on grades that offer clear processing or compliance advantages—these will capture the premium in a market where overall growth is steady but competitive.
- Leverage partnerships to accelerate circularity: Consider alliances with reclaimers, converters and brand owners to co‑fund qualification work for recycled/renewable‑based EAA blends and to shorten time‑to‑market for compliant multilayer solutions.
Why PW Consulting’s report is the right input for your 2026 decision cycle
Our study converts raw market statistics into executable insights—combining a robust forecast model with supplier intelligence, technical guidance and commercial playbooks. The depth of the analysis supports immediate use cases (procurement negotiation, capex prioritization, product launch sequencing) while the proprietary datasets allow for customized sensitivity testing aligned to corporate risk tolerances.
Note on data access: this preview intentionally omits the full set of segment‑level numeric tables and regional/application breakdowns to preserve the report’s role as a subscription asset. The full dataset includes granular annual figures, regional demand matrices, product‑type roll‑ups and converter‑level adoption cases—available to licensed clients and partners.
Next steps
- Download the complete report for the full model and subscriber‑only segmentation tables to run organization‑specific scenarios.
- Engage with PW Consulting for a tailored briefing that aligns the forecast to your asset base, procurement contracts and commercial pipeline.
- Consider an accelerated workshop to convert the study’s playbooks into a 90‑day execution plan for 2026.
Our 2026 preview underscores a central point: the EAA market is growing and maturing in ways that reward strategic clarity. Firms that combine feedstock foresight, technical differentiation and regulatory readiness will capture disproportionate value. The full PW Consulting report provides the quantitative backbone and tactical roadmaps required to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Ethylene-acrylic Acid (EAA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


