



PW Consulting: Glass Tableware Market to Reach USD 21.08 Billion by 2032 at 7.91% CAGR

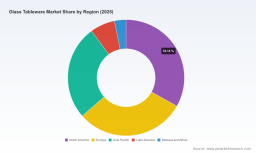
Glass Tableware Market — 2026 Strategic Preview for Decision‑Makers
As PW Consulting’s Senior Strategic Advisor for Consumer Goods, I present a focused, decision‑centric preview of the global Glass Tableware Market that primes executives for high‑impact moves in 2026. Anchored on a 2025 base year, the market has expanded materially since 2020 and—at a compounded annual growth rate of 7.91%—is projected to reach just over USD 21 billion by 2032. This briefing synthesizes the macro trajectory, near‑term shocks, competitive dynamics, and a pragmatic playbook. Per our “trailer” approach, we surface actionable frameworks and strategic implications while reserving the granular segmentation datasets for the full report.
Glass Tableware Market
Why 2026 Is a Strategic Inflection Point
-
Demand momentum versus input pressures: The market’s recovery and premiumization since 2020 have been durable, but margin architectures are under near‑term strain from rising input costs and policy shifts. Executives must balance revenue growth levers with cost‑push volatility.
Glass Tableware Market -
Policy‑driven cost shocks: A major export policy change announced in early 2026 removes VAT export rebates for glass products in a key manufacturing base, effectively increasing export economics for affected suppliers by a substantial single‑digit to low‑double‑digit percentage. This is a forcing event for pricing, sourcing, and contractual renegotiations.
Glass Tableware Market -
Supply‑side inflation: Producer price indicators and spot float‑glass benchmarks show elevated input pricing versus pre‑pandemic levels—creating a persistent cost floor for producers that will influence inventory, capitalization, and procurement strategies throughout 2026.
What Our Glass Tableware Market Report Delivers (Practical, Executable)
-
Market sizing and forward projections (2026–2032) tied to demand vectors and macroeconomic sensitivity models.
-
Cost‑to‑serve and margin decomposition templates that map raw materials, energy, labor, and logistics to SKU profitability.
-
Buyer and channel playbooks for retail, e‑commerce, and hospitality procurement—framed as negotiation levers and assortment strategies.
-
Supplier heatmaps, capability assessments, and an OEM/ODM partner scorecard to accelerate nearshoring or dual‑sourcing decisions.
-
Regulatory impact assessments and cost pass‑through models calibrated for scenario planning (including tariff and tax shocks).
-
M&A and consolidation playbooks: target archetypes, diligence checklists, and integration scorecards for value capture in a fragmented market.
-
Commercialization templates for premiumization, sustainable product lines, and branded vs. private‑label channel economics.
Each deliverable is built to be directly usable by product, procurement, commercial, and corporate development teams—reducing analysis time and enabling faster execution.
Structural Dynamics Shaping 2026 Decisions
-
Premiumization and experience demand: Elevated at‑home dining and a refined hospitality rebound continue to shift mix toward premium stemware and differentiated drinkware formats. This is a durable demand lever for margin expansion if manufacturers can manage unit economics.
-
Fragmented industry structure: Market concentration metrics indicate relatively low top‑three and top‑five aggregate shares—pointing to an industry that is ripe for strategic consolidation, scale plays, and regional champions. The fragmentation also sustains opportunities for niche players to defend value through design, heritage manufacturing, or sustainability credentials.
-
Input cost volatility: Producer Price Index readings for glass manufacturing and elevated float‑glass spot prices in industrial hubs show that raw material and energy costs are significant drivers of near‑term margin volatility. Companies without robust hedging or variable cost pass‑through mechanisms face compressed profitability.
-
Regulation and trade policy: The removal of export VAT rebates in a major supplier country represents a discrete shock to traditional global sourcing models and will accelerate both commercial and operational responses—ranging from price renegotiation to re‑routing production footprints.
-
Sustainability and compliance: Lead‑free formulations, recyclable content, and energy‑efficient production are shifting from “nice‑to‑have” to procurement prerequisites for several global retail and hospitality customers.
Competitive Landscape — Strategic Positioning and Implications
-
Legacy US manufacturers (example: Libbey Inc.) : These players combine scale manufacturing in multiple geographies with strong foodservice and retail channels. Their strategic advantage lies in integrated supply chains and brand recognition—making them primary partners for large commercial buyers and potential consolidators seeking manufacturing backbone.
-
Heritage and artisanal producers (e.g., Blenko Glass, Mosser Glass) : Artisan stories, hand‑blown or pressed collections, and limited SKUs create defensible premium niches. These firms are well‑positioned to capture consumer willingness to pay for provenance and differentiated design, but they must digitize go‑to‑market models to broaden reach.
-
Large regional champions (e.g., Nadir Figueiredo) : Broad SKU assortments and deep domestic distribution enable scale economies and resilient export flows—yet exposure to regional trade policy shifts necessitates hedged export strategies and closer collaboration with multinational buyers.
-
High‑volume OEM/ODM clusters (East Asia manufacturers) : Several large manufacturers provide catalog and custom solutions for hospitality and retail buyers. Their cost competitiveness is being tested by policy headwinds and rising input prices, but their design-to-delivery speed remains a competitive moat for large private‑label programs.
-
Design‑led European houses (e.g., Bormioli Rocco, AKCAM) : Reputation for optics and premium stemware supports profitable export and brand partnerships. Trade show presence and new collections signal continued investment in design as a route to margin improvement.
-
Strategic note: recent product launches and trade show activity by design‑oriented suppliers, and a new product catalog from a leading OEM, highlight how companies are pursuing both product innovation and channel momentum in early 2026. Concurrently, the export rebate policy change for a major exporter is catalyzing supplier repricing and sourcing reconsideration.
2026 Tactical Playbook — Actions Leaders Should Prioritize Now
-
Prioritize cost transparency: Implement SKU‑level cost models that reflect updated raw material and energy price indices. Convert these into customer‑level profitability dashboards within 90 days.
-
Reprice contracts with scenario clauses: Insert short‑term escalation clauses for material and energy costs, and negotiate shared cost‑mitigation mechanisms with key account customers.
-
Dual‑source and nearshore: Rapidly qualify alternative production nodes and flexible converters to mitigate single‑country policy shocks. For importers, consider local assembly or light manufacturing to preserve price competitiveness.
-
Accelerate premium SKUs and limited‑edition runs: Leverage design and artisanal partnerships to expand high‑margin assortments while maintaining a lean manufacturing footprint for commodity lines.
-
Hedge raw material exposure: For scale producers, secure multi‑year supply contracts or indexed procurement agreements for soda ash, silica, and energy; for smaller producers, form purchasing consortia to access scale pricing.
-
Deploy a focused M&A radar: Target complementary regional players with distribution strength, artisan brands for direct‑to‑consumer access, or niche manufacturers that can boost product mix and margin.
-
Fast‑track sustainability certification: Validate recyclable content and energy footprints for faster procurement approvals from institutional hospitality and retail customers.
Scenario Triggers and Decision Thresholds
-
Cost shock trigger: If producer price indices or spot float prices rise beyond predefined thresholds, activate contingency margins and suspend promotional programs until pass‑through is negotiated.
-
Policy shock trigger: For exporters affected by rebate removal, evaluate a three‑month tactical price increase, then decide between structural relocation or sustained margin acceptance based on customer elasticity tests.
-
Demand softening trigger: If hospitality channel orders fall by a quantifiable percentage year‑over‑year, shift production to private label and retail promotions focused on value and multipacks.
Conclusion — Why This Preview Matters for 2026
2026 will test leadership teams on three fronts: the ability to translate demand gains into sustainable margins, to respond nimbly to policy and input‑cost shocks, and to convert industry fragmentation into strategic advantage through targeted consolidation and brand building. With the market on an elevated growth trajectory from the 2025 base and a forecast that takes us beyond USD 20 billion by 2032, the choices companies make in the next 12 months will disproportionately determine relative market share and profitability for the remainder of the decade.
This article is an executive preview. The full PW Consulting Glass Tableware Market Report contains the granular segmentation, regional channel economics, SKU‑level profitability matrices, and the proprietary models we reference here—tools designed to support tactical decisions and boardroom strategy workshops. For access to the complete dataset and a tailored briefing for your company, please contact our industry practice.
For detailed analysis of this topic, please visit the official page: Glass Tableware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


