



PW Consulting: PEEK Market to Hit USD 1,562.5M by 2032 at 7.96% CAGR

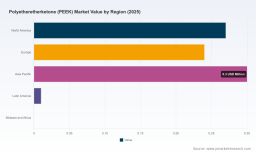
PEEK Market 2026: Strategic Imperatives for Boards and Business Units
As companies plan capital allocation and go-to-market strategies for 2026, Polyetheretherketone (PEEK) has moved from niche high-performance polymer to a strategically important material class across aerospace, medical, advanced mobility and industrial applications. Our PW Consulting PEEK Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, supply-chain stress points, regulatory inflection points and competitor intent into an operational roadmap that senior executives can use to align investment, sourcing and product strategies.
Polyetheretherketone (PEEK) Market
Why this study matters for 2026 decision cycles
-
Market momentum is demonstrable: the addressable PEEK market has exhibited steady expansion through the mid-2020s and, under our central forecast, continues to grow at a compound annual growth rate of approximately 7.96% across 2026–2032. This trajectory implies meaningful revenue upside for incumbents and credible entry economics for well-capitalized challengers.
Polyetheretherketone (PEEK) Market -
Strategic timing: 2026 is a hinge year. Many suppliers completed capacity moves in 2024–2025 and several began commercial ramp-ups by early 2026. Decisions taken this year on capacity, localization and partnerships will determine access to APAC and advanced-application customers for the next five years.
Polyetheretherketone (PEEK) Market -
Complex value-chain sensitivity: PEEK is a derivative of aromatic feedstocks with concentrated upstream exposures and new handling regulations that raise operating complexity. Pricing, logistics and regulatory compliance now materially influence margin and time-to-market.
Macro snapshot (concise, decision-relevant)
-
Base and forecast framing: our dataset uses 2025 as the base year and projects through 2032. By 2025 the total PEEK market reached nearly one billion USD (reported in USD, revenue unit: Million), and our models show continued growth to mid-next-decade levels under a mid-case scenario. This scale justifies multi-year investments in both incremental capacity and specialty formulation R&D.
-
Market structure: concentration is meaningful. The top three producers control a material share of global supply, and the top five consolidate an even larger portion. This structure creates both strategic risk (single-source exposures) and commercial opportunity (premiumization and selective partnerships).
What the full report delivers (practical, executable content)
-
Transparent sizing and forecasting: a reconciled historical series (2020–2025) and scenario-driven forecasts (2026–2032) using bottom-up production and demand balancing. We provide multiple demand scenarios—base, upside and downside—linked to adoption rates in target end-markets and alternative polymer substitution dynamics.
-
Supply-chain and cost analytics: a detailed mapping of feedstock linkages, with sensitivity analyses quantifying the P&L impact of feedstock price swings, transport surcharges and labor-cost inflation. The model lets procurement teams stress-test supplier contracts under raw-material shock scenarios and regulatory compliance cost ramps.
-
Regulatory and handling playbook: practical checklists and process changes required to comply with evolving pellet and polymer handling rules—covering floor-to-facility controls, worker safety training, and traceability steps needed to meet global OEM requirements.
-
Commercial and product strategies: segmentation frameworks for premium-grade vs. commodity PEEK, product roadmaps for filled vs. unfilled grades, and go-to-market recommendations tailored to aerospace, medical and high-voltage electrical applications. Note: the report contains granular splits by region, type and application reserved for subscribers to protect competitive sensitivity.
-
Financial and M&A playbook: valuation comps, runway analysis for brownfield vs. greenfield expansions, and divestiture/bolt-on acquisition screening criteria for corporates seeking to capture adjacent capabilities (compounding, extrusion, machined semi-finished goods).
-
Scenario planning tools: downloadable Excel models provide customizable scenarios for capex phasing, contract hedging, and pricing strategies by customer segment.
Competitive landscape: what to watch in 2026
The competitive map is dominated by a handful of specialist producers and vertically integrated manufacturers. Key market players profiled in the study include:
-
Victrex plc (Thornton Cleveleys, Lancashire, UK) — a market-leading producer of PEEK polymers and forms. Recent moves include new polymer grades and APAC capacity ramp-up, signaling a strategy to defend OEM relationships by expanding grade breadth and geographically diversifying production footprints.
-
Syensqo (Brussels, Belgium) — noted for KetaSpire and Ajedium grades that target automotive and aerospace applications. Recognition for innovation (e.g., advanced film technologies used in e-motors) underlines the role of differentiated formulations in winning specification battles.
-
Ensinger GmbH (Nufringen, Germany) — a specialist in semi-finished and machined PEEK components, serving injection-molding and custom-part markets. Their model shows how downstream value-add can insulate margins amid upstream feedstock volatility.
-
Zeus Industrial Products (Orangeburg, SC, USA) — focused on tubing, fiber and drawn products for medical and aerospace applications; an example of product-line specialization that captures higher-margin niches.
-
Jilin Joinature Polymer Co., Ltd. (Changchun, Jilin, China) and Panjin Zhongrun High Performance Polymer Co., Ltd. (Panjin, Liaoning, China) — regional producers targeting both domestic and export markets with a range of granules and powders; their competitive behavior is central to APAC pricing dynamics and local OEM sourcing strategies.
Across these players we observe two primary strategic postures: (1) scale and grade breadth to lock-in OEMs that demand long qualification cycles, and (2) niche specialization to capture premium applications and faster commercialization windows. The full report contains company scorecards, capacity maps and strategic recommendations for engagement (JV, tolling, long-term off-take) tailored to supplier profiles.
Industry dynamics and tail risks executives must not ignore
-
Feedstock volatility: recent months have seen observable movement in bisphenol and related feedstock prices in major producing regions. Our modeling accounts for both spot-price shocks and structural cost increases driven by upstream decarbonization investments—an important margin tail for piston-driven polymer makers.
-
Regulatory mechanics: new rules for pellet handling and updated safety protocols for certain PEEK variants increase compliance overhead. These changes translate into CAPEX and OPEX impacts for midstream processors and contract manufacturers, as well as possible qualification delays for new product launches.
-
Logistics and transport surcharges: rising freight and handling costs in Q1–Q2 2026 have already pressured delivered prices. Buyers should assume periodic surcharges and include explicit escalation clauses in supply agreements.
-
Labor and upstream capex effects: upstream chemical producers are investing in lower-emission steam cracking and other upgrades, increasing production costs in the near term while reducing carbon risk longer term. This dynamic creates both cost pressure and an opportunity for brands to market lower-carbon polymer formulations.
Strategic recommendations for 2026 planning cycles
-
Secure multi-tiered supply: pursue blended sourcing strategies combining contracted volumes with spot access and tolling arrangements. Explicitly model the P&L impact of feedstock price swings and include pass-through mechanisms where feasible.
-
Qualify in parallel: reduce lead-time risk by running parallel qualification tracks (primary-supplier and an approved alternate) for critical OEM programs—this is especially important in aerospace and medical sectors with long approval windows.
-
Invest in grade differentiation: allocate R&D and application engineering budget toward formulations that reduce system-level costs (lighter weight, longer lifecycle, enhanced electrical insulation). Differential performance remains the strongest buffer against commoditization.
-
Plan for compliance cost: include pellet-handling and PEEK-specific handling protocol costs in 2026 operating budgets and supplier negotiations. Early adoption of compliance best-practices reduces qualification friction with leading OEMs.
-
Evaluate localized capacity: for companies serving APAC or intending to scale in medical/electronics, consider near-market manufacturing or contractual production in-region to mitigate logistics surcharges and accelerate lead times.
-
Monitor competitive capacity: track announced expansions and ramp timings. Where incumbents expand in near-term, expect pricing pressure in targeted product lines; consider countermeasures such as co-development or purchase guarantees to stabilize demand.
Conclusion: a pragmatic call to action
PEEK is no longer an experimental material class; it is a strategic choice with measurable top-line and margin implications. The coming 24 months will determine which companies capture durable share in high-growth, high-value applications. PW Consulting’s full report provides the granular segmentation, supplier scorecards, and scenario models that boards, CFOs and heads of manufacturing need to operationalize 2026 decisions—without revealing proprietary commercial detail here. For senior teams needing immediate decision support, our offer includes tailored briefings and custom sensitivity analyses to translate the report’s insights into executable roadmaps.
Access the full subscription report to obtain the detailed regional and application splits, downloadable financial models and prescriptive supplier engagement playbooks that supply-chain, commercial and technology leaders require for 2026 execution.
For detailed analysis of this topic, please visit the official page: Polyetheretherketone (PEEK) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


