



PW Consulting: Motorcycle Carburetor Market to Grow at 4.25% CAGR Through 2032

Motorcycle Carburetor Market — 2026 Strategic Preview (PW Consulting)
This preview frames PW Consulting’s comprehensive Motorcycle Carburetor Market study and explains its direct strategic value to executive teams debating product roadmaps, M&A, compliance investment, and go-to-market moves in 2026. It signals the key market dynamics, competitive posture, regulatory inflection points and pragmatic next steps — while intentionally withholding the granular regional and application splits that are contained in the full report to preserve the “trailer” experience and motivate access to source intelligence.
Motorcycle Carburetor Market
Quick macro view you can act on
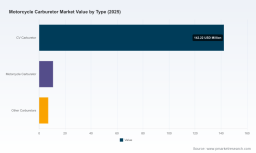
The market for motorcycle carburetors has demonstrated steady expansion through the early 2020s, rising from roughly USD 122.4 Million (2020) to about USD 160.1 Million in the report base year (2025). Our forecast period (2026–2032) assumes a compound annual growth rate of 4.25%, taking total market size toward an expected USD 212.8 Million by 2032. That trajectory reflects a mature product category that continues to generate value across OEM, replacement and performance aftermarket channels even as electrification and emissions regulation force structural change.
Motorcycle Carburetor Market
Why this study matters to corporate decision-makers in 2026
- Prioritize capital: Understand which parts of the product portfolio require certification spend versus those to phase out.
- Risk management: Quantify supply‑chain exposure to raw‑material volatility (aluminum, zinc, engineering plastics) and identify realistic de‑risking tactics.
- Competitive positioning: Map where global leaders and nimble regional OEMs create margin and volume advantages.
- M&A and partnerships: Identify targets and JV approaches to capture aftermarket service revenue and maintain OEM relationships.
- Regulatory planning: Translate regulatory timelines into certification and labeling roadmaps to avoid market access interruptions.
Market dynamics shaping strategic choices
Several enduring and emergent dynamics govern strategy formulation for 2026 and beyond:
Motorcycle Carburetor Market
- Demand composition: The market shows resilient demand across conventional motorcycle segments (OEM production and replacement markets) with notable upside in performance and aftermarket upgrades for racing and enthusiast applications.
- Regulatory pressure: Emissions and fuel‑system monitoring requirements increasingly dictate product design and cost. Compliance timelines are compressing certification windows and raising the cost of entry for aftermarket suppliers.
- Material and cost efficiency: High-volume manufacturers rely on stable supplies of aluminum, zinc and plastics to maintain cost‑competitive castings and housings. Raw‑material supply constraints or trade disruptions can rapidly erode margin, especially for suppliers serving price‑sensitive emerging markets.
- Fragmentation and concentration: The category is characterized by a competitive mix of large OEM-specialists, performance-focused incumbents and numerous regional producers serving entry-level segments; market concentration is moderate, which creates opportunities for consolidation and capability-led differentiation.
- Transition risk from electrification: Small‑displacement urban mobility faces explicit regulatory pathways toward zero‑emission certification in some jurisdictions, creating near-term demand shifts and longer-term structural substitution risk for carburetor suppliers.
Regulatory shocks to build into 2026 planning
Recent and near-term regulatory changes materially affect product roadmaps and go‑to‑market strategies:
- Aftermarket labeling requirements for emission‑critical parts now impose traceability and documentation obligations on suppliers and distributors — operationalizing these requirements is an immediate commercial priority.
- Stringent emissions certification requirements (NOx/HC thresholds and fuel‑system monitoring mandates such as OBD) increase the cost and time required to achieve road‑legal status for carburetor‑equipped motorcycles in key markets.
- Some jurisdictions are setting explicit timelines to require zero‑emission certification for sub-50cc street motorcycles, accelerating segmentation of demand and making near‑term planning for product migration or service diversification essential.
Competitive landscape — who matters and why
The competitive field mixes legacy OEM specialists, performance leaders and high‑volume regional producers. Understanding each cluster’s strategic intent informs partnering, pricing and product decisions.
- Keihin Corporation (Tokyo, Japan) — A global leader with deep OEM ties and high‑performance product families. Their strength is in piston‑type designs and long-standing OEM relationships that set performance and quality benchmarks.
- Mikuni Corporation (Tokyo, Japan) — Recognized for high‑flow and racing solutions, Mikuni’s product cadence often signals where premium aftermarket demand is heading.
- Dell’Orto S.p.A. (Cabiate, Italy) — European slide‑type specialist with a strong motorsport and aftermarket positioning; valuable for understanding premium European customer requirements.
- Walbro LLC (Cass City, USA) — Known for robust float carburetors and pragmatic feature sets suited to small engines and reliable low-cost platforms.
- Chinese OEM and aftermarket groups — Several well‑established manufacturers provide high‑volume, cost‑competitive solutions for emerging‑market OEMs and replacement channels; their scale and customization capabilities make them primary players in volume segments.
- Regional specialists (India, China, Europe) — Local manufacturers often combine tight cost control with fast time‑to‑market for derivative SKUs, posing both partnership opportunities and competitive threats depending on geography and channel.
Overall market concentration is moderate, with the top tier of suppliers accounting for a meaningful but far from dominant share — a structure that favors focused consolidation and vertical integration plays for acquirers willing to invest in scale and certification capability.
2026 playbook — actionable strategic options
For leadership teams, the following choices translate insights into executable plans during 2026:
- Fast‑track certification: Allocate a dedicated budget and cross‑functional team to achieve emissions and OBD compliance in target jurisdictions; treat certification as a market‑access enabler rather than a cost center.
- SKU rationalization and modularization: Reduce NPI cycle time and certification complexity by converging designs onto modular platforms that can be tuned for regional needs with minimal re‑certification.
- Supply‑chain de‑risking: Negotiate multi‑year agreements with metal and plastics suppliers, diversify sourcing footprints, and assess light‑engineering redesigns to reduce material intensity.
- Dual channel strategy: Differentiate OEM partnerships from aftermarket offerings — premium, certified lines for OEMs and performance enthusiasts; lean, cost‑optimized platforms for replacement markets.
- M&A and partnerships: Target bolt‑on acquisitions to acquire certification expertise, expand aftermarket service capabilities, or gain manufacturing scale in priority regions.
- Service and retrofit offerings: As regulation squeezes new unit demand in some urban segments, monetize service, retrofit and conversion kits, and develop lifecycle revenue streams beyond unit sales.
What the full PW Consulting report delivers (high‑utility components)
The complete study bundles actionable modules designed for boardrooms and strategy teams:
- Verified market sizing and forecast model (2020–2032) with scenario variants and sensitivity analysis.
- Regulatory matrix linking region‑specific rules to product design and certification timelines, plus a compliance cost calculator.
- Competitive profiles and capability heatmaps covering technology, certification track record and channel focus for key suppliers.
- Supply‑chain risk scoring and mitigation playbooks for raw materials and contract manufacturing dependencies.
- Go‑to‑market playbooks for OEM, aftermarket and performance segments, including pricing buckets and margin expectations.
- M&A screening toolkit and shortlists of potential targets by strategic objective (scale, certification, regional access).
- Operational checklists: 90‑, 180‑ and 365‑day execution plans to convert strategy into measurable milestones.
Note: granular regional and application splits, detailed segment revenue breakdowns and model files are intentionally reserved for the full report to preserve the strategic advantage of subscribers and clients.
90‑day priority checklist for executive teams
- Initiate a quick compliance gap analysis for all carburetor SKUs against priority market regulations; identify immediate non‑compliant SKUs and quantify certification timelines.
- Lock in critical raw‑material contracts or hedges for aluminum and zinc to stabilize unit cost assumptions for FY26 planning.
- Pilot a modular SKU program: select one platform to rationalize and certify as a demonstrator for faster market access.
- Engage potential technical partners (performance OEMs, certification labs) to accelerate product homologation and explore co‑branded aftermarket opportunities.
- Run a shortlist review for targeted acquisitions or minority investments to rapidly gain certification capability or aftermarket reach.
Concluding perspective
The motorcycle carburetor market in 2026 offers a mix of stability and disruption: steady aggregate growth with pockets of regulatory and technological risk. For companies that treat certification, supply‑chain resilience and platform modularity as strategic levers, the market still yields profitable opportunities across OEM, replacement and performance channels. PW Consulting’s full report supplies the segment‑level maps, regulatory timetables, supplier profiles and model files you need to convert the high‑level options above into prioritized investments and measurable returns. Access to the complete dataset is the next practical step for teams that need to make defensible, time‑sensitive decisions in 2026.
For detailed analysis of this topic, please visit the official page: Motorcycle Carburetor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


