



PW Consulting: Heat Cost Allocator Market Poised for 6.98% CAGR (2026–2032)

Heat Cost Allocator Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a concise but strategically rich overview of our Heat Cost Allocator Market study — an evidence-based briefing designed to inform executive decision-making in 2026. The market is moving from regulatory-driven adoption to feature-driven differentiation: electronic allocators, dual-sensor architectures, IoT-readiness and tamper-resilience are no longer optional. Our analysis synthesizes multi-year market dynamics, regulatory headwinds/opportunities, vendor positioning, and actionable go-to-market playbooks—while preserving the proprietary granularity that powers transaction-grade decisions. For full datasets, regional and application splits, and model assumptions, please consult the full report on our website.
Heat Cost Allocator Market
Market at a Glance: Growth Trajectory and Structural Context
Between 2020 and 2025 the global heat cost allocator market expanded materially, and PW Consulting’s base-year assessment (2025) positions annual revenue near the three-quarters of a billion USD mark. Our forecast from 2026 through 2032 projects sustained expansion, with the market approaching the mid-to-high single-digit compounded annual growth rate reflected in a projected increase to over USD 1.2 billion by 2032. This trajectory — a CAGR of approximately 6.98% across the forecast window — reflects a convergence of regulatory mandates, building electrification strategies, and rising demand for consumption-based billing and energy transparency in multi-occupant properties.
Heat Cost Allocator Market
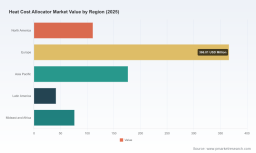
Two structural facts are essential for strategic planning: first, the market remains moderately fragmented (our concentration analysis shows the top three and five vendors capture a minority share of total revenue), and second, segmentation across regions, device types and applications produces distinct pockets of margin, product requirements and route-to-market complexity. These dynamics mean that scale is valuable but not sufficient; winning strategies combine technical differentiation, channel flexibility and regulatory-compliant roadmaps.
Heat Cost Allocator Market
Why 2026 is a Strategic Inflection Point
- Regulatory crystallization: By the end of 2025 most EU member states had implemented the EU Energy Efficiency Directive (EED II) and national mandates such as amended heating cost ordinances, establishing remote readability and consumption-based allocation as the baseline compliance requirement in many multi-apartment contexts. Parallel moves in Asia (notably South Korea’s updated Green Building criteria) extend compliance imperatives to new markets.
- Standards raising the technical bar: European standardization (EN 834 and associated national implementations) now codifies features such as dual-sensor systems, tamper detection and remote-read interfaces. Vendors and specifiers who do not align product roadmaps risk obsolescence or retrofit cycles.
- Digital outcomes matter: Building owners and energy managers increasingly value data continuity, integration with building management systems (BMS), and service-based billing models. The vendor value proposition has shifted toward platform + device + services bundles.
Report Contents — Practical, Executable, and Transaction-Ready
Our Heat Cost Allocator Market report is structured to be operationally useful for corporate strategy, commercial planning, procurement and M&A teams. High-level contents include:
- Market sizing, historical performance (2020–2025) and forward-looking revenue modelling (2026–2032) with scenario sensitivity for regulatory acceleration and technology substitution.
- Competitive landscaping with profiles of incumbent and challenger vendors, product mapping (features, interfaces, readout modalities), and channel strategies.
- Regulatory impact assessment and compliance roadmaps tailored to the EU, selected APAC markets, and North America.
- Go-to-market playbooks: OEM sales strategies, dealer & installer channel economics, and public-sector tender positioning.
- Technology deep dives: dual-sensor architectures, anti-tamper methods, radio/AMR/IoT interfaces, and integration patterns with BMS and meter data management systems.
- Procurement and total cost of ownership models: unit pricing dynamics, retrofit vs. new-build decision matrices, and service revenue opportunities (remote reading subscriptions, analytics).
- M&A and partnership screen: target criteria, valuation multiples observed in adjacent metering segments, and integration risk checklists.
- Case studies and deployment playbooks from representative multi-family building and housing association pilots, illustrating installation workflows, commissioning protocols and billing outcomes.
- Primary datasets and modelling workbooks (proprietary), available to licensees for scenario customization.
Competitive Landscape: Who Matters and Why
The vendor field comprises established metering and building-technology firms alongside specialized allocator manufacturers. The market’s moderate concentration gives room to differentiated players to scale via product features or channel partnerships. Below I summarize the strategic posture of the core competitors evaluated in the study; readers should reference the report for a comparative feature matrix and procurement scorecards.
- QUNDIS GmbH (Erfurt, Germany) — A focused electronic-allocator specialist with proven radio-readout platforms. Strengths: deep domain expertise in consumption-based billing hardware, strong installer relationships in core European markets. Strategic implication: ideal partner for scalable AMR rollouts where robust radio ecosystems exist.
- Engelmann Sensor GmbH (Wiesloch, Germany) — Offers flexible electronic allocators and recently launched an “all-in-one” Unifix solution (January 2026) designed for broad compatibility with existing radiator plates. Strengths: product adaptability and installer-friendly design. Strategic implication: accelerates retrofit programs and reduces installation friction; watch for aggressive volume bids into EU public housing tenders.
- Brunata A/S (Minol-ZENNER Group, Herlev, Denmark) — Combines hardware with IoT-enabled remote reading and enterprise billing systems. Strengths: integrated services and cross-border execution. Strategic implication: appealing to housing associations seeking turnkey metering-to-billing solutions.
- Danfoss A/S (Nordborg, Denmark) — Brings dual-sensor technologies and strong engineering credentials. Strengths: R&D scale, industrial-grade product reliability. Strategic implication: positioned well for standards-driven upgrades where performance characteristics (e.g., dual-sensor accuracy) become specification gates.
- Resideo Technologies, Inc. (Charlotte, USA; EMEA ops in Germany) — Leverages AMR/walk-by readout experience and broad channel coverage. Strengths: channel breadth and aftermarket service capability. Strategic implication: viable for hybrid AMR deployments and markets where walk-by remains cost-effective.
- Zenner International GmbH & Co. KG (Saarbrücken, Germany) — Radio-capable allocators and a focus on integration with existing meter ecosystems. Strengths: regional network and OEM partnerships. Strategic implication: consolidation candidate for platform buyers seeking European scale.
- Diehl Metering GmbH (Haiger, Germany) — Known for anti-tamper features and sub-metering systems for multi-family buildings. Strengths: security-focused devices, installation robustness. Strategic implication: favored in markets and customers where tamper-resilience is mandated or highly valued.
- Siemens AG — Building Technologies (Munich, Germany) — Offers allocator products within a broader building automation portfolio. Strengths: systems integration capabilities and global enterprise footprint. Strategic implication: best positioned for large, integrated building automation projects.
- Apator S.A. (Poznań, Poland) — Competitive European supplier with a balance of cost and features. Strengths: price-competitive offerings and remote readout options. Strategic implication: contender in cost-sensitive retrofit programs.
- Sontex SA (La Chaux-de-Fonds, Switzerland) — Emphasizes installation simplicity and commissioning ease. Strengths: fast field deployment and configuration. Strategic implication: reduces soft-costs in large-scale retrofit rollouts.
Technology and Policy Signals: What to Prioritize in 2026
- Compliance-first product roadmaps: Dual-sensor designs, certified tamper detection, and remote-read interfaces are now minimum viable features in regulated markets. Product development timelines should be compressed to meet procurement cycles starting in 2026.
- Platform thinking: Hardware-only strategies are commoditizing. Vendors that embed secure telemetry, API-first integration and analytics will capture recurring service margins.
- Installer economics: Retrofit success hinges on reducing on-site complexity. Device formats that minimize customization and spare-part variations materially lower lifecycle costs.
- Data governance & security: With remote readout mandates, privacy and cybersecurity compliance are procurement filters for large housing providers and public tenders.
- Regulatory watch: The consolidation of EED II into national law and standards like EN 834 means procurement teams should treat compliance as an input to TCO modelling rather than a post-hoc checkbox.
Strategic Recommendations for 2026 Decision Cycles
- For vendors: Re-align R&D roadmaps to EN 834-compliant feature sets, accelerate modular platform development, and pursue channel partnerships that reduce installer friction. Consider targeted M&A to secure IoT middleware or local installation networks.
- For building owners and housing associations: Prioritize devices with proven remote-read capabilities and clearly articulated upgrade paths. Tender criteria should include commissioning time, data integration APIs and long-term service SLAs.
- For investors and M&A teams: Focus on assets that combine device IP with recurring data revenue or privileged access to long-duration contracts (housing associations, utilities). Valuations should account for regulatory tailwinds and retrofit execution risk.
- For system integrators: Build repeatable integration templates for BMS and billing systems; offer staged rollouts that demonstrate ROI within 12–24 months to reduce procurement friction.
Closing: The Value PW Consulting Brings
Our Heat Cost Allocator Market study is intended as both an intelligence engine and a decision-making toolkit. The macro picture — markets growing from mid-2020s base levels toward over USD 1.2 billion by 2032 at a near 7% CAGR — confirms a commercially attractive space. Yet the competitive and regulatory mosaic ensures that commercial outcomes will vary widely by product architecture, channel strategy and compliance posture. PW Consulting’s report contains the granular scenario models, vendor scorecards and procurement playbooks required to turn that growth into sustainable advantage.
For executives preparing procurement cycles, product launches, or M&A deliberations in 2026, the report provides prioritized actions and downloadable modelling assets. To access the full data tables, regional and application splits, and our proprietary vendor benchmarking, please refer to the full report page linked from PW Consulting’s Heat Cost Allocator Market dossier.
For detailed analysis of this topic, please visit the official page: Heat Cost Allocator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


