



PW Consulting: Flavor & Fragrance Market to Grow at 5.12% CAGR (2026–2032)

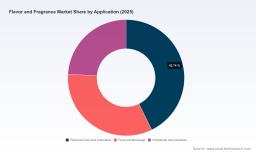
Flavor and Fragrance Market 2026: Strategic Imperatives from PW Consulting
As companies set budgets, allocate R&D spend, and shape M&A agendas for 2026, the Flavor and Fragrance (F&F) market requires a pragmatic synthesis of growth signals, supply-chain fragility, regulatory change, and technology-enabled product innovation. Our latest market study—anchored on a 2025 base year and covering 2020–2025 historical performance with forecasts to 2032—provides that synthesis. At the macro level the market expanded from an approximate USD 125.5 Million in 2020 to USD 157.5 Million in 2025 and, under our central scenario, is projected to reach roughly USD 223.1 Million by 2032, implying a compound annual growth rate of about 5.12% over the forecast window. These topline dynamics set the stage; the strategic questions are about where value will concentrate and how to defend and grow margin in an increasingly complex operating environment.
Flavor and Fragrance Market
Why this study matters for 2026 decision-makers
- Timing of strategic inflection: 2026 is a pivot year for many firms where near-term supply investments meet mid-term sustainability and regulatory constraints. Budgets approved this year will determine capacity, sourcing choices, and product pipelines that shape revenue through 2032.
- Capital allocation under pressure: Raw material volatility and compliance-driven reformulation are elevating working capital needs and capex priorities. Companies without a coherent capital allocation framework risk value dilution despite market growth.
- Opportunity cost of inaction: Incremental volume is available in the medium term, but winning it requires coordinated investments in natural ingredient supply chains, biotransformation platforms, and digital-enabled formulation to compress time-to-market.
Key market dynamics shaping strategic choices
The operational landscape is the result of three overlapping forces: cost and availability of raw materials, evolving regulatory frameworks, and technology-driven substitution of traditional chemistries.
Flavor and Fragrance Market
- Raw material pressure and feedstock risk: Agricultural commodity indices and classical feedstock outlooks have become a daily input into sourcing decisions. Recent monitoring shows vegetable oil and citrus feedstock price swings that translate directly into cost volatility for essential oils and common aroma chemicals. This requires procurement strategies that combine financial hedging, diversified sourcing geographies, and closer supplier partnerships.
- Regulatory tightening and transparency regimes: The introduction of chemical-disclosure initiatives and enhanced stewardship standards is reshaping formulation practices. Industry coordination bodies are accelerating risk-based stewardship and safety certifications—companies face a non-trivial reformulation load, and those who proactively map regulatory trajectories will have a decisive time-to-market advantage.
- Biotech and natural-alternative adoption: Biotransformation and fermentation-based solutions are moving from pilot-phase novelty to scalable commercial platforms. These routes create differentiated claims—natural equivalence, sustainability credentials, and supply resiliency—but they also require investment in new supplier ecosystems and regulatory dossiers.
Competitive landscape—practical implications
The sector’s competitive topology remains dominated by global integrators alongside specialized regional innovators. Strategic takeaways for 2026:
Flavor and Fragrance Market
- Global integrators: Large players with end-to-end capabilities continue to invest in biotechnology platforms, verticalization of natural supplies, and wellness-oriented product suites. Their scale enables R&D breadth and global customer reach, which translates into preferred partnership status for multinational customers looking to consolidate vendors and simplify supply chains.
- Specialists and niche players: Mid-sized and smaller companies lean into traceability, supplier transparency, and rapid customization for premium segments. Their advantage is speed and authenticity of sourcing claims; the trade-off is limited capital for large-scale capacity expansions.
- New entrants and adjacent moves: Ingredient incumbents and biotech companies are increasingly active in F&F through targeted product portfolios or JV models. Successful entrants typically combine technological distinctiveness with a clear go-to-market path into either food/bev or personal care channels.
Representative companies that exemplify these dynamics include global leaders who have publicly articulated strategies around biotech, natural ingredients, and sustainability-led innovation, as well as specialty houses that prioritize traceable sourcing and formulation agility. Recent industry moves—facility launches to secure key raw materials, portfolio introductions of biotransformed natural flavors, and targeted capacity expansions—underscore the speed at which strategic positioning is evolving.
Regulatory and supply shocks to model now
Decision-makers must explicitly model three near-term shocks when stress-testing plans for 2026:
- Commodity-price shock: Elevated vegetable oil and citrus feedstock indices increase production cost baselines and compress margin unless passed through or offset by formulation yields and premium positioning.
- Disclosure and compliance shock: New transparency mandates and strengthened stewardship standards require product-ingredient traceability investments and may extend product-registration timelines, particularly for export-focused formulations.
- Climate and sourcing shock: Supply concentration in vulnerable geographies (e.g., key vanilla-producing regions) increases geopolitical and climate exposure—firms without diversified sourcing and contingency inventories face disproportionate operational risk.
From insight to action: what the PW Consulting report delivers
We designed this study to be execution-oriented for corporate strategists, procurement heads, and business-unit leaders. Key deliverables include:
- Transparent market model: An integrated topline and bottom-up model (Excel-enabled) that explains our calculations for the 2020–2025 historicals and projects performance across 2026–2032. The model includes scenario toggles for price shocks, adoption rates of biotechnologies, and regulatory lag times.
- Commercial playbooks: Actionable go-to-market strategies for winning in personal care, food & beverage, and household segments—covering product positioning, pricing architecture, and route-to-market choices.
- Procurement & sourcing toolkit: A decision matrix for feedstock selection, hedging strategies, and supplier segmentation including supplier due-diligence templates and contingency planning protocols.
- M&A and portfolio optimization framework: Target-screening criteria, valuation sensitivities to feedstock and regulatory risk, and integration checklists tailored to F&F assets.
- Regulatory tracker & reformulation roadmap: A concise monitor of imminent regulatory exposures and a step-by-step reformulation playbook to preserve claims and compliance across major markets.
- Innovation pipeline assessment: Comparative diagnostics of traditional chemistry, natural extraction scale-up, and biotech-derived alternatives—mounted to commercialization timelines and cost-to-serve.
Note: this article intentionally presents high-level findings to support strategic thinking. The full report contains proprietary segment-level tables, regional breakouts, competitive market-share estimates, and vendor-level financial sensitivity analyses that are not reproduced here.
Practical strategic recommendations for 2026 planning
- Prioritize supply resilience over lowest-cost sourcing: Given ongoing commodity volatility, build tiered sourcing strategies that combine secured long-term contracts for critical feedstocks with short-term spot flexibility for commoditized inputs.
- Invest in scalable biotransformation selectively: Adopt a portfolio approach—fast-follower strategies in high-growth categories and first-mover investments where sustained differentiation and premium pricing are credible.
- Turn regulatory compliance into a commercial asset: Use transparency and stewardship credentials as market differentiators, particularly in consumer-facing premium segments where safety narratives enhance willingness to pay.
- Rationalize SKUs with margin-first logic: Apply SKU profitability analytics to reduce reformulation burden and reinvest savings into high-growth, high-margin SKUs supported by stronger marketing and channel alignment.
- Prepare M&A playbooks in advance: Define target profiles and post-merger integration playbooks now—competition for quality natural-ingredient assets is intensifying and will accelerate deal valuations.
How to use the full PW Consulting study
Use the report as an operational bridge between high-level strategy and plant-level execution. Examples of direct applications in 2026 decision cycles:
- Budget approvals: Translate scenario outputs into three-tier capex plans to align with conservative, central, and aggressive growth outcomes.
- R&D prioritization: Channel development funding to formulations and platform technologies with the clearest path to margin and compliance upside.
- Commercial negotiations: Leverage supplier and customer analytics to redesign contract terms that share risk of raw-material inflation.
- M&A screening: Apply our valuation sensitivities to accelerate or postpone transactions based on forward cash-flow resilience under varied commodity and regulatory scenarios.
Closing perspective
The F&F market is not a single, homogeneous growth story—it's a composite of resilient demand, concentrated pockets of premiumization, technology-driven substitution, and regulatory tightening. The topline trajectory is healthy, but translating aggregate growth into sustainable profitability requires hard choices in sourcing, platform investment, and portfolio design. PW Consulting’s report synthesizes the available public signals, proprietary modeling, and commercial playbooks into a single pragmatic reference for 2026 planning cycles.
For the full set of proprietary segment-level tables, regional analyses, competitor scorecards, and downloadable financial models that underlie these conclusions, please visit our report page or contact PW Consulting to arrange a briefing. The executive summary available online provides a guided view; the full dataset and operational toolkits are provided to clients and subscribers.
For detailed analysis of this topic, please visit the official page: Flavor and Fragrance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


