



PW Consulting: Sugar Sphere Market to hit USD 291.5M by 2032, growing at 6.2% CAGR

Sugar Sphere Market — 2026 Strategic Preview for Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our full Sugar Sphere Market research. This briefing interprets the macro trajectory, competitive dynamics, supply-chain sensitivities and the near-term strategic moves that will matter to executives planning for 2026. Consider this a high‑resolution trailer: it demonstrates the analysis depth and commercial implications we deliver, while intentionally withholding detailed subsegment tables and regional breakdowns to preserve the compelling value of the full study.
Sugar Sphere Market
Market at a Glance — Macro Trends That Shape Strategy
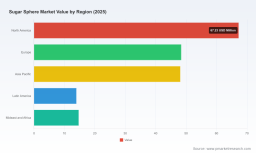
The global sugar sphere market is at an inflection point. After steady growth across the 2020–2025 historical window, the market registered roughly USD 192.3 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 6.2% through the 2026–2032 forecast period, with end‑period projections indicating a materially larger addressable market by 2032. This pace signals healthy, sustainable demand driven by continued adoption of multiparticulate sustained‑release formulations, stable demand from established pharmaceutical customers, and rising interest from specialty generic and CDMO clients.
Sugar Sphere Market
What this macro view means for 2026 decisions: a mid‑single digit CAGR provides room for expansion but does not eliminate price pressure or supply risk. Firms must balance capacity investments with margin protection and supplier flexibility.
Sugar Sphere Market
Market Dynamics and Structural Vulnerabilities
-
Raw material volatility and cost pressure. Our industry interviews and analyst datasets show that roughly half of pharmaceutical manufacturers are experiencing higher costs for high‑quality sucrose and coating materials used in sugar sphere production. At the agricultural level, sugarcane yields can swing meaningfully—by about 10–15% annually—due to weather variability, introducing a non‑trivial source of supply and cost volatility for manufacturers that rely on commodity sugar inputs.
-
Regulatory and quality thresholds are non‑negotiable. Sugar spheres used as multiparticulate cores for sustained‑release products are subject to stringent GMP controls and strict monograph specifications (USP, Ph. Eur.) for particle size uniformity, impurity limits and mechanical robustness. Compliance failures can lead to costly remediation timelines and customer losses.
-
Concentration and supplier dynamics. The market exhibits concentrated supply at the top end: the leading three and five suppliers capture the majority of commercial volumes, which creates both stability (scale) and fragility (dependent on a few capacity nodes). This structure makes strategic engagements with top suppliers essential for access to specialized size ranges and guaranteed throughput.
-
Technology and process differentiation. Incremental improvements in sphericity, non‑porous surfaces, and particle size control have become differentiators—particularly for high‑value sustained‑release applications. Manufacturers that combine process control, documentation and supply reliability command premium positioning.
Competitive Landscape — What Leading Players Reveal
Our competitive scan focuses on incumbent specialists and emerging low‑cost entrants, each with distinct implications for 2026 strategy:
-
Colorcon (United States) — A global leader whose SUGLETS® sugar spheres are positioned for drug layering and sustained‑release products. Recent capacity expansion at its Bazainville, France facility (completed in mid‑2024) increased production capability to meet rising global demand. Strategic implication: Colorcon’s investments set a higher service benchmark for on‑time supply and product range availability.
-
pharm‑a‑spheres GmbH (Germany) — Known for high mechanical stability and excellent sphericity achieved through controlled manufacturing processes. Their technological focus raises the bar on core quality for sophisticated formulations.
-
M.B. Sugars & Pharmaceuticals Limited (India) — A high‑volume supplier with recent regulatory wins: additional approvals for new particle size ranges broaden its addressable portfolio. Strategic implication: regulatory certification can rapidly translate into market share gains, particularly for contract manufacturers and generic producers seeking validated sources.
-
European specialty producers (IPS Surinerts, Pharmatrans Sanaq, Emilio Castelli) — These firms emphasize neutral pellet quality, dossier support and, in some cases, Drug Master File (DMF) availability. They are attractive partners for innovators seeking documented regulatory pathways.
-
Chinese suppliers (Zhuhai Rundu, Nanjing Joyfulchem) — Emerging as reliable, cost‑competitive sources with investments in process innovation and capacity. Their presence matters for procurement strategies and long‑term cost management.
Collectively, these firms illustrate two strategic realities for 2026: scale and regulatory affirmation drive access to premium formulations, while regional and cost‑oriented suppliers expand options for price‑sensitive programs. The competitive mix continues to favor firms that combine documented quality, regulatory readiness and reliable logistics.
Strategic Imperatives for 2026
For executives preparing 2026 budgets and capital plans, the following imperatives emerge from our analysis. Each recommendation is calibrated to the market’s 6.2% CAGR environment—growth exists, but with margin and supply pressure that require proactive measures.
-
Hedge raw material exposure. Build multi‑tiered sugar sourcing strategies (spot contracts, seasonal hedging, vertical supplier relationships) to mitigate crop yield volatility and input‑cost spikes. Consider long‑term purchase agreements with indexation clauses to balance price stability and flexibility.
-
Prioritize supplier qualification and dual‑sourcing. Given the market’s concentration and the criticality of GMP compliance, qualifying at least two suppliers per critical particle size range reduces production disruption risk.
-
Invest selectively in capacity and automation. Rampings should be guided by product mix and secured offtake. Capacity expansions (internal or partner‑based) should align with validated demand from CDMOs and large formulators to avoid underutilization.
-
Leverage regulatory capital. Secure or acquire DMFs and dossier components where possible—regulatory readiness is a fast path to capture share for new particle sizes or formulation niches.
-
Embed sustainability and traceability. Buyers increasingly demand supply‑chain transparency. Programs that demonstrate responsible sugar sourcing and lower carbon intensity gain differentiation, particularly with life‑cycle assessments becoming standard in procurement.
-
Pursue selective partnerships and bolt‑on M&A. Given high R&D and validation costs for bespoke size ranges, partnerships with regional specialists or targeted acquisitions can accelerate access to capability while minimizing greenfield investment.
-
Optimize commercial contracts. Negotiate service level agreements that include capacity reservation, quality penalties and price‑adjustment mechanisms tied to input indices to align supplier incentives.
Risk Scenarios and Contingency Playbook
Decision makers should stress‑test plans against three practical scenarios:
-
Supply shock (agricultural shortfall). Trigger actions: invoke contingency suppliers, accelerate validated imports, and deploy prioritized allocation across product lines.
-
Regulatory tightening. Trigger actions: fast‑track GMP audits, secure DMFs, and pre‑position analytical method transfers and batch records.
-
Price erosion from new entrants. Trigger actions: differentiate through service, technical support and integrated supply agreements rather than competing purely on price.
What the Full PW Consulting Report Delivers
Our full Sugar Sphere Market study goes beyond diagnosis to provide an actionable playbook for 2026 execution, including:
-
Scenario‑based revenue forecasts and sensitivity models calibrated to variable input cost and demand shocks.
-
Supplier scorecards and a due‑diligence framework for rapid qualification and dual‑sourcing, mapped to regulatory and logistical risk.
-
Contract templates and negotiation playbooks that translate market concentration and capacity lead times into commercially enforceable SLAs.
-
Operational checklists for quality control, particle size verification and dossier readiness aligned to USP and Ph. Eur. expectations.
-
Investment prioritization matrices that guide capex decisions under mid‑single digit growth scenarios, minimizing stranded asset risk.
-
A mapped competitive intelligence annex profiling leading suppliers, their strategic moves and implications for procurement and partnership strategies.
How to Use This Preview in Board and Budget Conversations
This preview equips leaders to frame three board-level decisions for 2026:
-
Do we secure supply and regulatory headroom now, or accept higher spot exposure? Use our supplier scorecard to quantify the tradeoffs.
-
Where should incremental capital be deployed—automation, capacity expansion, or M&A? Our prioritization matrix connects each option to return horizons consistent with a 6.2% CAGR environment.
-
Which commercial levers (contract terms, indexation, volume commitments) should be standardized to protect margins? Our contract playbook provides executable templates.
Closing — Why Access the Full Study
This preview highlights the strategic contours of the sugar sphere market but intentionally omits granular regional and application splits that are central to transaction‑level decisions—those are contained within the full report. If your 2026 plan involves capacity investments, supplier consolidation, regulatory filings or targeted M&A, the complete study contains the actionable data, supplier dossiers and financial models needed to execute with confidence.
PW Consulting’s Sugar Sphere Market research pairs rigorous market modeling with operational playbooks, enabling pharmaceutical manufacturers, CDMOs and ingredient suppliers to translate a 6.2% CAGR environment into defensible, risk‑adjusted growth plans. For access to the comprehensive data, segmented analyses and downloadable tools, please consult the source report page.
For detailed analysis of this topic, please visit the official page: Sugar Sphere Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


