



PW Consulting: Screw Press Market Poised for 7.5% CAGR Through 2032

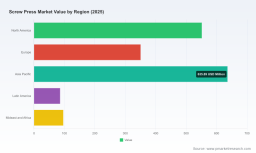
Screw Press Market — 2026 Strategic Preview
As municipal and industrial operators compress capital cycles and regulators tighten discharge limits, the screw press market is moving from niche equipment to a core component of wastewater and solids-management strategies. PW Consulting’s forthcoming Screw Press Market research — anchored on a 2025 base year and a detailed 2026–2032 forecast horizon — synthesizes quantitative market sizing with actionable, transaction-ready guidance for executives who must make investment, procurement, and M&A decisions in 2026. The high-level market trajectory is clear: the sector expanded steadily from 2020 and was valued at USD 1,720 Million in 2025; it is forecast to reach approximately USD 2,850 Million by 2032, representing a 7.5% compound annual growth rate across the 2026–2032 period.
Screw Press Market
Why this matters for 2026 decision cycles
-
Regulatory momentum is accelerating adoption windows. Recent analyses show significant retrofitting activity across advanced economies as wastewater discharge standards and circular-economy mandates push operators to improve sludge dewatering and solids recovery.
Screw Press Market -
Energy and lifecycle economics are becoming the determiners of competitive procurement. Equipment that demonstrably reduces energy intensity per ton of dewatered solids now achieves shortened payback thresholds and unlocks access to finance and public subsidy.
Screw Press Market -
Supply-chain and materials choices (stainless-steel wetted parts, carbon-steel structural components) are impacting both capital costs and maintenance profiles — decisions that materially affect total cost of ownership across a 10–15 year horizon.
Market dynamics and the evolving value chain
The market’s growth is being shaped by three intersecting dynamics. First, regulation-driven retrofit cycles in municipal systems — supported by empirical installation trends in major jurisdictions — are creating a sizable addressable market for reliable dewatering solutions. Second, technology differentiation is narrowing to energy efficiency, solids-capture performance, and ease of integration with downstream biosolids management processes. Third, capital constraints among small and medium enterprises create a bifurcated demand profile: high-end buyers prioritize performance and lifecycle costs, while a larger cohort remains sensitive to upfront capital and installation complexity.
These forces produce a predictable set of commercial outcomes: vendors that combine demonstrable field performance (high solids capture, consistent throughput), modularity for retrofit installations, and low operating energy per ton will command pricing premiums and stronger aftermarket service economics. At the same time, financing structures, product-as-a-service models, and factory-built skid systems are expanding the number of buyers who can access premium technology without large initial capital outlays.
Regulation, standards and materials — hard constraints
-
Regulatory drivers are concrete. Multiple studies show that a significant share of newly installed sludge-handling equipment in regulated markets has been screw-press based, driven by tightened effluent and biosolids management standards.
-
Energy-efficiency credentials are now a procurement requirement in many public tenders. Some leading product lines demonstrate drive systems and mechanical designs that exceed current electric motor efficiency norms, translating into immediate OPEX benefits.
-
Materials choice matters: industry practice consolidates on stainless steel for wetted components and carbon steel for supporting structures — a design split that balances corrosion resistance with structural economics.
-
Adoption barriers persist. Studies indicate that a meaningful portion of smaller operators cite high initial capital and installation costs as the principal obstacle to adopting screw press systems, which keeps a portion of the market fragmented and price-sensitive.
What the PW Consulting report delivers (practical, decision-ready content)
-
Comprehensive market sizing and a 2026–2032 forecast at multiple granularities (by region, product type, and end-application), with transparent methodology and sensitivity scenarios designed for board-level risk assessment.
-
Competitive benchmarking and vendor scorecards — technology, service footprint, supply-chain resilience, and aftermarket revenue streams — to streamline vendor shortlists for RFPs and M&A screening.
-
Procurement and specification playbooks: recommended technical specifications (materials, motor efficiency thresholds, solids-performance metrics), installation checklists, and commissioning acceptance tests tailored to retrofits and greenfield projects.
-
Unit-economics and ROI models: CAPEX/OPEX comparisons across typical retrofit and greenfield scenarios, payback sensitivity to energy prices, disposal cost savings, and service-contract design to preserve margins.
-
Go-to-market and partnership strategies for vendors and investors: market-entry tactics, channel models, and JV structures that accelerate adoption among utilities and industrial buyers.
-
Primary-sourced insights and field validation: interviews with plant operators, OEM service teams, and procurement leads, plus case studies illustrating measured performance improvements and lifecycle cost outcomes.
Competitive landscape — who matters and why
The supply base is marked by a blend of global incumbents and regional specialists. The market structure is moderately concentrated: the top three vendors together account for over one-third of market sales, while the top five capture a majority share — a profile that favors established players with proven field track records and scale in aftermarket services.
-
FKC Co., LTD. — A recognized global leader with thousands of installations worldwide, FKC is often the benchmark for municipal dewatering and thickening applications. Their strength lies in field-proven reliability and custom-configured systems for large utilities.
-
Vincent Corporation — Focused on design and manufacturing for organic-material dewatering, Vincent’s value proposition centers on engineering depth and materials know-how to optimize throughput for specific feedstocks.
-
BDP Industries — A U.S.-based manufacturer of fully enclosed screw presses, notable for minimizing water use and maintenance requirements. Their model appeals to buyers prioritizing low lifecycle energy and simplified onsite servicing.
-
HUBER Technology — European supplier of high-efficiency screw-press systems; emphasizes drive- and throughput-efficiency that can materially reduce electrical consumption and increase solids capture in municipal applications.
-
ANDRITZ AG — Global supplier with integrated systems for liquids/solids separation; well positioned for large projects requiring full-system integration, from feed handling to biosolids conditioning.
For buyers and investors, these vendor profiles are not static: competitive advantage will be determined by who can demonstrate lower total cost of ownership, faster commissioning, and validated performance under real operating conditions.
Strategic implications and recommended actions for 2026
-
Prioritize retrofit pipelines where regulatory deadlines or disposal-cost pressures create near-term payback windows. Use the report’s ROI templates to triage projects by net-present-value and implementation risk.
-
Insist on measurable performance guarantees in procurement (energy-per-ton and average solids content of cake) and structure contracts to include service-level units that align vendor incentives with lifecycle performance.
-
For OEMs and investors: focus R&D and commercial efforts on energy-efficient drive systems, modular retrofit skids, and digital monitoring that enables predictive maintenance — features that buyers are increasingly willing to pay for.
-
Consider financing solutions or product-as-a-service models to unlock budget-constrained SME buyers; such structures also create recurring revenue streams and higher lifetime customer value.
-
Use acquisition screens that prioritize installed-base serviceable regions, control of aftermarket parts, and IP around high-efficiency drives or solids-handling patents.
-
Monitor raw-material and supply-chain exposures (stainless steel availability and pricing) as scenario levers that can materially affect lead times and margins.
Key metrics to track in 2026
-
Installed base growth by retrofit vs greenfield projects
-
Average solids capture and cake dryness achieved in operational trials
-
Energy consumption per tonne of dewatered solids
-
Aftermarket revenue as a percentage of total sales
-
Time-to-commission and first-year uptime in retrofit deployments
Next steps — how to use the full report
PW Consulting’s full Screw Press Market study is built to be directly actionable in 2026 planning cycles. If you are building capital budgets, evaluating vendors, preparing an M&A target screen, or designing a product roadmap, the full report provides the data, models, and vendor intelligence necessary to convert insights into decisions. The research deliberately preserves granular segmentation tables, vendor scorecards, and confidential interview transcripts in the detailed deliverable; this summary highlights the strategic takeaways while inviting procurement teams and senior leaders to review the complete dataset for transaction execution.
Contact PW Consulting to access the full report and the downloadable decision-support toolkit — including ROI calculators, procurement templates, and a vendor shortlisting workbook — that will enable you to move confidently from strategy to execution in 2026.
For detailed analysis of this topic, please visit the official page: Screw Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


