



PW Consulting: Metal 3D Printing Market to Reach USD 6,419.6M by 2032 at 20% CAGR

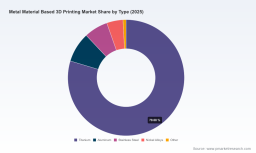
Metal Material Based 3D Printing Market — Strategic Outlook for 2026 Decision‑Makers
As organizations plan capital allocation, supply‑chain adaptation and technology roadmaps for 2026, metal material based additive manufacturing (AM) presents both an exceptional growth opportunity and a complex risk landscape. Our latest PW Consulting research—anchored on a 2025 base year, a historical view covering 2020–2025 and forward forecasts through 2032—shows the market expanding at a sustained compound annual growth rate (CAGR) of roughly 20%. The market moved from the sub‑billion dollar phase in the early 2020s to a multi‑billion dollar industrial footing by mid‑decade, with 2025 serving as the pivotal year when demand, material qualification efforts and production‑grade system deployments converged to reframe strategic priorities for aerospace, defense, medical and industrial OEMs.
Metal Material Based 3D Printing Market
Why this research matters for 2026 decisions
-
High growth, high disruption: With a near‑term CAGR well into double digits, metal AM is no longer a niche prototyping tool. Boardrooms must treat metal 3D printing as a core production technology that affects product architectures, supply‑chain resilience and aftermarket service models.
Metal Material Based 3D Printing Market -
Material and process qualification is the gating factor: As metal AM moves from parts‑per‑thousand to parts‑per‑thousand‑per‑week, the commercial winners will be those who solve validated materials, qualification and certification at scale—especially for flight‑critical and medical implants.
Metal Material Based 3D Printing Market -
Timing matters: Investments made in 2026 will determine whether organizations lead in design‑for‑additive (DfAM) and qualified supply or incur the higher switching and certification costs of delayed entry.
Top‑line market dynamics: drivers, constraints and inflection points
-
Demand accelerators: Aerospace & defense and medical applications continue to be the primary technology accelerants because of their high value per part and rigorous performance requirements. Broader industrial adoption—automotive, tooling and energy—remains a powerful second wave as manufacturers pursue lightweighting, part consolidation and supply‑chain shortening.
-
Materials as strategic assets: Titanium powders dominate strategic conversations due to unmatched performance in aerospace and medical segments. At the same time, metal powder producers are expanding capacity and vertically integrating to capture value across feedstock, qualification and alloy formulation.
-
Regulatory and certification milestones: New ISO standards and Nadcap‑aligned process validation regimes are becoming table stakes for production deployments. These regulatory developments create both friction (longer time‑to‑qualification) and opportunity (premium for qualified suppliers and certified material portfolios).
-
Defense procurement as an accelerant: Military adoption is outpacing many commercial sectors in some geographies, supported by targeted procurement and in‑field manufacturing pilots. This creates urgent certification and cybersecurity requirements for supply partners.
-
Supply chain reshaping: Expect continued consolidation and vertical integration among powder producers, system OEMs and service bureaus. Organizations that secure tier‑one supplier relationships and dual‑source critical alloys will enjoy tactical advantages in 2026.
Competitive landscape — what leading players are doing
The metal AM value chain is evolving into a bimodal ecosystem: a set of equipment OEMs competing on build performance, throughput and software, and a group of materials specialists optimizing powder chemistry, consistency and qualification. Our analysis focuses on both sides of this equation.
-
EOS GmbH continues to set a technology benchmark for laser powder bed fusion (LPBF) systems and is deepening its materials portfolio. Recent launches of new metal powders and regional production investments signal a push to shorten lead times and accelerate certification cycles. For strategic buyers, EOS is a likely partner for integrated system + material solutions where supply predictability is paramount.
-
Nikon SLM Solutions is making moves in production‑scale LPBF systems and software. Large system orders from prime defense contractors, combined with next‑generation data preparation tools, indicate Nikon’s intent to capture high‑volume industrial workflows where software‑driven process control is a differentiator.
-
Renishaw remains focused on aerospace and medical specialties, coupling hardware with tailored material/parameter sets to accelerate qualification for regulated sectors.
-
3D Systems and other established incumbents are positioning for end‑to‑end solutions—printer hardware, powder supply and services—targeting customers seeking turnkey production conversions.
-
Colibrium Additive (GE Additive) and electron beam melting (EBM) players are emphasizing alloys for high‑performance applications, which influences procurement strategies in aerospace and energy sectors where EBM‑capable alloys excel.
-
Powder specialists such as Höganäs, Carpenter Technology, Sandvik and ATI are expanding capacity and formalizing AM‑grade product lines. Their moves toward traceability, tighter particle‑size control and alloy tuning are creating a new competitive frontier: materials as differentiated, certified intellectual property.
Implications of recent developments
-
New materials launches and facility investments by system OEMs are shortening the timeline from machine purchase to qualified production. Companies that pre‑position with these OEMs will reduce qualification overhead and accelerate time‑to‑market.
-
Large system orders for defense primes and software releases focused on data preparation show OEMs competing on the whole process chain, not just individual machines. This compresses the value chain and raises the strategic importance of software and process control capabilities in procurement criteria.
-
Powder suppliers’ vertical moves change supplier selection dynamics: buyers must evaluate not only powder quality, but also capacity, geographic footprint and certification capabilities. Dual‑sourcing strategies should be modeled into procurement plans to mitigate single‑supplier risk.
What PW Consulting’s report delivers (practical, executable outputs)
PW Consulting’s Metal Material Based 3D Printing Market report is designed as an executable toolkit for executives deciding in 2026. Highlights include:
-
Market sizing and forecast model (2020–2032) with scenario levers: Our base model is presented in USD (Million) with sensitivity cases that let you stress test outcomes by adoption rates, material qualification timelines and defense procurement pivots.
-
Modular go‑to‑market playbooks: Tailored strategies for OEMs, tier‑1 suppliers, powder producers and service bureaus that cover channel design, price architectures, qualification roadmaps and industrial partnerships.
-
Vendor benchmarking and supplier matrix: Comparative analysis across equipment OEMs, software providers and material specialists—covering technology readiness, certification capabilities, service footprint and partnership flexibility.
-
Regulatory and certification checklist: Practical steps for ISO/Nadcap compliance and design controls specific to metal AM, including timelines and resource estimates for qualifying materials and processes.
-
M&A and partnership targets: An actionable shortlist of strategic targets and partnership archetypes derived from capability gaps we observed across the value chain.
-
Risk heatmap and mitigation playbook: Identifies the highest impact risks (material supply bottlenecks, certification delays, cybersecurity and export controls) and offers prioritized mitigation actions.
-
Case studies and operational templates: Real‑world examples of part redesign, production line integration and cost‑to‑serve modeling from early enterprise adopters. Templates include qualification project plans and supplier scorecards.
How to use the insights to shape a 2026 strategy
-
Start with material‑first use cases: Prioritize parts and product lines where materials (e.g., titanium or nickel alloys) deliver the highest functional and economic value. Success here creates the organizational credibility to scale AM across the enterprise.
-
Build qualification as a cross‑functional program: Treat material and process qualification as a multi‑year program with milestones, not a procurement checkbox. Bring together engineering, quality, procurement and regulatory teams from day one.
-
Negotiate flexible supply agreements: Secure usable capacity from powder producers with clauses for traceability, accelerated delivery and collaborative R&D to co‑develop alloy modifications for your products.
-
Assess full system stacks, not component specs: Compare vendors based on software, service, materials ecosystem and regional support—these factors materially affect time‑to‑qualified‑production.
-
Use pilots to de‑risk scale: Run targeted pilot lines to validate economics, part performance and qualification pathways before committing to broad rollouts.
Market structure and concentration
The market exhibits moderate concentration: a handful of technology and materials leaders collectively command a significant portion of revenue and influence standards development. That dynamic rewards early partnerships with top‑tier providers but also creates an opening for specialized entrants that can address certification or niche alloy needs.
What we are intentionally holding back (the “trailer” approach)
To preserve the value of the full study—as well as to encourage direct engagement with our modeling tools—we have deliberately withheld granular regional and application revenue splits from this executive summary. The full report contains detailed segmentation data, including regional and application breakdowns, per‑alloy revenue trajectories, supplier share tables and downloadable forecast models that enable bespoke scenario planning. If your 2026 plans depend on these micro‑level allocations (e.g., supplier selection in a given region or alloy‑specific procurement), accessing the full dataset is essential.
Next steps
For 2026, executives should prioritize three actions: (1) run a material‑value assessment to identify the first wave of metal AM conversions, (2) initiate supplier qualification and dual‑sourcing strategies for critical powders, and (3) secure partnerships with system vendors that demonstrate certified process stacks and responsive software roadmaps. PW Consulting’s full Metal Material Based 3D Printing Market report provides the models, vendor insights and operational templates to execute these steps with confidence.
Contact PW Consulting to access the full report, supporting forecast model and a customized briefing tailored to your firm’s strategic questions for 2026.
For detailed analysis of this topic, please visit the official page: Metal Material Based 3D Printing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


