



PW Consulting: Steel Powder Market Poised for 6.4% CAGR

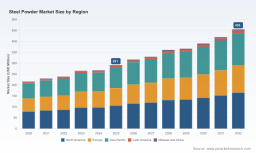
Steel Powder Market — Strategic Outlook for 2026: A PW Consulting Perspective
As companies prepare strategy and capital-allocation decisions in 2026, the steel powder market is entering a phase where steady structural growth intersects with intensifying regulatory and supply‑chain volatility. PW Consulting’s new market study — anchored on a 2025 base year and projecting through 2032 — synthesizes historical performance (2020–2025), a quantitatively grounded forecast (2026–2032) and pragmatic playbooks for commercial, operational and technology leaders. This introduction highlights the report’s strategic value for executives in 2026 while deliberately leaving granular sub‑segment figures available only in the full report to preserve commercial advantage for subscribers.
Steel Powder Market
Market snapshot — direction and scale
The steel powder market has shown resilient expansion through the first half of the decade. Using 2025 as the base year, PW Consulting’s topline model identifies a multi‑year compound annual growth rate (CAGR) of 6.4% over the 2026–2032 forecast window. The model combines historical shipment and revenue trends, capital expenditure signals from leading producers, and demand pull from core applications such as automotive, aerospace, industrial machinery and medical manufacturing.
Steel Powder Market
- Trajectory: After stabilizing through 2024–2025, demand is forecast to accelerate modestly as additive manufacturing (AM) adoption deepens in high‑value sectors and as conventional powder metallurgy applications recover from cyclical weakness.
- Market size perspective: The market’s revenue base in 2025 provides the anchoring point for scenario analyses. PW Consulting’s scenarios show that, at the central 6.4% CAGR, the market expands meaningfully by the early 2030s — creating a multi‑billion‑dollar opportunity for incumbent and new entrants alike.
- Concentration: Market share is neither fragmented nor monopolized. The top three and top five producers capture a material portion of the market, indicating oligopolistic dynamics that favor scale, technology leadership and specialty grades.
Drivers, headwinds and inflection points (what will matter in 2026)
- Technology adoption: Broader acceptance of metal additive manufacturing in aerospace, defence and medical applications is the most visible demand lever. New powder grades and lower defect envelopes are unlocking use cases that command premium pricing and tighter specifications.
- Feedstock and circularity: Steel powder production increasingly relies on recycled scrap as a primary feedstock. Producers that secure high‑quality scrap streams and invest in upstream sorting and refining capabilities will preserve margin and resilience.
- Regulatory regime shifts: 2026 introduces new policy inflection points. China’s export licensing for certain steel products (effective January 1, 2026) and the EU’s CBAM implementation increase complexity for cross‑border flows and cost structures. Tariff dynamics and trade remedies continue to create uneven regional pricing and sourcing incentives.
- Regional demand cycles: Regional manufacturing slowdowns or accelerations will create uneven pockets of opportunity. For example, North American iron and steel powder shipments declined in 2024 amid softness in certain powder metallurgy and AM segments — an important short‑term headwind for suppliers focused on that market.
- Supply flexibility: Capacity expansions, especially in high‑purity gas atomization and specialty alloy powders, will re‑shape competitive advantage. Producers that combine flexible batch production with stringent process controls will win aerospace and medical specifications.
Competitive landscape — who to watch and why
The competitive map is a mix of global diversified metals groups and specialist powder manufacturers. Leading firms are deploying different strategic mixes — capacity scale, proprietary powder chemistries, recycled‑feedstock integration, and channel partnerships — to capture incremental value.
Steel Powder Market
- Höganäs (Sweden): A global leader in iron, steel and stainless steel powders, Höganäs’s investments in gas atomization capacity and high‑purity grades position it to lead in aerospace and medical AM markets. Their recent capacity expansion initiatives underscore a strategy to capture premium segments with stringent certification requirements.
- Outokumpu (Finland): By leveraging recycled scrap from its flat products business, Outokumpu offers a differentiated, sustainability‑oriented proposition for stainless steel powders. Their movement into aerospace‑grade stainless powders signals a targeted push up the value chain.
- Carpenter Technology Corporation (US): Carpenter’s focus on premium alloys, tool steels and application engineering (MIM, HIP, additive workflows) provides an integrated solution set attractive to high‑value customers seeking single‑source reliability and engineering support.
- Sandvik (Sweden): With the Osprey series and new product introductions, Sandvik is competing on materials R&D and brand credibility for AM. Their product portfolio aims to bridge traditional tool steels and advanced maraging categories.
- Kobe Steel, Rio Tinto and major regional players: These firms bring scale in feedstock sourcing and process capabilities. Rio Tinto’s development of AM‑targeted powders at its RTFT facility illustrates the strategic convergence of mining and advanced manufacturing capabilities.
- Regional specialists (China, Italy, US): A number of national champions and specialists focus on localized supply, niche chemistries and cost leadership. Their role is particularly material where trade barriers or regional certification requirements favor local production.
Recent product and capacity moves in 2025–2026 reveal strategic priorities: capacity boosts at high‑purity atomization lines, targeted introductions of grades to bridge adjacent alloy families, and targeted entries into aerospace and aviation markets. These are not incremental product tweaks — they reflect purposeful moves to own the premium ladder of AM and critical PM applications.
Regulatory and supply-chain shocks — planning contingencies for 2026
- Export controls and licensing: China’s 2026 export licensing for certain steel products introduces a new layer of permit risk and potential lead‑time lengthening. Companies reliant on cross‑border sourcing must pre‑emptively verify alternative suppliers and stock strategies.
- Carbon pricing and CBAM: The EU’s Carbon Border Adjustment Mechanism in 2026 raises the effective landed cost of steel powders and feedstocks into Europe. Strategic hedging, nearshoring of production, and low‑carbon certification will become commercial differentiators.
- Tariff unpredictability: Existing measures, such as US trade remedies on certain metals, create price dispersion and sourcing arbitrage opportunities — but also risk for supply reliability. Firms should model tariff scenarios into 2026 procurement strategies.
- Raw material quality: The use of recycled scrap as feedstock is a double‑edged sword — it supports circularity but requires investment in metallurgy and process controls to meet tighter AM specifications.
What PW Consulting’s full report delivers (practical, actionable contents)
PW Consulting’s full Steel Powder Market study is designed as an operational toolset for 2026 decision‑makers. The report combines strategic narrative with hands‑on modules and proprietary data models, including:
- Topline market sizing and multi‑scenario forecasts (2026–2032) calibrated to macroeconomic, industry cycle and technology adoption variables.
- A validated demand model by application and region that supports what‑if scenario runs for commercial planning (note: detailed sub‑segment tables and proprietary elasticities are available in the subscriber report).
- Competitive intelligence dossiers for the industry’s leading firms: capacity maps, product portfolios, recent investments and likely playbooks over the next 18–36 months.
- Supply‑chain risk matrices that quantify the impact of export licensing, carbon border pricing and tariff scenarios on landed costs and delivery lead times.
- Go‑to‑market and procurement playbooks: supplier selection criteria, cost‑to‑serve calculators, and strategies for partnering with AM system integrators and OEMs.
- Technology radar and CAPEX implications: analysis of gas atomization versus alternative powder routes, capital intensity profiles, and break‑even analyses for specialist lines.
How executives should use the study in 2026 — recommended actions
- Align sourcing strategies to policy scenarios: By Q2 2026, procurement teams should have dual‑source plans and evaluated nearshore alternatives for any supply currently exposed to export licensing or CBAM cost shocks.
- Prioritize product certification pathways: For sellers targeting aerospace, medical and defence markets, invest in process controls and qualification programs now — these are multi‑quarter timelines that affect 2027–2028 revenues.
- Calibrate capacity investments: Use PW Consulting’s scenario outputs to stress test greenfield or brownfield expansions. Focus capacity on flexible, small‑batch high‑purity capabilities rather than commodity commodityization where margins compress.
- Monetize sustainability: Certify low‑carbon powders and embed traceability across the feedstock chain. Buyers in regulated jurisdictions will pay a premium for verified low‑embodied‑carbon materials over time.
- Explore strategic partnerships: OEMs adopting AM want integrated material + process suppliers. Consider partnerships with AM machine OEMs, HIP/forging specialists, or captive supply arrangements with steelmakers to secure feedstock and downstream pull‑through.
The PW Consulting advantage — why this study is decision‑grade for 2026
Unlike headline market commentaries, this study is built for executives who must translate market insight into boardroom decisions in 2026. It ties a transparent forecast (2026–2032) to tactical playbooks — from procurement hedges to product qualification roadmaps — and blends public‑domain signals with proprietary primary interviews and a validated shipment/revenue model. The report intentionally conceals detailed sub‑segment tables in this public summary to protect competitive sensitivity and to incentivize deep dives via the full deliverable.
Final note — next steps
For teams planning capital allocation, supplier strategy, M&A screening or product certification roadmaps in 2026, PW Consulting’s Steel Powder Market study provides the necessary quantitative scaffolding and qualitative context. Access to the full report unlocks the detailed regional, type and application breakdowns, elasticity assumptions, and company‑level financial sensitivities that underpin the forecast and recommended actions. Contact PW Consulting to obtain the complete dataset and bespoke scenario runs tailored to your company’s footprint and risk appetite.
For detailed analysis of this topic, please visit the official page: Steel Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


