



PW Consulting: 2-Hydroxyethyl Methacrylate Market set to grow at a 4.2% CAGR (2026–2032)

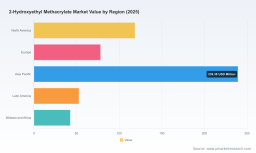
2‑Hydroxyethyl Methacrylate (HEMA) Market: Strategic Preview for 2026 Decision‑Making
As PW Consulting’s lead industry analyst, I present a high‑altitude, decision‑focused preview of our latest HEMA market research. This piece is designed as a strategic “trailer”: it demonstrates the analytical depth and operational relevance of the full study, highlights the levers that will matter to executives in 2026, and surfaces the high‑impact risks and opportunities — while intentionally withholding proprietary subsegment tables and point‑level data to direct stakeholders to the full report for executional intelligence.
2-Hydroxyethyl Methacrylate Market
Market snapshot and trajectory
Using 2025 as the base year, our model reconciles historical flows (2020–2025) and scenarios across 2026–2032. The global HEMA market has expanded steadily from a 2020 baseline and reached an estimated USD 531.0 Million in 2025. At a compound annual growth rate (CAGR) of 4.2% across the forecast horizon, the market is projected to approach approximately USD 705 Million by 2032 under our central case. Concentration is meaningful: the three leading firms account for a majority share of shipped volumes, and the top five firms capture roughly two‑thirds of the market — an oligopolistic structure that shapes pricing dynamics, innovation diffusion, and customer access.
2-Hydroxyethyl Methacrylate Market
Why this matters for 2026 strategy
For executives planning capital allocation, sourcing strategies, or product development launches in 2026, HEMA sits at the intersection of several structural trends that will determine commercial outcomes:
2-Hydroxyethyl Methacrylate Market
- Demand duality: HEMA’s end markets include performance coatings, reactive resin systems, adhesives, and regulated biomedical applications. Some end uses are volume‑driven and price‑sensitive; others require premium, ultra‑high‑purity product and long qualification cycles.
- Upstream cost exposure: Ethylene glycol — the principal upstream feedstock — continues to link HEMA economics to energy markets. Volatility in crude oil and natural gas propagates through to feedstock costs, creating episodic margin compression unless firms hedge strategically or secure captive supply.
- Regulatory asymmetry: Different regulatory treatments across jurisdictions (for example, professional‑use restrictions in certain cosmetic segments in the EU vs. permissive medical uses in the US) create arbitrage and product positioning opportunities, but also segmentation risk for suppliers that lack agile regulatory capabilities.
- Concentration and supplier power: With significant share held by a small set of producers and traders, buyers face a tradeoff between diversified sourcing and the cost/qualification burden of additional suppliers.
Actionable intelligence embedded in the report
The full PW Consulting study is structured for direct application by commercial, R&D, and procurement teams. Highlights include:
- Robust market-sizing and forecasting model (2020–2032) with scenario toggles for feedstock shocks, regulatory tightening, and accelerated biomedical demand.
- Supply‑chain heat maps showing geographic concentrations of capacity, transit risk corridors, and a supplier resilience scoring framework.
- Commercial playbooks for buyers and sellers: cost pass‑through templates, qualification timelines for high‑purity grades, and negotiation scripts tied to CRx dynamics.
- Regulatory and compliance matrix: jurisdictional requirements, ISO standards for biomedical grades, and recommended internal audit checklists for effluent treatment and reporting.
- Investment and M&A decision tools: IRR sensitivity tables, payback profiles for capacity expansion, and integration checklists focused on quality systems and environmental controls.
Note: To preserve the “trailer” function of this piece, we do not reproduce the granular regional/application‑split tables or the detailed price curves here. The full report contains downloadable models and exhibit pages for transaction diligence and commercial planning.
Competitive landscape — practical takeaways
Our competitive primer covers global majors and active regional players. Several dynamics are particularly relevant for 2026 strategy:
- Regional manufacturers and traders remain very active in Asia, serving domestic polymer industries and export channels. These firms often compete on lead times and tailored packaging/grades rather than on broad innovation platforms.
- Technology and product differentiation are concentrated in two areas: ultra‑high‑purity grades for medical and optical/resin applications, and functionalized HEMA derivatives that deliver adhesion, flame retardancy, or crosslinking advantages.
- Recent launches by specialty chemical producers and multinational integrators signal that downstream OEMs — from medical devices to advanced coatings — will increasingly demand validated supply and traceability as a condition of procurement.
Representative company profiles covered in the report (selection):
- Shakti Chemicals (Mumbai): Active trader and supplier focusing on polymer chemistry applications across Asia, with strength in trade channels and regional customer service.
- Qingdao RENAS Polymer Material (Qingdao): Manufacturer-oriented operations supplying standard and specialty HEMA grades to local polymer and coatings markets.
- Nantong Chem‑land (Nantong): Supplier of high‑purity grades geared toward industrial and specialty applications, emphasizing quality controls.
- Yancheng Green Chemicals (Yancheng): Manufacturer servicing polymer synthesis and advanced chemical applications with emphasis on production efficiency.
Among recent industry developments, the market has seen the launch of ultra‑pure HEMA grades aimed at medical, optical, and high‑clarity resin applications, collaborations between majors and OEMs to co‑develop HEMA‑based coatings for electric vehicle components, and novel phosphate‑derived methacrylate monomers targeting flame retardancy and corrosion resistance. These moves collectively raise the bar for qualification and narrow the time window for first‑mover advantage in adjacent niches.
Regulatory, environmental, and supply risks you cannot ignore
We distill three categories of non‑market risk that materially affect 2026 options:
- Regulatory constraints and product positioning. The EU enforces professional‑use restrictions in certain cosmetics categories, while US regulatory stance permits HEMA in defined medical applications. Firms that treat global markets uniformly will either over‑comply and lose share or under‑comply and face market exclusion or recall risk.
- Environmental compliance. HEMA hydrolyzes into methacrylic acid and ethylene glycol; modern production systems must control effluent and demonstrate treated discharge well below industry thresholds. Buyers and investors should require supplier effluent monitoring data and documented mitigation measures as pre‑qualification criteria.
- Feedstock volatility and supply chain bottlenecks. Ethylene glycol pricing volatility reverberates through HEMA cost structures. Our scenario work shows that without hedging or long‑term offtake agreements, manufacturers can see material margin swings that change the attractiveness of capacity expansions.
Strategic plays for 2026 — prioritized and pragmatic
Based on the central forecast and scenario analyses, PW Consulting recommends executives consider the following prioritized actions for 2026 planning:
- Lock in strategic feedstock arrangements. Pursue multi‑year ethylene glycol contracts or physical/logistical hedges to stabilize input costs. Where possible, evaluate co‑location with intermediate suppliers to reduce transit risk and capture time‑to‑market advantages.
- Segment the go‑to‑market by qualification horizon. Reserve internal R&D and production bandwidth for ultra‑high‑purity and functionalized HEMA where margins and entry barriers justify extended qualification; use contract manufacturing and trading partners to serve flexible, price‑sensitive demand.
- Embed regulatory intelligence into product roadmaps. Map product variants to jurisdictional regulatory routes and pre‑emptively build label‑compliance and professional‑use channel strategies for Europe, while leveraging permissive medical pathways in North America for higher‑value wins.
- Quantify supplier resilience in procurement. Use the report’s supplier resilience scorecard to qualify alternative sources, stress‑test supply continuity, and structure penalty/rebate clauses tied to on‑time delivery and quality.
- Pursue targeted partnerships over broad M&A in the near term. Given the market’s moderate concentration, partnerships for access to specialized grades or capacity can deliver faster ROI and lower integration risk than full acquisitions — unless the target provides clear vertical integration benefits (feedstock to finished monomer) or unique proprietary grades.
What the full report unlocks
The complete PW Consulting HEMA market study delivers the executable evidence base to operationalize the plays above. Subscribers receive:
- Downloadable financial models with adjustable scenarios for feedstock pricing, regulatory shocks, and accelerated demand curves;
- Detailed supplier dossiers, buyer scorecards, and suggested contractual language for supply assurance;
- Qualification timetables and cost‑to‑qualify estimates for ultra‑high‑purity grades and regulated medical applications;
- Playbooks and templates for procurement, R&D prioritization, and M&A diligence.
Final synthesis — the 2026 inflection
As 2026 approaches, HEMA is transitioning from a largely commodity‑adjacent chemical to a segmented specialty platform where purity, functionalization, and regulatory positioning drive value. The market’s steady CAGR and projected expansion to roughly USD 705 Million by 2032 create a conducive backdrop for focused investments. That said, commercial success will favor firms that (a) control feedstock exposure, (b) differentiate into validated high‑value grades, and (c) maintain rigorous regulatory and environmental compliance. Our study equips leaders with the models, checklists, and supplier intelligence to make those tradeoffs with confidence.
To access the full dataset, interactive models, and supplier scorecards that underpin these conclusions, consult the PW Consulting HEMA market report. The full report is intentionally comprehensive — and designed for immediate deployment into 2026 strategy cycles.
For detailed analysis of this topic, please visit the official page: 2-Hydroxyethyl Methacrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


