



PW Consulting: SOI Market Poised for USD 3.85 Billion by 2032 at 13.5% CAGR

SOI Market 2026 Strategic Preview: Operational Imperatives for Decision‑Makers
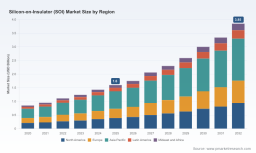
As PW Consulting’s lead industry analysts, we present a high‑level strategic briefing drawn from our full Silicon‑on‑Insulator (SOI) Market study (base year 2025, historical 2020–2025, forecast 2026–2032). The SOI ecosystem is transitioning from boutique specialty to scaled industrial supply—our bottom‑up model shows a return to robust expansion driven by mobile radio, automotive electrification, and low‑power compute architectures. The market expanded from roughly USD 0.85 billion in 2020 to USD 1.6 billion in 2025 and, under our base assumptions, grows at a compound annual growth rate of 13.5% over the forecast period, reaching an estimated USD 3.85 billion by 2032. This preview highlights the decisions that will matter most in 2026, and why the full report is a practical tool for capital, procurement, and product strategy teams preparing budgets and investment cases this year.
Silicon-on-Insulator (SOI) Market
Why this matters for 2026 decisions
2026 is a tipping point for SOI. Demand drivers—higher‑frequency RF front‑ends, increased integration of power and RF in automotive and industrial modules, and a renewed emphasis on energy‑efficient compute—are intersecting with supply‑side shifts: major capacity expansions, a move to larger wafer diameters, and active government incentives that reshuffle lead‑time and geographic risk.
Silicon-on-Insulator (SOI) Market
- Supply concentration is meaningful: the market exhibits a moderate degree of supplier market share concentration (CR3 approximately 58%; CR5 approximately 72%), which creates both an opportunity and a strategic vulnerability for buyers and new entrants alike.
- Policy and capital flows are changing supply economics. CHIPS Act funding and related national incentives have catalyzed domestic capacity projects—since 2020 more than 140 semiconductor projects across the United States have been announced, representing over USD 640 billion in investment—altering lead‑time and location decisions for SOI wafer sourcing.
- Trade frictions and tariff dynamics are increasing the premium on localized or diversified supply chains, encouraging companies to revisit sourcing, dual‑sourcing, and long‑term supply agreements in 2026 procurement cycles.
What the PW Consulting SOI Market Study delivers
Our full report is designed as an operational playbook for leaders. It combines transparent methodology with executable outputs that feed directly into capital planning, supply chain management, and product roadmaps. Key actionable elements include:
Silicon-on-Insulator (SOI) Market
- Comprehensive market sizing and validated demand curves (2020–2032) by technology class and end‑use (detailed splits available in the full study).
- Supply‑side capacity mapping, wafer diameter transition timelines, and a supplier capability matrix that rates vendors on yield, technology (e.g., Smart‑Cut, SIMOX, bonding), and 300 mm readiness.
- Price and margin sensitivity models tied to raw material and equipment costs, tariff scenarios, and SKU mix shifts.
- Scenario planning toolkits—bull, base, and downside cases—with trigger points and probability bands to stress capital investment and procurement plans.
- Competitive benchmarking and M&A screening criteria for acquisitions, JV formation, or captive capacity builds.
- Regulatory and policy intelligence, including CHIPS Act readouts and regional incentives that materially affect cost of ownership and time‑to‑market.
Note: this preview deliberately omits the full breakdowns by region, type, and application that form the core commercial intelligence of the report. Those detailed tables and supplier‑level forecasts are available in the subscription report and are designed to be integrated directly into financial models and procurement RFIs.
Competitive dynamics: how leading vendors are positioning
The SOI vendor map is evolving from a technology‑centric oligopoly toward a capacity‑enabled competitive set. Recent strategic moves highlight two parallel dynamics: (1) incumbents scaling to meet automotive and RF demand; (2) foundries and wafer suppliers deepening collaboration to secure design wins.
- Soitec (Bernin, France) remains a technology leader via its Smart‑Cut platform and has recently announced an expansion that meaningfully lifts 300 mm capacity for automotive and RF applications—an advance that shortens the path to volume for design houses and OEMs.
- GlobalWafers (Taiwan) is pushing 300 mm manufacturing and has increased 200 mm output, reflecting a capacity diversification strategy that supports both legacy and next‑generation production nodes.
- Shin‑Etsu Chemical and SUMCO are executing scale plays on 300 mm SOI wafers, focusing on high‑speed, low‑power applications where wafer quality and throughput drive supplier selection.
- Regional and niche players—Shanghai Simgui, Okmetic, Silicon Valley Microelectronics—are preserving important local supply and specialty process capabilities (e.g., MEMS, cavity SOI), which buyers often require to reduce program risk or meet regional content rules.
- Foundry moves—such as Tower Semiconductor’s expansion of wafer bonding for SiPho and RF‑SOI—indicate growing vertical coordination between substrate suppliers and wafer fabs, accelerating integration timelines for complex RF and photonics modules.
For procurement and corporate development teams, the implication is straightforward: supplier selection is now a function of techno‑commercial fit and regional policy alignment as much as price and lead time.
Strategic playbook for 2026 — actions that preserve optionality
Below are priority actions that should be on the 2026 agenda for semiconductor OEMs, Tier‑1 suppliers, foundries, and investors.
- Supply resilience: institute a layered sourcing strategy—primary 300 mm suppliers, secondary 200/300 mm partners, and specialty local suppliers for qualification runs. Lock in staggered lead times and consider capacity reservation contracts for multi‑year design programs.
- CapEx timing and flex: align new product ramps to supplier capacity roadmaps. Where vertical integration is viable, run fast payback models for captive wafer fabs or secured JV capacity; otherwise prioritize long‑term offtake agreements with volume tiers and escalation clauses.
- Technical differentiation: choose SOI variants and wafer processes that optimize system‑level power and RF performance (and that align with foundry process nodes). Early co‑development with wafer suppliers can reduce NRE and speed time‑to‑market.
- Policy arbitrage: actively engage with regional incentive programs and fabrication financing schemes—these can materially reduce time‑to‑volume and lower landed cost risk tied to tariffs and logistics.
- M&A and partnership scouting: target bolt‑on acquisitions for niche process capability (e.g., MEMS or cavity SOI) and evaluate minority stakes in capacity expansions to secure prioritized throughput.
- Commercial contracting: structure contracts with price pass‑throughs for raw material and equipment surcharges, while negotiating performance‑based commitments to mitigate supply risk.
Scenarios and triggers to monitor in 2026
PW Consulting models three practical scenarios—bull, base, and downside—centered on demand strength for RF and automotive, the pace of 300 mm capacity ramp, and geopolitical trade actions. Key triggers that should move your planning forks in 2026 include:
- Public announcements and commissioning dates from major wafer suppliers (the market impact of a 300 mm ramp is nonlinear).
- Allocation of CHIPS Act and equivalent national incentives—both the timing and the conditionality attached to grants/loans.
- Design‑win cadence at major OEMs for RF front‑ends and automotive IC platforms; accelerated design wins compress capex cycles for substrate suppliers.
- Tariff and export control shifts that change landed cost or equipment availability for specific geographies.
How to use the report in your 2026 planning cycle
Integrate the full PW Consulting SOI Market study into three core planning flows:
- CapEx and investment committees: use our demand curves and supplier ramp schedules to stress test IRRs, depreciation timing, and working capital needs.
- Procurement and supply management: map suppliers to program timelines, incorporate our risk scoring into SOWs, and append contingency triggers to purchase orders.
- Product and platform roadmaps: incorporate wafer technology constraints and co‑optimization recommendations to reduce qualification cycles and accelerate revenue realization.
If your 2026 planning calendar includes wafer sourcing decisions, capital allocation, or M&A options, this study is designed to be operationalized directly into financial models and procurement RFIs. The detailed regional, technology and application splits, as well as supplier scorecards and pricing scenarios, are intentionally reserved for the full report: think of this briefing as the strategic trailer—detailed line‑item intelligence and supplier forecasts are available in the subscription deliverable.
PW Consulting will continue to track capacity announcements, policy shifts, and foundry design wins through 2026. For teams preparing budgets or evaluating strategic options this year, the immediate priorities are clear: secure optionality, align technical choices with supplier roadmaps, and factor policy incentives explicitly into the cost of ownership. Our full report supplies the tables, model files, and vendor scorecards you need to execute on those priorities.
For detailed analysis of this topic, please visit the official page: Silicon-on-Insulator (SOI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


