



PW Consulting: Heart Defect Closure Devices Market to Reach $344.8M by 2032 at 6.98% CAGR

Heart Defect Closure Devices Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
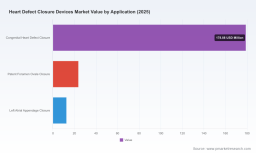
The Heart Defect Closure Devices market is entering a phase of sustained, investable growth. PW Consulting’s market model — built on a 2020–2025 historical base and projecting through 2026–2032 — points to a clear expansion trajectory: global market revenue grows from USD 215.0 Million in the 2025 base year to an estimated USD 344.8 Million by 2032, corresponding to a compound annual growth rate (CAGR) of 6.98% over the forecast period. This momentum is driven by a confluence of regulatory approvals, technology refinements in transcatheter occlusion systems, and evolving clinical guidelines that broaden eligible patient cohorts and encourage earlier intervention.
Heart Defect Closure Devices Market
Why this report matters for 2026 strategic choices
-
Timing-sensitive investment decisions. The 2026–2032 forecast window captures the immediate commercial effects of post-2023/2024 regulatory entrants and device lifecycle transitions. Companies evaluating capex for manufacturing scale-up, clinical investment, or regional launches must position to benefit from the next three critical expansion years when adoption curves steepen.
Heart Defect Closure Devices Market -
Clinical-evidence driven commercialization. Pivotal approvals and early commercial case series materially influence hospital adoption and payer coverage. The report quantifies adoption velocity scenarios and maps evidence gaps that, if addressed, can accelerate uptake and justify premium pricing.
Heart Defect Closure Devices Market -
M&A and partnership prioritization. Fragmentation metrics and concentration trends in our analysis highlight where inorganic moves or exclusive distribution partnerships can create defensible commercial footprints with limited incremental clinical risk.
What the in-depth analysis provides — a practical summary
This research package is designed for executives and strategy teams who need actionable intelligence rather than abstract trends. Key deliverables include:
-
A validated market model with historical (2020–2025) and forecast (2026–2032) revenue streams in USD Million, including base-case, upside, and downside scenarios tied to regulatory and clinical adoption inflection points.
-
Adoption-pathway simulations that translate clinical trial timelines, reimbursement changes, and hospital procurement behavior into patient-volume and revenue implications at national and regional levels.
-
A regulatory and reimbursement playbook that synthesizes recent approvals, PMA/clearance precedents, and payor policy signals — coupled with tactical recommendations for submissions, labeling strategies, and real-world evidence (RWE) generation.
-
Commercial benchmarking templates: price elasticity matrices, sales-force deployment plans, distributor channel economics, and SKU rationalization frameworks to optimize margins during scale-up.
-
Clinical and health-economics dossiers: comparative profiles of device classes, complication rates, length-of-stay impacts, and cost-offset models to support value-based contracting.
-
Decision-support annexes: unit-level P&L templates, scenario-based ROI calculators for capacity investments, and an interactive data workbook allowing executives to test custom assumptions without exposing sensitive segment tables in public summaries.
Competitive landscape — who to watch and why
The market remains moderately fragmented, with concentration ratios reflecting meaningful room for regional specialists and innovative entrants. Our market concentration analytics show CR3 at approximately 24.6% and CR5 at approximately 26.2%, underscoring a competitive field with no single dominant incumbent. This structure favors differentiated clinical or commercial propositions.
Key players profiled in the report include (representative, not exhaustive):
-
Abbott Laboratories — A long-time market participant with established Amplatzer™ septal occluders and an expanding delivery-system portfolio. Abbott’s continued device iterations and recent regulatory clearances for delivery systems meaningfully affect procedure economics and clinician preference.
-
W. L. Gore & Associates — Provider of the GORE CARDIOFORM family, with design features that target specific anatomical and handling considerations. Gore’s product discontinuations and portfolio streamlining efforts have reshaped clinical choice architecture in several centers.
-
Occlutech Holding AG — A notable recent entrant to the US market following FDA PMA approval and initial commercial implantations. Occlutech’s U.S. commercialization, enabled by distribution partnerships, is a leading near-term disruptor of incumbent channel dynamics.
-
Medtronic plc and Boston Scientific Corporation — Both offer structural heart device portfolios and have the commercial scale and hospital access to accelerate adoption where clinical differentiation is demonstrated.
-
Regional competitors (examples from Asia) — Manufacturers such as Lifetech and Lepu maintain strong home-market positions and are increasingly active in emerging-market supply strategies and selective regulatory filings for higher-margin geographies.
Recent regulatory and commercialization dynamics to incorporate
-
Notable approvals and market entries: Occlutech received a pivotal PMA and initiated U.S. commercialization activity following the decision — an event that rebalances competitive access in key structural-heart centers. Parallel approvals in earlier years for leading PFO/ASD occluders continue to shape the reference standard for clinical outcomes.
-
Device lifecycle actions: Some legacy devices have been discontinued while others have been recoded or rebranded following regulatory reviews. These actions create windows for newer devices to capture share by addressing residual clinical or handling limitations.
-
Delivery systems: Regulatory clearances for delivery systems and procedural kits (including recent clearances in late 2025) materially influence procedural time, training burden, and cost per case — factors our model converts into adoption multipliers.
Practical strategic implications for 2026 planning
For an executive setting 2026 priorities, the report translates macro growth into concrete actions across four lenses:
-
Commercial: Prioritize partnerships that accelerate access to high-volume structural-heart centers. Where internal sales coverage is limited, consider selective exclusive distribution or hybrid models that preserve margin while delivering local clinical support.
-
Clinical evidence: Invest in pragmatic RWE studies that close the few high-leverage evidence gaps identified in our adoption-pathway analysis (e.g., long-term comparative safety, device-specific anticoagulation protocols). Such studies are often more impactful and faster than large-scale randomized trials for commercialization.
-
Manufacturing & supply chain: Align capacity investments to the modeled mid-decade adoption inflection; overcapacity in the face of slow approvals or undercapacity after accelerated uptake both carry outsized costs. The report’s scenario P&Ls provide clear thresholds for timing investments.
-
Portfolio & R&D prioritization: Use the report’s product-matrix to identify high-return feature sets (e.g., retrievability, conformability, delivery profile) that command reimbursement premiums and clinician preference. R&D resource allocation should favor features with fast regulatory pathways and clear clinical differentiation.
Risk factors and contingency planning
PW Consulting’s stress-tested scenarios highlight several risk vectors 2026 planners must hedge against:
-
Regulatory unpredictability — PMA timelines, post-market surveillance outcomes, and device reclassification can shift adoption curves.
-
Payer actions — Coverage determinations and evidence thresholds vary across markets; payers can materially slow adoption if cost-offsets are not convincingly demonstrated.
-
Clinical practice drift — Procedural guidelines and patient selection criteria can constrain or expand addressable populations; early engagement with key opinion leaders reduces execution risk.
-
Competitive bundling — Incumbents with broad structural-heart portfolios may use bundled contracting to blunt new entrants; commercial teams must prepare countermeasures such as differentiated service offerings.
How to use this report in your 2026 playbook
Senior teams should use our report as both a strategic compass and an execution toolkit. Recommended immediate steps upon acquisition:
-
Run the included interactive workbook with your internal assumptions to produce tailored revenue and ROI scenarios for 2026–2028.
-
Map clinical-evidence programs to the adoption levers we identify and prioritize the smallest, fastest studies that close the largest commercial gaps.
-
Initiate early-stage distribution conversations in target regions flagged by our market-access sensitivity analysis and use our pricing templates to negotiate access while preserving margin.
-
Align R&D roadmaps to the device-feature sets our analysis shows will command adoption premiums and withstand reimbursement scrutiny.
Closing — the value proposition of the full report
PW Consulting’s Heart Defect Closure Devices Market study provides the empirical backbone for 2026 strategic decisions: a validated market size trajectory from USD 163.15 Million in 2020 to USD 215.0 Million in 2025, and a forecast to USD 344.8 Million by 2032 at a 6.98% CAGR. The full report embeds those headline numbers within a practical decision framework, including configurable financial models, regulatory and payer intelligence, and competitor playbooks. To preserve strategic differentiation, the public summary intentionally omits granular segment and region-level tables; the full intelligence package contains those detailed data layers, downloadable models, and a prioritized execution roadmap to convert market opportunity into profitable growth.
Contact PW Consulting to access the complete dataset, live model, and bespoke advisory engagements that translate these insights into 2026-ready actions.
For detailed analysis of this topic, please visit the official page: Heart Defect Closure Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


