



PW Consulting: Office Storage Market Set to Surge at 7.9% CAGR through 2032

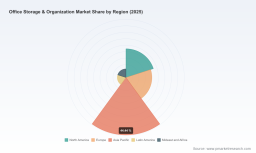
Office Storage & Organization Market — Strategic Brief for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concentrated preview of our latest Office Storage & Organization Market study. This brief synthesizes the high-level implications of a market currently valued at approximately USD 3.15 Billion in 2025 and forecast to grow to roughly USD 5.34 Billion by 2032, implying a compound annual growth rate (CAGR) of 7.9% over the forecast window. Our objective here is to show the strategic lines of sight that should shape corporate choices in 2026—while intentionally withholding the granular segment tables so that decision-makers visit the full report for executable detail.
Office Storage & Organization Market
Why this research matters for 2026 strategic choices
-
Corporate real estate optimization and hybrid work models are changing demand patterns for office storage solutions. Boards and procurement teams must reconcile spending discipline with the need to reconfigure workspaces for agility, safety, and employee experience.
Office Storage & Organization Market -
Manufacturers and distributors face simultaneous pressures: margin squeeze from raw-material volatility, labor-cost inflation, and tighter safety standards—each altering product economics and go-to-market priorities.
Office Storage & Organization Market -
Investors evaluating M&A or rollout strategies need an integrated view: total addressable market trajectory, concentration dynamics, channel economics, and practical playbooks for scaling in a fragmented market.
Market trajectory and primary macro drivers
The market has expanded steadily from the early 2020s into 2025, growing from an estimated USD 2.18 Billion in 2020 to about USD 3.15 Billion in 2025; this reflects both a rebound from pandemic-related contractions and structural shifts such as increased demand for modularity, high-density storage, and home-office solutions. Looking forward, the market’s projected rise to USD 5.34 Billion by 2032—at a 7.9% CAGR—signals sustained expansion driven by retrofits, corporate headquarters refresh cycles, and a growing aftermarket for organizational accessories and space-optimization services.
Key macro drivers worth emphasizing for 2026 strategy include:
-
Cost dynamics: The wood office-furniture PPI index reached elevated levels in mid-2025, creating cost headwinds that many suppliers will not be able to absorb without rethink of pricing and procurement strategies.
-
Regulation and safety: Emerging occupational safety requirements are increasing specification complexity—load-bearing and fire-resistance thresholds in particular—which affects design, materials choice, and aftermarket liabilities.
-
Raw-material volatility: Steel, wood composites, and engineered plastics remain sources of margin uncertainty. Efficient hedging, long-term supplier agreements, and design for material flexibility are now table-stakes.
-
Financing tailwinds: In select markets, access to long-term financing (for example, targeted U.S. loan programs supporting facility investments) lowers the effective hurdle for capex-heavy retrofit projects, creating an opportunity for bundled hardware + finance offerings.
Strategic imperatives for manufacturers, distributors, and investors in 2026
-
Prioritize supply-chain resilience: Secure diversified sourcing for steel, engineered plastics, and wood composites; use dual-sourcing and regional buffers to limit lead-time exposure.
-
Shift to value-based pricing for compliance-critical segments: Products requiring higher load ratings or fire-resistance should be priced and marketed as premium, service-backed solutions to protect margin.
-
Invest in modular and configurable offerings: Demand is trending toward adaptable systems that support space-efficiency and frequent reconfiguration, enabling higher lifetime revenue per square foot.
-
Build omnichannel capability: Firms that integrate showroom, catalog, and digital configurator channels—backed by fast fulfillment—will capture customers across corporate procurement and the growing home-office segment.
-
Embed service and subscription models: Installation, maintenance, and refurbishment services increase customer lifetime value and smooth demand seasonality.
-
Prepare for selective consolidation: The market concentration metrics reflect a fragmented competitive landscape—an opening for bolt-on acquisitions that add capacity, channel reach, or specialized product lines.
What the full report delivers — practical, action-oriented content
Our complete study is structured to support immediate strategy and operational execution. Highlights include:
-
Market sizing and forecast (2020–2032) with scenario variants tied to macroeconomic and material-cost pathways.
-
Segment analyses by region, product type, and application that translate market dynamics into prioritized growth pockets (note: detailed segment tables and regional heatmaps are available in the full report).
-
Competitive benchmarking with financial proxies, capability maps, and a buyers’ matrix to help you position product portfolios and channel propositions.
-
Supplier cost-driver model that isolates the primary levers affecting gross margin under different material and labor-cost scenarios.
-
Regulatory impact assessment with compliance checklists and design recommendations to de-risk product launches in core markets.
-
M&A and partnership playbook: target screens, valuation heuristics, and integration risk checklists calibrated to concentration dynamics and scale thresholds.
-
Go-to-market and commercial playbooks for producers, distributors, and large end-users—complete with sample KPIs, pilot templates, and procurement scripts.
Competitive landscape — positioning insight (high level)
The sector remains commercially diverse, with major global retailers, specialized manufacturers, and platform-enabled distributors all competing for distinct parts of the value chain. Measured concentration is modest—top-three firms capture roughly a quarter of market revenue and the top-five about thirty percent—indicating that national and regional players maintain substantial influence.
-
Retail-led players (examples include national organizers and mass-market furniture retailers) drive brand-led volume, scale manufacturing, and aggressive omnichannel execution. Their strength is price competitiveness and distribution breadth.
-
Specialist manufacturers and systems providers (high-density mobile shelving and engineered storage systems) compete on engineering, durability, and integrated service—important where compliance and space optimization are mission-critical.
-
Distributors and showroom operators blend curation with specification services to serve corporate buyers; their competitive edge lies in project management and tailored procurement workflows.
Recent market activity illustrates these dynamics: several established distributors and manufacturers released updated product catalogs in 2026, and product showcases through 2025–2026 have reinforced the push toward modular, design-forward, and durable storage systems. These developments underscore an ongoing investment cycle that will influence supplier selection and procurement timetables throughout 2026.
How C-suite and procurement leaders should use this research this year
-
Short-term (0–12 months): Implement a rapid SKU rationalization and material hedging program; launch a pilot for a service-wrapped modular storage solution to capture retrofit budgets.
-
Medium-term (12–36 months): Build or partner for omnichannel sales capability (digital configurator + showroom + fulfillment), expand service offerings, and evaluate tuck-in acquisitions that fill capability gaps.
-
Long-term (36+ months): Consider regional manufacturing footprints to mitigate freight and material volatility, invest in sustainable materials and compliance certifications that will command pricing premiums, and institutionalize scenario-based planning into product roadmaps.
Why PW Consulting’s study is uniquely actionable
This report marries robust quantitative forecasting with hands-on commercial playbooks. Our methodology blends primary interviews across the value chain, real-world procurement benchmarking, and a transparent cost-driver model so clients can simulate outcomes under different pricing, regulation, and raw-material scenarios. Where other studies stop at forecasts, we translate projected demand into precise commercialization and M&A blueprints designed to be implemented within 6–18 months.
Next steps — where to find the full intelligence
This brief highlights the strategic choices arising from a market that is expanding at a near-8% CAGR into the next decade and that is shaped by cost pressure, regulatory complexity, and evolving workplace design. For the confidential segment-level heatmaps, channel economics worksheets, company scorecards, and the full set of playbooks referenced above, access the full Office Storage & Organization Market report. The detailed breakdown is intentionally withheld here to preserve actionable advantage for subscribers and clients—contact PW Consulting to unlock the complete intelligence and the financial models that power 2026 decisions.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


