



PW Consulting: Guitar Amplifier Market to reach USD 182.7 Million by 2032 (2.11% CAGR)

Guitar Amplifier Market 2026: Strategic Preview for Decision‑Makers
Executive preview
As companies enter 2026, the guitar amplifier market sits at a familiar crossroads: durable, heritage‑driven demand on one hand, and rapid technical and supply‑chain disruption on the other. PW Consulting’s latest study uses a 2025 base year and an expanded 2026–2032 forecast to translate these forces into decision‑grade intelligence. The global market reached USD 142.0 Million (revenue, 2025 base) and — based on scenario testing and structural drivers — is projected to grow at a steady 2.11% CAGR across the forecast window, reaching roughly USD 182.7 Million by 2032. That steady headline growth masks meaningful pockets of opportunity and risk that will determine winners and losers during CEOs’ 2026 strategy cycles.
Guitar Amplifier Market
Why this study matters for 2026 strategy
-
Allocation of scarce capital. With moderate overall growth, 2026 will be a year of portfolio prioritisation: invest behind high‑velocity subsegments and consolidate or harvest slower niches. Our modelling translates macro growth into investment thresholds, payback windows, and risk bands executives can use when deciding capex vs. R&D tradeoffs.
Guitar Amplifier Market -
Channel & product mix optimization. The interplay between legacy tube expertise and newer modeling/digital propositions is reshaping distribution economics. Tactical choices about direct‑to‑consumer vs. dealer networks will materially affect margin capture in 2026.
Guitar Amplifier Market -
Supply‑chain resilience. Elevated input costs and tariff volatility mean sourcing strategy is no longer back‑office: it’s board‑level. Our report quantifies how transformer lead times, tariff exposure, and localized manufacturing affect time‑to‑market and COGS for common amp architectures.
-
M&A and partnership cadence. With mid‑market fragmentation and a modestly concentrated vendor landscape, 2026 is prime for bolt‑on acquisitions or strategic alliances that close capability gaps quickly. The analysis provides an M&A heat map and valuation sensitivity for acquirers.
Market trajectory — what the numbers conceal and reveal
The headline trajectory — USD 142.0 Million in 2025 expanding to approximately USD 182.7 Million by 2032 at a 2.11% CAGR — reflects a market that is mature but dynamically re‑shaping. The modest annual growth rate highlights several structural realities: product lifecycles extend, consumer upgrades are selective, and premiumization is uneven across geographies and distribution channels.
Our forward scenarios decompose that aggregate growth into technology cycles (tube vs. solid‑state vs. modelling/digital), channel evolution (retail, direct, subscription/streaming bundles), and aftermarket consumption (parts, transformers, service). Each scenario produces distinct margin and working capital profiles that senior teams can map to their capital plans for 2026.
Segmentation — what we show and what we deliberately withhold
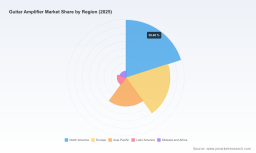
The report contains a granular segmentation framework across region, type (combo, head, etc.), and application (commercial, household, prosumer). For reasons of competitive sensitivity and to preserve the "trailer" nature of this executive preview, we intentionally withhold raw segment share tables and line‑item regional revenue by value. Instead, PW Consulting offers high‑value derivative outputs in the study:
-
Segment‑level growth rates and elasticity curves (directional, indexed values, and drivers).
-
Price‑to‑volume sensitivity models for the principal product archetypes, enabling margin impact analysis under different raw material and tariff assumptions.
-
Scenario heatmaps that show where a 1% shift in demand or cost materially changes NPV for different business models.
To preserve decision leverage, the full numerical segment tables, regional splits, and downloadable forecast model are accessible only through the full report page.
Competitive landscape — who matters in 2026
The amplifier market combines household names with boutique specialists. Market concentration is moderate: the top three vendors account for a meaningful share of revenue, and the top five extend that footprint further, leaving a sizable independent segment where nimble innovation and route‑to‑niche can succeed. Our peer analysis covers product portfolios, channel strategies, and R&D trajectories for leading manufacturers, including:
-
Fender Musical Instruments Corporation — a broad product slate spanning tube, modelling, and digital lines, with ongoing anniversary and heritage‑product plays that help maintain resale value and aftermarket demand.
-
Gibson Brands, Inc. — rebuilding amp credentials through brand extensions and relaunch programs that target both legacy customers and value segments under subsidiary brands.
-
Marshall Amplification — the archetypal high‑gain, tube‑centric brand with deep licensing and artist relationships that sustain premium ASPs.
-
PRS Guitars — leveraging boutique credibility into tightly scoped combo amp offerings that target session players and touring pros.
-
Friedman Amplification and Benson Amps — boutique builders that have become price and supply‑chain bellwethers for the high‑end tube market.
-
BOSS Corporation and Orange Amplification — leaders in modelling, hybrid and compact form factors, often outpacing legacy adopters in consumer markets.
-
Peavey Electronics and Hammond Manufacturing — representing scale manufacturing and critical parts supply, respectively; their strategies and capacity plans shape cost baselines across the industry.
Each company profile in the full report includes a capability matrix, distribution map, recent product pipeline developments, and a quantified "strategic flex" score that rates how readily each firm can shift product mix, price, and sourcing in response to 2026 shocks.
Operational dynamics and near‑term risks
Two operational themes should dominate executive attention in 2026:
-
Tariff & trade friction. Recent policy moves have re‑rated cross‑border manufacturing economics. Notable examples include new surtaxes and targeted tariffs affecting components and finished amplifiers. These measures can add material landed cost to boutique and imported heads and require scenario hedging at the price‑setting level.
-
Component bottlenecks and cost inflation. Critical inputs — particularly transformers and high‑voltage components used in tube amplifiers — have experienced steep price increases and lengthened lead times. Supplier statements and market monitoring indicate price inflation well into the high‑double‑digit range for certain transformer classes, with lead times stretching up to multiple years for specialized units. This dynamic forces design‑for‑supply and sourcing diversification to the top of 2026 agendas.
The full study translates these disruptions into three operational playbooks: short‑term procurement hedges, mid‑term localization and supplier development, and longer‑term platform redesigns that reduce dependency on constrained parts while protecting tonal authenticity.
Recent product and market signals (selected)
-
Fender’s 2026 product refresh, including heritage edition updates, reaffirms the commercial value of anniversary and nostalgia plays for maintaining premium pricing and aftermarket sales.
-
Friedman’s and PRS’s recent small‑format combo launches highlight demand for lower‑wattage, boutique tonal options — a signal for manufacturers and distributors to re‑evaluate SKUs and marketing focus.
-
BOSS’s continual investment in compact modelling amplifiers shows the bottom‑end and practice markets remain innovation hotspots, particularly where Bluetooth connectivity and lightweight effects integration matter.
What the report contains — practical deliverables
-
Full downloadable financial model (2020–2032) with scenario toggles for tariffs, input inflation, and demand shocks.
-
Segment demand index and pricing ladder for product archetypes and channels (published as indexed series to preserve consultative value).
-
Supplier and risk heat maps, including transformer and tube supplier capacity, with mitigation pathways and sourcing checklists.
-
Go‑to‑market playbooks for OEMs and distributors (channel economics, digital engagement, service and warranty strategies).
-
M&A heat map and target scoring, cross‑checked against market concentration metrics and margin decompositions.
Strategic implications & recommended 2026 actions
-
Prioritize product platforms that reduce exposure to constrained components while preserving core product DNA. Tactical redesigns, modular output stages, and hybrid amplification approaches can cut supplier risk and shorten time‑to‑market.
-
Reassess pricing architecture to explicitly incorporate tariff and logistics volatility. Indexed surcharges, hedging structures, and dynamic dealer rebates can protect margins without eroding brand value.
-
Choose selective M&A to fill capability gaps — not market share alone. Targets that bring local manufacturing, parts supply, or digital modelling IP will deliver more durable returns under current market dynamics.
-
Invest in customer lifetime value programs and service revenue streams to offset slower unit growth — extended warranties, re‑tubing subscriptions, and certified refurbishment channels are low‑risk margin enhancers.
Next steps — how to use this preview
This executive preview frames the 2026 strategic debate. For teams preparing budgets, three immediate actions are advisable: (1) run the PW Consulting model against your company’s product mix to identify break‑even exposure to tariff and transformer shocks; (2) convene cross‑functional sourcing/design sprints to identify two low‑dependency platform variants for 2027 launch; and (3) shortlist potential bolt‑ons informed by our M&A heat map and strategic flex scores.
Accessing the full intelligence
PW Consulting’s full Guitar Amplifier Market report contains the underlying tables, downloadable models, and raw segment outputs that this preview omits. If your 2026 planning requires line‑by‑line segment data, regional forecasts, or supplier contact matrices, the full report provides those assets together with a tailored advisory workshop option for implementation planning.
For 2026, the question for leadership is not whether the market will grow — it will — but whether your organisation is positioned to convert modest market expansion into outsized returns through supply‑chain agility, focused product investment, and selective strategic deals. PW Consulting’s study provides the empirical backbone and playbooks to make that conversion systematic.
For detailed analysis of this topic, please visit the official page: Guitar Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


