



PW Consulting: Plating Equipment Market Poised for 6.5% CAGR to USD 279.35M by 2032

Plating Equipment Market — A 2026 Strategic Outlook for Industrial Leaders
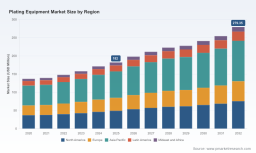
As capital allocation rounds intensify and supply-chain fragilities persist, boards and executive teams face a pivotal set of choices in 2026 for the plating equipment sector. PW Consulting’s latest market study — anchored on a 2025 base year, with historical analysis across 2020–2025 and forecasts for 2026–2032 — translates industry complexity into a pragmatic decision framework. The global market grew from roughly USD 137 Million in 2020 to USD 182 Million in 2025 and is projected to expand to about USD 198.01 Million in 2026, following a compound annual growth rate (CAGR) of 6.5% across the forecast interval and reaching approximately USD 279.35 Million by 2032. This report is designed not as a catalog of numbers alone, but as a strategy dossier: mapping where value pools will form, how competitive dynamics will shift, and what operational playbooks are required to capture upside while mitigating regulatory and commodity risks.
Plating Equipment Market
Why this report matters for 2026 decisions
-
Capital allocation with conviction — With the market expanding at mid-single-digit CAGR, equipment OEMs and large end-users must prioritize investments that accelerate automation and sustainability rather than incremental capacity alone. The report quantifies payback horizons under realistic adoption curves, enabling CFOs to compare CAPEX scenarios rigorously.
Plating Equipment Market -
Risk-adjusted supply chain planning — Commodity and geopolitical shocks are no longer tail risks. Our analysis integrates real-world indicators — from copper anode price spikes tied to EV battery demand to export controls affecting critical magnetics and components — translating them into procurement and inventory strategies for 2026.
Plating Equipment Market -
Regulatory preparedness as a competitive edge — New effluent and wastewater treatment standards (e.g., updated EPA limitations effective 2025) reshape the economics of plating installations. Early movers who retrofit or adopt low-waste chemistries can avoid retrofit costs and gain market access faster.
-
Talent and automation trade-offs — Labor constraints are driving OEMs and processors toward robotic integration and selective plating technologies. Our scenarios show how automation can compress unit costs and reduce compliance exposure, but they also identify where human expertise remains irreplaceable.
What the report contains — practical, deployable intelligence
-
Transparent market sizing and forecast methodology: detailed base-year reconciliations and sensitivity runs that stress-test demand against copper price, regulatory tightening, and end-market cycles (automotive, electronics, aerospace, jewelry, and industrial segments).
-
Scenario modeling: three calibrated futures (Base, Accelerated Automation, and Regulatory Shock) with implied demand curves, margin impacts, and capital requirements. Each scenario includes suggested tactical responses for 90-day and 12-month horizons.
-
Competitive benchmark & capability matrix: comparative analysis of major solution providers, including integrated chemistry‑plus‑equipment firms, specialist brush- and selective-plating vendors, turnkey systems integrators, and service-driven suppliers. Profiles capture strategic positioning, technological strengths, go‑to‑market models, and aftermarket footprints.
-
Procurement and CAPEX playbooks: decision trees for selecting between retrofit vs. greenfield configurations, TCO calculators in USD Million terms, and contract structures that align OEM incentives with long-term performance.
-
Regulatory and environmental compliance toolkit: step-by-step guidance for wastewater treatment upgrades, chemical substitution strategies, and emissions monitoring — including vendor shortlists and estimated implementation timelines.
-
Investor diligence pack: tailored synopses for private equity and strategic buyers covering market concentration, exit multiples under different scenarios, and integration risks for bolt-on acquisitions.
Competitive landscape: incumbents, challengers, and tactical moves
The plating equipment ecosystem remains moderately fragmented — market concentration metrics show top-three and top-five firm shares that permit both scale advantages and niche opportunities. Several archetypes dominate strategic thinking:
-
Integrated chemistry + equipment leaders: Firms that combine plating chemistries with turnkey equipment can accelerate customer adoption of lower-waste processes and lock-in aftermarket chemical sales. These players invest in platform-level R&D and leverage trade events to showcase integrated offerings — recent industry activity includes prominent participations at JPCA and SUR/FIN where integrated PCB and advanced packaging solutions were highlighted.
-
Selective and brush plating specialists: Companies concentrating on on-site repair, selective plating, and brush systems sustain strong relationships with maintenance-heavy end-users (aerospace repair, critical industrial components). Their value lies in service models and rapid deployment capabilities.
-
Turnkey systems integrators and automation players: Automation-focused OEMs are introducing new fixture designs (for example, recent launches of advanced barrel geometries) and robotics integrations to address labor shortages and throughput demands for high-mix manufacturers.
-
Vertical-focused suppliers: Smaller firms continue to win in jewelry and specialty markets through gold and decorative plating kits, leveraging domain-specific knowledge and responsiveness.
Representative company examples profiled in the study include leading integrated chemistry and turnkey providers, global specialty-chemistry and brush plating leaders, and regional equipment suppliers and integrators. The report synthesizes public announcements and proprietary intelligence — such as trade show showcases and product launches — and translates them into strategic implications for customers and competitors alike.
Industry dynamics that will shape winners in 2026
-
Environmental regulation: Manufacturers that pre-empt EPA-style effluent rules and invest in low-waste chemistries will avoid future compliance penalties and gain preferential status with OEM customers requiring secured supply chains.
-
Commodities and component availability: Spikes in copper and constraints in rare-earth dependent components (driven by export controls) will favor suppliers with diversified sourcing, substitution roadmaps, and recycling programs.
-
Labor and automation: Skilled labor shortages increase the ROI on robotic plating cells and selective automation; however, companies must balance capital intensity with flexible capacity to serve high-mix clients.
-
Service and aftermarket: As lead times extend for new equipment, aftermarket services, retrofits, and chemical supply contracts become reliable revenue engines; service-centric business models will outpace pure hardware players in margin resilience.
Actionable playbook for executives — immediate and strategic moves
-
For OEMs and contract platers: Initiate a 90-day audit of wastewater and chemical usage tied to a 12-month retrofit plan for low-waste processes. Price in commodity hedging for critical inputs and negotiate longer-term chemical supply agreements to stabilize margins.
-
For equipment manufacturers: Prioritize modular automation platforms and software-enabled service offerings; deploy a second-source strategy for components exposed to export controls and run scenario tests against copper price surges.
-
For investors: Use the report’s scenario outputs to stress-test exit multiples under regulatory and commodity shock models. Target acquisitions that provide service or chemistry lock-ins rather than pure hardware plays.
-
For policymakers and large buyers: Encourage standards alignment and provide incentives for adoption of low-waste chemistries; coordinate with suppliers to pilot technology demonstrators that de-risk broader procurement programs.
What sets PW Consulting’s study apart
This analysis is not an aggregation of public filings; it combines field interviews, supplier capability scoring, regulatory mapping, and a proprietary demand model calibrated to historical market transitions (2020–2025). Our forecast series (2026–2032) is presented in multiple realistic scenarios and is accompanied by downloadable CAPEX/TCO tools denominated in USD Million to help executives run deterministic sensitivity analyses. Critically, the full report includes granular segment-level forecasts, regional supply maps, and transaction comparables that we have intentionally reserved for report subscribers to preserve competitive advantage.
Next steps — how to use this insight in 2026
Leaders who treat 2026 as an execution year rather than a wait-and-see period will capture disproportionate share gains. Use the report to (1) prioritize retrofit and automation projects with quantified ROI thresholds, (2) secure supply contracts and diversification plans for volatile inputs, and (3) identify acquisition targets that shift revenue mix toward recurring services. For teams preparing investment committees or board briefings, the study supplies slide-ready scenario outputs and a checklist of regulatory and operational triggers to monitor month-by-month.
To access the complete dataset, segment-level forecasts, vendor scorecards, and the CAPEX modeling toolkit, consult the full Plating Equipment Market report on PW Consulting’s portal. The executive briefing provided here is deliberately calibrated to convey strategic depth while preserving the detailed actionable intelligence available to subscribers.
For detailed analysis of this topic, please visit the official page: Plating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


