



PW Consulting: Calcium Sulfate Market to Reach USD 385.32M by 2032 at 4.2% CAGR

Calcium Sulfate Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare budgets and capital plans for 2026, the calcium sulfate market presents a blend of steady growth, supply-side disruption and regulatory momentum that will shape strategic choices across industrial, agricultural and specialty segments. PW Consulting’s forthcoming full report — grounded in five years of historical tracking (2020–2025) and a seven‑year forecast horizon (2026–2032) — quantifies that backdrop and translates it into actionable options for producers, consumers, investors and policy-facing stakeholders.
Calcium Sulfate Market
Market at a Glance: Macro Trajectory and Competitive Texture
Our market model places 2025 as the base year. The global calcium sulfate market expanded from approximately USD 235.2 Million in 2020 to USD 288.9 Million in 2025, and PW Consulting projects the market to reach roughly USD 385.3 Million by 2032, representing a compound annual growth rate (CAGR) of about 4.2% across the 2026–2032 forecast period (values in USD Million). This steady compound growth reflects a balance of mature end‑use demand in construction and industrial applications, incremental gains in agriculture and food/pharmaceutical uses, and growing momentum for specialty and value‑added derivatives.
Calcium Sulfate Market
Concentration metrics in our competitive assessment show a moderately consolidated industry: the top three firms account for around 58% of identifiable market share, while the top five reach roughly 62%. That structure creates both stability and pressure points: established players have pricing influence and distribution reach, but mid‑sized and niche innovators can exert outsized local influence through product specialization or targeted logistics improvements.
Calcium Sulfate Market
Why This Matters for 2026 Decision Cycles
-
Capex and capacity planning: With a predictable mid‑single‑digit growth path, capital investments should prioritize flexibility and product mix optimization over large, inflexible greenfield bets. Timing of new capacity must be aligned with feedstock trends and regulatory developments to avoid stranded assets.
-
Supply security and feedstock strategy: Shifts in synthetic gypsum availability — linked to the accelerated retirement of coal‑fired power plants in several markets — are altering feedstock economics and increasing the strategic value of vertically integrated sources and recycled streams.
-
Regulatory and value‑chain repositioning: Emerging guidance on handling and reuse (for example, national environmental agencies encouraging agricultural and industrial reuse of flue gas desulfurization gypsum) is creating new commercial pathways but also increasing compliance and documentation burdens.
-
Margin capture and product differentiation: As base demand remains steady, growth in margins will come from higher‑value grades, blended fertilizers, specialty food/pharma‑grade products and service‑based propositions (quality assurance, customized logistics, technical support).
What the PW Consulting Report Delivers (Practical, Transaction‑Ready Content)
The full PW Consulting market study is built for decision makers who need to act in 2026. Highlights of the deliverables include:
-
Robust market sizing and forecast models: Five years of historicals (2020–2025) and seven years of forecast outputs (2026–2032) with scenario toggles for demand elasticity, price stress and feedstock constraints.
-
Value‑chain mapping and cost stack analysis: Farm to factory mapping, typical unit economics for different product forms, and sensitivity tables for raw‑material price swings and logistics cost shocks.
-
Commercial playbook for market entry and expansion: Channel strategies, tender participation templates, sample offtake and distribution contract clauses, and go‑to‑market scorecards for prioritizing regional investments.
-
Regulatory impact assessment and compliance checklist: Actionable steps to convert regulatory shifts — such as guidance to encourage reuse of gypsum streams — into commercial opportunities while limiting liabilities.
-
Competitive intelligence and benchmarking tools: Confidential profiles, performance benchmarks and strategic positioning matrices for incumbent and emerging players, along with an M&A heat map identifying targets and acquirers likely to move in 2026.
-
Supply disruption scenarios: Triggers and lead times tied to feedstock scarcity (e.g., decline in synthetic gypsum availability), logistics constraints and policy changes; mitigation playbooks for each scenario.
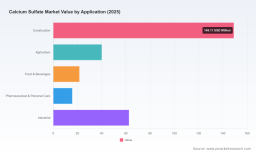
Note: This preview intentionally withholds the granular segment breakdowns and regional/application tables that are included in the paid report. Those segmented data, price curves and downloadable models are essential for transaction diligence and are available through PW Consulting’s full deliverable.
Competitive Landscape — Strategic Implications from Company Profiles
Our qualitative and quantitative assessment of market participants highlights diverse strategic postures:
-
CB Minerals (Mamaroneck, NY): A diversified supply base spanning dihydrate, hemihydrate and anhydrous forms, with sourcing from multiple countries. Their blended product availability and cross‑market footprint make them a logical partner for industrial customers seeking reliability and product breadth. Strategic implication: direct competitors and offtakers should expect a strong focus on logistics and blended SKU convenience from CB Minerals.
-
The Kish Company (Mentor, OH): Positioned as a supplier and processor of calcium sulfate for industrial extension and additive markets. Their processing expertise suggests they can capture margin through tailored particle sizing and surface treatment. Strategic implication: companies targeting industrial formulations should prioritize technical collaboration to lock in co‑development advantages.
-
Hebei Xingtai Shuanghua Gypsum Products (Xingtai, China): A manufacturer/exporter with competencies in food‑grade and pharmaceutical applications. Their product mix targets higher‑value end uses that require stringent quality controls. Strategic implication: firms seeking to expand into food and pharma markets must invest in regulatory certifications and traceability systems to compete.
-
SUL4R‑PLUS (Illinois, USA): An emerging, agriculture‑focused player producing granular calcium sulfate fertilizer blends. A recent strategic move — the April 2025 opening of a 100,000‑ton annual capacity facility in Marissa, Illinois — underscores the near‑term growth potential in agri‑blends and the competitive advantage from proximity to key agricultural zones. Strategic implication: agribusiness buyers and regional distributors should re‑evaluate supply contracts and distribution footprints to capitalize on lower delivered costs and customized blend capabilities.
These profiles, combined with PW Consulting’s benchmarking metrics, reveal where competitive advantage rests — product breadth and logistics for large suppliers, technical customization for mid‑size processors, and targeted agricultural or specialty focus for niche entrants.
Regulatory and Feedstock Dynamics: Near‑Term Disruption and Opportunity
Two regulatory and raw‑material trends warrant immediate attention in 2026 planning:
-
Regulatory guidance driving reuse: National environmental authorities in several countries have issued guidance to encourage the safe reuse of flue gas desulfurization (FGD) gypsum in agriculture and industry. Companies that can demonstrate robust sampling, certification and traceability will be positioned to capture this stream as a lower‑cost input — but compliance costs and reputational risk must be managed.
-
Decline in synthetic gypsum availability: Accelerated retirements of coal‑fired generation have already started to reduce synthetic gypsum volumes in some markets, tightening what had been an abundant secondary feedstock. The supply contraction amplifies the value of owned deposits, recycling infrastructure and long‑term offtake agreements.
Recommended Strategic Moves for 2026
For executives formulating 2026‑era strategy, PW Consulting recommends a measured portfolio of actions that balance resilience and growth:
-
Secure feedstock diversity: Negotiate multi‑source offtake agreements, explore partnerships with utilities and cement plants for recycled streams, and assess modest investments in beneficiation to widen acceptable feedstock types.
-
Prioritize higher‑margin applications: Allocate R&D and certification budgets toward food and pharmaceutical grades, specialty agricultural blends and engineered gypsum products that command price premiums and more stable demand.
-
Invest in logistical efficiency: Given the bulk nature of product flows, micro‑optimizations in terminal positioning, rail/road contracts and packaging can yield outsized margin improvements.
-
Monitor and shape regulation: Engage proactively with regulators on reuse protocols and material standards to both reduce compliance risk and open new markets for reclaimed gypsum.
-
Prepare M&A and alliance playbooks: With a moderately concentrated market structure, bolt‑on acquisitions and joint ventures can rapidly expand geographic coverage or add specialty capabilities — but due diligence must include our scenario stress tests for feedstock volatility.
Risk Triggers and Early‑Warning Signals
Key triggers to watch in 2026 that should prompt tactical shifts include:
-
Announcements of large coal plant decommissions or changes in power‑sector FGD management that would further skew synthetic gypsum flows.
-
New or revised national rules on gypsum reuse that materially change compliance timelines, handling costs or allowable applications.
-
Rapid capacity additions from low‑cost producers targeting agricultural blends in specific regions, which could compress regional spreads.
-
Logistics disruptions (port congestion, freight rate spikes) that affect delivered costs for bulk commodities.
Next Steps — How PW Consulting Supports 2026 Decisions
PW Consulting’s full Calcium Sulfate Market report provides the segment‑level data, regional demand matrices, pricing curves and executable playbooks that trading desks, corporate strategy teams and private equity investors need to finalize 2026 commitments. If your objectives include contract negotiation, capacity planning, or opportunity screening for M&A, our models — which include downloadable scenario toggles and a confidential supplier shortlist — will materially shorten your decision cycle and reduce execution risk.
For readers of this preview: this briefing highlights the levers and risks that will define competitive advantage in 2026, but the granular segmentation, supplier‑level benchmarking and financial models that enable binding decisions are reserved for the full PW Consulting deliverable. Contact PW Consulting to access the complete dataset and transaction toolkit.
For detailed analysis of this topic, please visit the official page: Calcium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


