



PW Consulting: Epoxidized Soybean Oil Market Poised for 7.58% CAGR

Epoxidized Soybean Oil (ESBO) Market: Strategic Primer for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present a concentrated strategic primer to frame your 2026 planning for the Epoxidized Soybean Oil (ESBO) value chain. This briefing synthesizes our independent market sizing, competitive landscaping, and risk matrix to show where commercial advantage will be won — while reserving the granular segment-level forecasts and model outputs for the full study.
Epoxidized Soybean Oil Market
Why ESBO deserves executive attention in 2026
- ESBO is at the intersection of commodity agriculture and specialty chemicals: it is a bio-based additive with direct sensitivity to soybean oil availability, commodity price cycles, and shifting regulatory regimes tied to plastics and fuels.
- Our base-year market sizing (2025) anchors strategy decisions: the global ESBO market sits just below a half‑billion USD in revenue (2025 base), and our forecast path — underpinned by a 7.58% compound annual growth rate — points to a material scaling opportunity through the 2026–2032 horizon.
- Structural change is underway. Demand dynamics are being reshaped by PVC formulation shifts, sustainability-driven procurement, biofuel policy impacts on feedstock flows, and targeted trade remedies. These forces create both margin pressure and differentiation opportunities for producers, distributors and downstream formulators.
What the 2026 strategic landscape looks like (high level)
- Growth momentum: After steady expansion over 2020–2025, the ESBO market accelerates into the forecast period supported by stronger demand in traditional plasticizer and stabilizer applications plus broadened uptake in specialty uses. Our scenario models show the market roughly doubling in scale from the early 2020s over the medium term under the baseline case.
- Supply-side concentration: The sector exhibits moderate concentration among leading producers and integrated agribusinesses, creating oligopolistic dynamics for sourcing and premium product positioning. Competitive advantage will accrue to firms that combine feedstock control, technical grade differentiation, and route-to-market strength.
- Volatility vectors: Raw material availability (soybean oil), regulatory shifts (trade probes and food-contact rules), and renewable diesel policy are primary sources of near-term upside/downside risk. Commercial teams should assume episodic price swings and intermittent trade restrictions when stress-testing 2026 plans.
How PW Consulting’s ESBO research supports board-level decisions
Our full study is built for executives who must convert market intelligence into defensible action. We structure the work around four decision-use modules:
Epoxidized Soybean Oil Market
- Market Sizing & Scenario Forecasting — transparent methodology, baseline and alternate-path scenarios, and sensitivity to feedstock price and regulatory shocks.
- Commercial Due Diligence — supplier and buyer scorecards, channel economics, margin waterfall analysis, and a pricing playbook designed to navigate volatility while protecting market share.
- Portfolio & Product Strategy — product differentiation levers (e.g., food-contact certification, Kosher status, high-IV/heat-stable grades), licensing and co-development frameworks for formulators, and premiumization pathways for specialty ESO variants.
- M&A and Capex Roadmap — target screens for strategic acquisitions (vertical integration, regional converters, niche specialty players), greenfield vs brownfield build templates, and payback scenarios under multiple commodity-price regimes.
Each module contains executable outputs: decision matrices, model kits, playbooks, and a prioritized action list to be operationalized in 90-, 180- and 360-day horizons.
Epoxidized Soybean Oil Market
Competitive dynamics — what leading firms are doing
The competitive landscape is shaped by a mix of global specialty chemical suppliers, agrichemical/agribusiness integrators, regional manufacturers, and distributors. Across this set, three strategic postures prevail:
- Scale + feedstock control (vertical integration): Large agribusinesses that integrate soybean crushing into their operations can shield margins when crude oil or biodiesel policy diverts feedstock. These firms often have the flexibility to prioritize internal offtake or participate in spot markets selectively.
- Specialty differentiation: Chemical suppliers that combine certification credentials (food-contact, Kosher), tailored formulations, and heat-stable/high-performance grades aim to capture value above commodity ESBO levels. Recent product promotions and launches underscore the importance of technical depth to win formulation share in PVC and niche end-uses.
- Channel & services play: Distributors and toll manufacturers emphasize logistics, packaging flexibility (drums/totes/bulk), and rapid technical support. For many end users, sourcing stability and timely product qualification are as critical as unit price.
Notable recent moves reinforce these themes: capacity upgrades and modernization projects have expanded output capability; new ESBO variants focused on improved compatibility or thermal stability have been launched; and product promotions highlight food-safe and renewable credentials as a commercial differentiator. These developments indicate the market is maturing from a commodity-buyer environment toward one where technical and certifiable product attributes command premium access to certain channels.
Key commercial implications for 2026 planners
- Hedge feedstock risk strategically: Given the tight linkage to soybean oil supply, procurement teams should layer contracts (long-term offtake, index-linked clauses, and option-based hedges) and explore direct sourcing partnerships to manage price exposure and availability.
- Invest in product credentials: Certification (food-contact, Kosher) and demonstrable performance (heat stability, compatibility) accelerate adoption in regulated end markets. R&D and regulatory investment are high-leverage moves that improve price realization and reduce churn.
- Prepare for regulatory theater: Ongoing trade investigations and local content scrutiny require an agile compliance function and contingency sourcing plans. Rapid re-routing capability and tariff mitigation strategies can be decisive during episodic market shocks.
- Deploy selective downstream integration: CPF (capacity, flexibility, footprint) analysis suggests selective M&A or JV activity — particularly in regions with demand growth or where logistics create a competitive moat — can be accretive to margin and resilience.
- Differentiate through service: For converters and formulators, reliable supply, technical service, and packaging flexibility often trump the lowest-cost offer. Sales models should align around value selling rather than strict commodity procurement pitches.
Risk map: what to watch through 2026
- Raw-material pressure: Changes in soybean oil allocation (e.g., diversion to biofuel mandates) can tighten availability and lift prices; procurement teams must stress-test models for multiple feedstock-disruption scenarios.
- Trade and anti-dumping actions: Recent investigations in certain jurisdictions have already impacted flows; expect episodic protectionist measures that re-route trade lanes and alter landed cost math.
- Regulatory & sustainability standards: Evolving plastics regulation and increasing demand for renewable/traceable feedstocks create both barriers and premium opportunities; firms that fail to document chain-of-custody will see limited access to higher-value contracts.
- Technology and substitution risk: New plasticizer chemistries or formulations that reduce reliance on ESBO could emerge; continual product innovation is therefore essential to maintaining relevance.
What the full PW Consulting report contains (practical deliverables)
- Comprehensive market model with transparent assumptions, scenario toggles, and downloadable model artifacts for board use.
- Supply-chain heat maps and supplier scorecards highlighting capacity, technical capability, and strategic fit for potential partners or acquisition targets.
- Regulatory tracker and tariff scenarios tailored to priority markets, plus playbooks for rapid response to trade remedies or import restrictions.
- Commercial levers playbook: pricing frameworks, contract templates, logistics optimization, and SKU rationalization guidance.
- M&A screening dossier with high-probability targets, valuation benchmarks, and integration risk checklists.
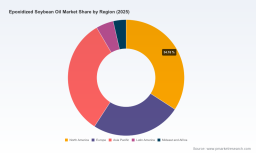
Note: The full report contains granular regional and application-level forecasts, detailed split analytics, and company-level volume/price matrices. In keeping with this primer’s “trailer” design, those detailed segment outputs are intentionally withheld here to channel readers to the source study for the complete intelligence package.
Next steps for executives
- Use the headline market sizing and CAGR outlook in this primer to calibrate top-line targets and stress scenarios for 2026 budgeting cycles.
- Commission a rapid commercial due diligence (4–6 week sprint) if you are considering capacity investment, a JV, or an acquisition in the ESBO chain — the timing is right to capture first-mover advantages before premium segments harden.
- Initiate cross-functional workshops (procurement, R&D, regulatory, sales) to define a 180-day plan focused on feedstock resilience, product-certification upgrades, and targeted customer pilots.
For teams ready to translate these insights into actionable plans, PW Consulting offers the full ESBO market study along with bespoke advisory engagements to operationalize the recommendations. Our models and playbooks are built to be immediately integrated into 2026 capital allocation and commercial strategies.
Closing
ESBO is no longer merely a commodity intermediate — it is a strategic lever for formulators, a hedged commodity for agribusinesses, and a focal point for sustainability claims across plastics and packaging. With a clearly defined market trajectory and identifiable risk corridors, 2026 is the year to move from reactive sourcing to strategic positioning. PW Consulting’s full report gives you the maps and decision toolkits to do precisely that.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


