



PW Consulting: Dental Drug Market to Reach USD 6,831.9M by 2032 with 6.2% CAGR

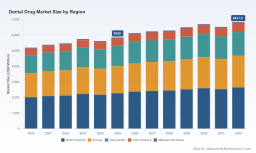
Dental Drug Market 2026 — Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a succinct, actionable preview of our new Dental Drug Market study — a practitioner's guide for boards, corporate strategy teams, and private capital preparing decisions in 2026. Anchored on a 2025 base year and a robust 6.2% compound annual growth rate (CAGR) through the near-term forecast, this research translates macro momentum into decision levers you can operationalize today. The purpose of this preview is to outline the strategic value of the full report: we will demonstrate analytical depth and signal the most consequential implications for 2026 moves while intentionally withholding the granular segment tables and proprietary data sets to direct you to the full study for transaction-level intelligence.
Dental Drug Market
Why this study matters in 2026
-
Market scale and trajectory: The dental drug market reached a substantial scale in 2025 (base year) and is poised to expand at a mid-single-digit CAGR. That combination of size and steady growth makes the sector a target for both incremental product strategies and transformative M&A plays.
Dental Drug Market -
Strategic inflection points: Shifts in payer dynamics, regulatory cost structures, and concentrated supplier footprints are creating differentiated winners and losers. Timing and sequencing of investment — not just capability — will determine whether incumbents defend margins or new entrants capture share.
Dental Drug Market -
Decision urgency: For commercial leaders planning product launches, for supply-chain leaders sizing capacity, and for investors underwriting private deals, 2026 is a preparatory year: structural changes in pricing and regulation will begin to materialize in ways that affect IRR and time-to-market.
Core dynamics shaping 2026 strategy
-
Regulatory and payer pressure: The implementation of negotiated prices under new drug-pricing programs has begun to change the pricing baseline for outpatient pharmaceuticals. While these initial negotiations target select drugs, the precedent shifts negotiation leverage among payers and manufacturers. Separately, higher regulatory filing costs and agency fee schedules have raised the fixed-cost threshold for bringing novel dental therapeutics through a formal drug-approval route. Together, these forces raise breakeven timelines for innovation and prioritize product platforms with clear reimbursement pathways.
-
Supply chain and raw-material sensitivity: The dental drug value chain depends on specialized APIs and contract-manufacturing know-how for tasks such as cartridge filling and sterility assurance. Sourcing pressure for key anesthetic APIs and concentrated filling capacity create single-point risks that can quickly affect availability and price. Manufacturers who invest in redundant sourcing, local/nearshore capacity, or backward integration will gain negotiating leverage and stability.
-
Labor and operational specialization: Beyond chemical inputs, this segment relies on trained labor for high-precision manufacturing and clinic-level administration (e.g., cartridge handling, injectable protocols). Wage inflation and skills shortages in production and QC can materially alter unit economics and time-to-scale in emerging geographies.
-
Clinical and product mix evolution: Therapeutic demand centers on pain management, infection control, and procedural adjuncts. Local anesthetics continue to be the single-largest therapeutic category by usage; however, clinical demand for non-opioid analgesics and minimally invasive local-delivery modalities is accelerating. Product innovation is therefore a mix of formulation refinement, delivery convenience, and procedural integration.
Competitive landscape — who to watch and why
The market displays moderate concentration: the top-three companies account for a meaningful share of industry revenues, and the top-five increase that concentration modestly. This structure creates a mix of scale advantages and white-space opportunities for specialists.
-
Septodont Holding (Saint-Maur-des-Fossés, France) — a long-established leader in local and topical anesthetics with global distribution; their recent strategic investment and board participation in a development-stage analgesic specialist signals an explicit move to broaden their pipeline and accelerate injectable innovation.
-
Dentsply Sirona (Charlotte, NC, USA) — integrates pharmacologic adjuncts into broader dental workflows, creating cross-selling opportunities between devices and drug consumables; their product strategy emphasizes clinical interoperability.
-
Henry Schein (Melville, NY, USA) — a distribution powerhouse whose catalog breadth and channel reach make it a vital partner for commercial rollouts; the 2025/2026 catalog refresh expanded anesthetic assortments and demonstrates ongoing channel-led product shaping.
-
Ultradent Products, 3M, Centrix, Pierrel, Huons, Normon, and several agile specialists — each occupies distinct strategic positions: innovation-oriented formulation houses, large industrial players with adjacent oral-care portfolios, regional manufacturers with cost-advantaged production, and niche developers focused on opioid-sparing analgesics. These firms are the primary targets for bolt-on acquisitions, supply agreements, and co-development partnerships.
-
Balanced Pharma Inc. (North Carolina, USA) — a small but strategically important innovator focused on novel dental injectables and opioid-alternative analgesics; strategic backing from larger incumbents has amplified their visibility as an M&A and licensing candidate.
Recent developments with immediate strategic impact
-
Strategic investments and board realignments among incumbents and innovators are accelerating access to differentiated injectable therapies. These moves reduce technical execution risk for novel formulations and signal a near-term uptick in licensing activity.
-
Major distributors are refreshing assortments to capture higher-margin product families and to support bundled procedural offerings — a trend that increases the premium on streamlined SKUs and clinician-friendly packaging.
-
Payer and regulatory changes are shifting pricing benchmarks and increasing the importance of early health-economics evidence generation to secure formulary positioning.
What PW Consulting’s full report delivers — practical, transaction-ready content
Our objective was to produce work that is not merely descriptive but operational. The study contains granular tools you can adopt immediately to inform 2026 decisions. Highlights of deliverables include:
-
Executive dashboards with scenario-based revenue trajectories (base, upside, downside) driven by our 6.2% CAGR assumption and stress-tested for regulatory, reimbursement, and supply shocks.
-
Actionable market-entry playbooks for biologics/formulations vs. generics, including go-to-market sequencing, recommended channel partners, and targeted pricing strategies.
-
Commercial diligence templates: customer segmentation logic, salesforce sizing, list-versus-net pricing sensitivity analyses, and a retailer/distributor negotiation scorecard.
-
Regulatory-impact mapping: timeline implications of current fee and filing environments, recommended evidence packages for expedited payer conversations, and cost models for clinical programs under current agency fee structures.
-
Supply-chain risk matrix and sourcing playbook, including supplier concentration indices, contract-manufacturing scorecards, and recommended nearshoring thresholds to secure continuity for high-priority SKUs.
-
Competitive benchmarking and M&A playbook: capability heatmaps for the leading firms, valuation multiples observed in recent transactions, and a prioritized list of acquisition and partnership targets by strategic objective.
-
Customizable financial model (editable) that integrates unit economics, channel mix, and price erosion curves — built for scenario runs around payer-negotiation outcomes and manufacturing-cost shocks.
How to use this research in 2026 planning
-
Corporate strategy: Use the study’s scenario framework to test inorganic vs. organic growth at multiple price-pressure thresholds. Prioritize investments into product platforms that either protect gross margin through differentiation or materially reduce cost-per-dose via manufacturing scale.
-
Commercial teams: Leverage the go-to-market playbooks to rationalize SKUs, develop distributor partnerships, and design clinician adoption incentives tied to measurable procedural outcomes.
-
R&D and portfolio leaders: Reallocate resources to formulation advances and delivery systems that reduce clinic time, improve safety, and facilitate payer coding — all of which accelerate reimbursement and adoption.
-
Private equity and corporate development: Apply PW’s M&A playbooks and valuation sensitivities to accelerate deal sourcing and to structure earn-outs and milestone payments tied to regulatory and commercial inflection points.
What we intentionally withhold in this preview — and why
To preserve the commercial value of the study for decision-makers, we are not disclosing the full segmentation tables, region-by-region allocations, or product-level revenue splits in this preview. The full report contains proprietary market-calibration data, segment-by-segment forecasting models, and detailed price and volume assumptions that are indispensable for transaction diligence and will be made available through our report portal or consulting engagements.
Final recommendations for 2026 executives
-
Prioritize supply security and alternative sourcing for anesthetic APIs and cartridge-filling capacity; these areas represent the quickest route to stabilizing margin volatility.
-
Accelerate partnerships or minority investments in development-stage innovators that offer opioid-sparing analgesics or clinician-friendly delivery systems; these assets will be highly sought after as payers focus on outcome-based arrangements.
-
Recalibrate launch and pricing playbooks to reflect higher regulatory overhead and payer negotiation risk; embed real-world evidence generation into early commercialization plans.
-
For investors, focus on targets with defensible manufacturing footprints, strong distributor relationships, and modular product platforms that can be rapidly scaled across multiple geographies.
PW Consulting’s full Dental Drug Market report provides the data, models, and playbooks that turn these recommendations into executable programs. For access to the detailed tables, segment models, and a guided briefing with our strategy team, please visit the full report page or contact our client services desk to schedule a 2026 planning workshop.
For detailed analysis of this topic, please visit the official page: Dental Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


