



PW Consulting: Torsional Vibration Damper Market at USD 1,800M in 2025, 5.5% CAGR

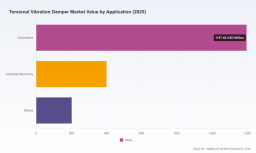
Torsional Vibration Damper Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a focused, decision-oriented briefing on the global torsional vibration damper (TVD) market. This is the executive “trailer” for our full market research: you will find rigorous frameworks, actionable implications and evidence-based directionality here — but selective numerical detail from core segment tables is intentionally withheld to preserve the urge to access the full report for definitive project-level inputs.
Torsional Vibration Damper Market
Market snapshot (base year 2025; forecast 2026–2032)
-
Historical base: our tracked period (2020–2025) shows a recovery and accelerating demand profile, with total market size rising from roughly USD 1.2 billion in 2020 to USD 1.8 billion in the 2025 base year.
Torsional Vibration Damper Market -
Outlook: the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.5% over the 2026–2032 forecast window, reaching roughly USD 2.8 billion by 2032 under the central scenario.
Torsional Vibration Damper Market -
Concentration: the market remains moderately fragmented; the three- and five-firm concentration ratios indicate that specialist OEM suppliers and integrated powertrain suppliers coexist — offering both differentiated technology and aftermarket scale. This structural profile creates opportunity for technology-driven consolidation and targeted partnerships.
Why this matters for corporate decision-making in 2026
-
R&D and product roadmaps: as internal combustion engine (ICE) architectures evolve (downsizing, higher specific torque) and hybrid powertrains proliferate, torsional dynamics become more complex. Firms must prioritize multi-mode damping solutions and material science investments now to avoid late-cycle rework.
-
Procurement and raw-material strategy: volatility in petrochemical markets has materially impacted elastomer and silicone-fluid costs. Strategic sourcing, hedging contracts, and qualification of material substitutes will determine margin resilience through 2026 and beyond.
-
Aftermarket vs. OEM playbook: aftermarket demand remains a stabilizer for suppliers facing compressed OEM pricing. Decisions on channel focus, inventory allocation and warranty exposure will affect near-term cash generation and long-term OEM leverage.
-
M&A and partnership targeting: given moderate concentration levels, bolt-on acquisitions of niche viscous or elastomer specialists — or JVs with precision spring/steel manufacturers — can buy technology differentiation faster than greenfield development.
-
Regulatory and NVH compliance: accelerating noise, vibration and harshness (NVH) and emissions certification protocols are increasing test and validation overheads. Capital allocation for testing labs and early-stage certification support is a 2026 must.
What the full report contains — practical, transaction-ready deliverables
-
Actionable market sizing and modeling: up-to-date total market and dynamic forecast models (adjustable inputs for fuel mix, global vehicle production scenarios, and aftermarket consumption) that plug directly into corporate planning tools.
-
Scenario analysis and sensitivity tables: three stress-tested scenarios (baseline, downside commodity-shock, and accelerated electrification) with P&L and working-capital impacts for supplier and OEM archetypes.
-
Supply-chain risk map: tiered supplier heatmaps, single-source dependency flags, and lead-time variability scores to prioritize dual-sourcing and qualification programs.
-
Technology readiness and IP landscape: comparative assessment of elastomeric, viscous and spring-based architectures, roadmap timing for multi-stage solutions, and inventor/portfolio mapping for M&A screening.
-
Competitive benchmarking toolkit: supplier scorecards across cost-to-produce, quality/qualification heritage, OEM presence, aftermarket channels and service capability — ready for vendor negotiations.
-
Commercial playbooks: win themes for OEM tenders, aftermarket bundling options, pricing levers and warranty covenant templates proven in recent negotiations.
-
Integration checklists for M&A and JV: operational due-diligence checklists emphasizing validation labs, test rigs, and elastomer chemistry quality systems.
Competitive landscape — who matters and why
The TVD supplier landscape combines large integrated powertrain suppliers and focused specialists. The following profiles are oriented to strategic posture rather than exhaustive corporate disclosure:
-
Vibracoustic SE — a technology leader in pressed and vulcanized elastomer and fluid dampers, with strong OEM and aftermarket channels. Recent advancements in multi-stage elastomer engineering (announced early 2026) indicate an intent to reframe multi-frequency damping for downsized, high-torque applications.
-
Vibratech TVD (Fluidampr) — renowned for viscous/fluids-based dampers and a strong presence in high-performance, off-highway and stationary-power segments. Their recent technical webinar underscores a capability to optimize viscous damping for hybridized torque profiles.
-
Schaeffler AG — pursues centrifugal-pendulum absorbers and arc-spring solutions embedded into transmissions, targeting powertrains where compactness and shift-quality are critical.
-
ZF Friedrichshafen AG — leverages dual-mass flywheel know-how to provide integrated decoupling systems with deep transmission integration expertise.
-
Continental AG — combines broad OEM access with a competitive aftermarket franchise, positioning for cross-selling NVH packages.
-
Hasse & Wrede GmbH — a global leader for viscous shear dampers in heavy-duty engines and compressors; active product introductions and system integrations for reciprocating compressors have reinforced their sectoral dominance.
-
Dayco Incorporated — aftermarket-focused, expanding severe-duty portfolios in response to specific heavy-duty engine platforms and fleet requirements.
-
American Engineering Group (AEG) , Geislinger GmbH , BorgWarner Inc. , Trelleborg AB , Valeo SA , Sumitomo Riko and LuK GmbH — each contributes distinct competencies from dual-elastomer systems to tuned steel-spring dampers and integrated driveline solutions. Collectively they shape the competitive set for OEM contract bids and aftermarket coverage.
Recent industry activity is instructive: Vibratech’s September 2025 webinar signaled heightened OEM interest in viscous solutions tailored for downsized high-torque ICEs and hybrids; Vibracoustic’s February 2026 product unveiling confirms elastomer multi-stage commercialization is accelerating; Dayco and Hasse & Wrede’s 2025 product initiatives illustrate continuing investment in severe-duty and compressor-specific applications. These moves highlight supplier strategies of product differentiation, channel expansion and vertical specialization.
Market dynamics and risk accelerators
-
Raw-material volatility: engineered elastomers and silicone-based fluids are sensitive to petrochemical price swings. Cost pass-through mechanisms are limited in OEM contracts, creating potential margin squeeze for suppliers without hedging strategies or material substitutes.
-
Regulatory tightening: NVH and emissions testing protocols are intensifying — in several mature markets regulatory testing burdens have been increasing at near-double-digit rates. This raises certification costs and extends lead times for new damper introductions.
-
OEM price pressure: sustained price-reduction programs in high-volume automotive contracts compress supplier margins; scale and differentiation are increasingly decisive competitive advantages.
-
Technology transition: electrification and hybridization change torsional-frequency spectra and torque-management requirements. While full BEV architectures reduce some damper needs, hybrid systems and high-efficiency ICEs expand demand for specialized damping — creating non-linear winners and losers by segment.
Practical 90/180/365-day actions for executives
-
90 days: run a targeted supplier risk audit (top five critical parts), initiate raw-material hedging conversations, and prioritize qualification slots for alternative elastomer suppliers.
-
180 days: field-test multi-stage prototypes with prioritized OEMs and fleet partners; mobilize aftermarket bundling pilots on two geographic platforms to stabilize aftermarket revenue.
-
365 days: execute one inorganic play (bolt-on viscous or elastomer competency) or formalize a technology JV; lock in certification roadmaps for new NVH/emissions requirements and embed test-lab investments into capital planning.
Closing provocation — what this briefing does not disclose (and why)
We have deliberately presented the strategic architecture, competitive map and operational playbooks while omitting the granular split tables that drive deal-level valuations (regional and application-specific revenue bridges, tiered margin models and segment-level unit economics). These core datasets — including fully modeled regional and application segmentation, vendor-specific revenue allocations and granular pricing matrices — are included in the full PW Consulting report and are essential for transaction diligence, sourcing RFPs and capex allocation decisions.
To convert the directional advantages outlined above into executed decisions in 2026, access to the full data pack and vendor scorecards is necessary. PW Consulting’s full TVD market study contains the downloadable models, supplier scorecards and bespoke scenario runs you will deploy in boardrooms, procurement negotiations and R&D portfolio meetings.
For an accelerated readout or to commission custom modeling keyed to your product, region or OEM portfolio, please contact PW Consulting’s industry research team via our corporate research page to obtain the full report and supporting datasets.
For detailed analysis of this topic, please visit the official page: Torsional Vibration Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


