



PW Consulting: LSA Market to Reach USD 844.73M by 2032 at 4.85% CAGR

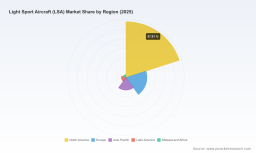
Light Sport Aircraft (LSA) Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s Light Sport Aircraft (LSA) Market study is designed as a tactical intelligence asset for corporate leaders, M&A teams, product strategists, and regulators preparing decisions in 2026. Built on a 2025 base year and calibrated to a seven‑year forecast horizon (2026–2032), the report quantifies a market that stood at approximately USD 606.25 million in 2025 and — under our baseline assumptions — is projected to grow at a compound annual growth rate (CAGR) of 4.85% toward a market size north of USD 840 million by 2032. That steady, mid‑single‑digit expansion hides a set of structural inflection points (regulatory, technological, and channel) that will determine winners and losers over the next three-to-five years.
Light Sport Aircraft (LSA) Market
Why this research matters in 2026
-
Regulation as a market multiplier: The July 2025 MOSAIC rule is not just a compliance headline — it materially reshapes product definition, certification timelines and pilot privileges. Our modelling captures both the immediate effects (pilot privileges that began Oct 22, 2025) and the later certification pathway changes that become binding in mid‑2026.
Light Sport Aircraft (LSA) Market -
Investment clarity: With a predictable baseline CAGR and visible growth levers, the study turns a broad sector narrative into prioritised investment options — platform upgrades, MRO capacity, flight training partnerships, and selective bolt‑on acquisitions.
Light Sport Aircraft (LSA) Market -
Risk prioritisation: By combining accident/trend indicators from regulatory safety reporting with supplier concentration and certification cost curves, the research produces a ranked risk register that is immediately usable in due diligence and portfolio planning.
-
Decision readiness: Executives get scenario outputs keyed to the two most consequential near‑term variables — MOSAIC uptake speed and propulsion transition (conventional vs. hybrid/electric) — enabling immediate resource allocation decisions for 2026.
What the report delivers — practical, ready‑to‑act content
-
Validated forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with downloadable time‑series in USD (Million) and adjustable assumptions for sensitivity testing.
-
Scenario suite: conservative, baseline (our published CAGR 4.85%), and accelerated adoption cases that isolate the impacts of regulatory liberalisation and propulsion disruption.
-
Competitive playbooks for OEM archetypes — product roadmap templates, certification timelines, and aftersales monetisation blueprints.
-
Operational toolkits: supplier risk heatmaps, MRO capacity models, flight school partnership scorecards, and a 100‑day integration plan for acquisitions.
-
Regulatory impact matrix aligning FAA MOSAIC implementation milestones (pilot privilege change and certification windows) with product development and production planning checkpoints.
-
Company profiles and strategic assessments of the industry’s active SLSA OEMs (technical capabilities, distribution models, certification footprints) — enough to inform outreach and negotiation strategies while preserving our proprietary market cell details.
-
Data governance appendix describing sources, reconciliation methods, and the assumptions behind our CR and concentration analysis.
Market dynamics and strategic implications
From 2020 through 2025 the market exhibited resilience: demand recovered post‑dislocation and structural drivers such as recreational flying, sport training, and niche commercial use continued to underpin revenue growth. Our baseline projects continued expansion to 2032, reflecting both organic fleet renewal and new market entries enabled by regulatory changes.
But the headline CAGR masks several vectors that will dominate strategic choices in 2026:
-
Regulatory redefinition of LSA: MOSAIC’s shift to performance‑based eligibility introduces a bifurcation — incumbents with engineering and certification capability can fast‑follow expanded product envelopes; smaller kit‑oriented OEMs face higher marginal compliance costs.
-
Certification and compliance overheads: New make/model notification, PSP obligations, and the requirement that only assigned ASIs may issue certain airworthiness certificates raise both time‑to‑market and fixed compliance costs; that favors firms with scale or with access to capital.
-
Technology trajectories: Advances in light‑weight composites, modern EFIS avionics, and alternative propulsion are creating differentiated value propositions (range, payload, operating cost) that can shift purchase economics despite modest headline growth.
-
Aftermarket economics: Because LSA adopters are highly sensitive to operating cost and training availability, monetising service, spare parts, and instruction offers elevated lifetime value. Our MRO models show attractive margins for players able to standardise platforms across dealer networks.
-
Moderate concentration, active consolidation runway: Measured concentration metrics indicate neither monopolistic control nor complete fragmentation — a market ripe for strategic roll‑ups, selective vertical integration, and dealer network aggregation.
Competitive landscape — strategic archetypes and representative players
Rather than a simple ranked list, the competitive field is best understood as a set of archetypes that map to different strategic choices in 2026:
-
Tier‑A certified OEMs with diversified portfolios and global distribution: These manufacturers combine multiple SLSA models with established dealer networks and aftermarket support. Their competitive advantage lies in certification experience and scale in production and support.
-
European composite specialists: Firms with lightweight airframe expertise and export orientation — their choice is whether to invest in expanded certification capability to capture MOSAIC‑enabled demand or to leverage licence/partnership models in target markets.
-
North American STOL and bush‑capable OEMs: Focused on niche mission profiles and flight‑training linkages, these companies can capitalise on regional training demand but must assess certification costs if they intend to broaden seating/weight envelopes.
-
Weight‑shift and ultralight producers: These players face unique regulatory transitions; some may pivot toward offering amphibious or light amphib models to capture tourism/leisure niches.
-
Legacy kit builders and small volume OEMs: Cost sensitive and relationship driven, they must weigh the economics of compliance against pivoting to experimental or LSA markets.
Representative names in the field span established Western OEMs, agile European designers, and specialised manufacturers across amphibious, weight‑shift, and STOL segments. Each grouping has a differentiated response set to the 2026 regulatory and market environment: deepen certification capability, pursue alliances for propulsion supply, or double down on aftermarket capture.
MOSAIC as catalyst — a tactical checklist for 2026
-
Re‑baseline product roadmaps against the MOSAIC performance definition; identify which platforms can plausibly be upgraded to capture the new envelope.
-
Develop a certification timetable that aligns engineering milestones with the FAA’s July 24, 2026 certification window for new performance‑based LSA criteria; incorporate notification requirements to the relevant FAA authorities early in the design cycle.
-
Update Partnership for Safety Plan (PSP) commitments and internal safety governance to reduce risk exposure highlighted in regulatory safety reports.
-
Secure supply continuity for critical systems (engines, propellers, avionics) via multi‑year contracts or distributor partnerships to avoid bottlenecks as production scales.
-
Design a go‑to‑market that integrates flight‑training programmes and dealer aftercare, converting first‑time buyers into a recurring‑revenue base.
Investment and M&A thesis for 2026
With steady market growth backed by a clear regulatory inflection, the most compelling investment stories in 2026 are not necessarily large platform buys but targeted acquisitions that deliver capability: certification expertise, established MRO capacity, flight school networks, or propulsion supply. Given the market’s measured concentration, the financial rationale is attractive for buyers seeking scale benefits in procurement and higher margins in aftermarket services.
Key risk vectors to underwrite in any transaction: regulatory compliance backlog, accident and insurance trend exposure (as captured in safety reports), and supplier concentration for engines and avionics. Our valuation matrices and integration playbooks are structured to convert those risks into negotiable adjustments rather than transaction blockers.
How to use this study in your 2026 planning cycle
-
Embed the baseline and scenario outputs into your FY‑26 capital allocation and product prioritisation processes.
-
Run the MOSAIC upside case for any platform you consider expanding — the delta analysis will determine where certification investment yields top‑quartile returns.
-
Apply our supplier risk heatmaps to procurement negotiations and working capital plans to protect production ramp timelines.
-
Use the M&A toolkit to screen targets and accelerate 100‑day integration planning for bolt‑on acquisitions that expand MRO and training reach.
PW Consulting’s LSA Market report is intentionally constructed as a decision‑ready toolkit: it shows the analytical mechanics behind our headline growth estimate (2025 base, 4.85% CAGR) and provides actionable frameworks while retaining the core cell‑level segmentation and proprietary competitor scoring behind a gated dataset. If your team is preparing product investments, certification plans, or M&A activity in 2026, this study supplies the scenario logic, regulatory playbook, and commercial templates needed to act with conviction.
To access the full dataset, granular segmentation tables, and the company‑level financial models that underpin these conclusions, please refer to the full report page or contact PW Consulting for a briefing.
For detailed analysis of this topic, please visit the official page: Light Sport Aircraft (LSA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


