



PW Consulting: Reverse Transcriptase Market to reach USD 1,659.9M in 2026 at 6.69% CAGR

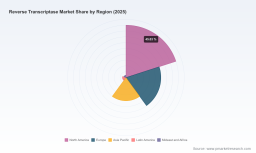
Reverse Transcriptase Market — Strategic Briefing for 2026 Decision Makers
As life-science buyers, product leaders and corporate strategists set budgets and allocate R&D priorities for 2026, the Reverse Transcriptase market presents both a predictable growth runway and a set of breaking inflection points. PW Consulting’s latest market study, anchored on a 2025 base year and forecasting through 2032, synthesizes hard market-sizing (the global market grew from USD 1,102.5 Million in 2020 to USD 1,530.0 Million in 2025) with scenario-led insights. The model projects a continued expansion into the forecast window (the market is forecast to reach USD 1,659.9 Million in 2026 and USD 2,408.5 Million by 2032) at a compound annual growth rate of 6.69% over 2026–2032.
Reverse Transcriptase Market
Why this matters for 2026 decisions
-
Budgeting and portfolio prioritization: The market’s steady CAGR and the step-change in absolute size between 2025 and the early forecast years create a predictable base for multi-year capex and manufacturing planning. Firms that align capacity with the early part of the 2026–2028 growth curve can lock-in scale advantages and shorten time-to-revenue for incremental enzyme launches and integrated kits.
Reverse Transcriptase Market -
M&A and partnership timing: With a concentrated supplier landscape (CR3 ~65%, CR5 ~75%), mid-sized innovators face clear barriers to scale. 2026 is a window for targeted bolt-on acquisitions that deliver product differentiation—enzyme engineering, improved thermostability, or integrated workflow compatibility—without competing directly on commodity pricing.
Reverse Transcriptase Market -
Commercial channel and differentiation: The market expansion is occurring alongside faster adoption of RNA-centric workflows, decentralized molecular diagnostics and higher-throughput sequencing. Vendors that offer validated end‑to‑end workflows (enzyme + buffer chemistry + support documentation) will capture disproportionate share in tender-driven institutional channels in 2026.
Market evolution — key quantitative signals (high-level)
-
Scale and momentum: The market more than doubled in size across the 2020–2032 window in absolute terms. The 2025 base provides a robust starting point for ROI modeling, and the first forecast year (2026) shows measurable uplift as new diagnostic programs and research investments come online.
-
Concentration and competitive dynamics: The market concentration metrics indicate that a small number of global players command the majority of commercial volumes. That creates favorable economics for incumbents but also a structural opportunity for challengers that can deliver differentiated performance or cost-to-serve advantages.
-
Volatility vectors: Pricing pressure in mature procurement channels, supply-chain fragility for cold-chain biologicals, and accelerating regulatory scrutiny around molecular diagnostic components are the primary risk levers that could compress near-term margins if not proactively hedged.
Practical contents of the PW Consulting report
The study is designed as a pragmatic decision tool for commercial and corporate leadership. It includes:
-
A transparent market model with historicals (2020–2025) and an integrated forecast (2026–2032) that can be re-run with alternate macro assumptions and input parameters.
-
Scenario analysis (three tiers) that quantifies outcome ranges under differing adoption curves for molecular diagnostics, sequencing demand, and RNA therapeutics R&D spend.
-
Go-to-market playbooks for six strategic moves: premium product differentiation, cost leadership at scale, channel reconfiguration, regional market entry, M&A playbook, and contract-manufacturing partnerships.
-
Operational toolkits: SKU rationalization templates, manufacturing capacity planning matrices, and a supply‑chain resilience checklist mapped to typical biological reagent constraints.
-
Commercial KPIs and scorecards used to benchmark product launches, tender success rates, and partner performance—structured so internal teams can plug in corporate-level targets and obtain actionable gap analyses.
Competitive landscape — profiles and strategic postures
Our competitive analysis focuses on the vendors that shape product expectations and procurement decisions in reverse transcriptase supply chains. Below is a high-level characterization of each firm’s strategic posture (detailed vendor scorecards and validated capability matrices are available in the full report).
-
New England Biolabs (Ipswich, MA, USA) : Known for a technical-first product portfolio emphasizing enzyme innovation, NEB’s strengths are in reagent performance claims, robust application notes and developer community engagement. Their play is defense through technical differentiation and community adoption.
-
Thermo Fisher Scientific (Waltham, MA, USA) : Thermo Fisher leverages broad channel reach and integrated workflow offerings—tying enzyme products into end-to-end solutions for high-throughput labs and diagnostic manufacturers. Expect them to push bundled solutions and leverage global service capabilities.
-
QIAGEN (Hilden, Germany) : QIAGEN positions itself where molecular diagnostics and sample-to-answer workflows converge. Their competitive edge lies in validated kits and regulatory know-how, making them a preferred partner for clinical-lab customers and regulated diagnostic OEMs.
-
Merck KGaA (Darmstadt, Germany) : Merck’s advantage is breadth—suited to customers seeking supply reliability and broad reagent portfolios. They play the scale card and are a logical supplier for multi-site labs or contract manufacturers prioritizing continuity and certification.
-
Promega Corporation (Madison, WI, USA) : Promega is recognized for assay development support and application-driven reagents. Their go-to-market is often collaborative, helping customers co-develop assays and thus locking in product use through application dependence.
-
Takarabio (Takara Bio, Otsu, Japan) : Takara’s strengths are in enzyme engineering and market segments that require high-fidelity or specialty reverse transcriptases. Their route to growth in 2026 will be through targeted partnerships and niche clinical applications.
Strategic plays we see winning in 2026
-
Move from component selling to workflow selling. Vendors that convert single‑sku enzyme sales into validated, documented workflows (reagents + protocols + technical support) secure higher margins and stickier revenue streams.
-
Pursue modular scale-up via CMO partnerships. For firms without excess biologics capacity, partnering with qualified CMOs for fill/finish and cold-chain logistics reduces capital intensity while preserving speed to market.
-
Embed regulatory and clinical evidence into product launches. Products launched with pre-validated claims and clear regulatory pathways (e.g., companion diagnostic compatibility) accelerate procurement cycles in clinical settings.
-
Use targeted M&A to fill capability gaps. Small to mid-sized enzyme developers with novel chemistries are attractive acquisition targets for incumbents that need differentiation without developing in-house capabilities over many quarters.
Risk management and operational readiness
Our analysis highlights three operational risks that require attention in 2026 planning cycles: (1) supply-chain concentration for bespoke reagents and packaging materials; (2) margin compression driven by tender-led pricing dynamics in larger institutional channels; and (3) faster regulatory expectations for traceability and quality systems. The report includes a supplier-risk heatmap, working-capital scenarios, and a price-elasticity framework to quantify the likely impact of each risk on EBITDA under alternate adoption cases.
How to translate these insights into action
For corporate strategy teams: incorporate the PW Consulting market model into your 2026 financial plan to test acquisition payback periods under optimistic and conservative adoption curves. For commercial leaders: adopt the workflow-selling playbook and pilot a bundled-offer in two high-opportunity accounts in H1–2026. For R&D leaders: prioritize enzyme features that reduce total assay cost and shorten warm-up times—these attributes are repeatedly cited by procurement and lab managers as escalation factors during vendor selection.
Accessing the withheld intelligence
This briefing intentionally omits granular sub-segment tables and procurement-level pricing matrices to preserve the value of the complete study. The full PW Consulting Reverse Transcriptase Market report contains the segment-level demand model, region-by-application dynamics, detailed vendor scorecards, and template transaction models (including synergies and due-diligence checklists) that are essential for execution in 2026. Visit our report page to obtain the full dataset, interactive model, and a customized briefing with our lead analysts.
For detailed analysis of this topic, please visit the official page: Reverse Transcriptase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


