



PW Consulting: Engineered Quartz Stone Market to Reach $195.16M by 2032 at 7.12% CAGR

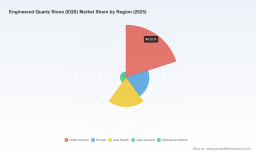
Engineered Quartz Stone (EQS) Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-oriented introduction to our full Engineered Quartz Stone (EQS) Market study. Between 2020 and 2025 the global EQS market advanced steadily; our base-year calibration for 2025 places market revenues at USD 120.0 million (USD Million unit). Under the scenarios modeled in the full study, EQS is set to expand through the 2026–2032 forecast horizon at a compound annual growth rate of 7.12%, reaching roughly USD 195.2 million by 2032. These macro dynamics create a window of strategic choices in 2026 for manufacturers, fabricators, distributors, and investors.
Engineered Quartz Stone (EQS) Market
Why this study matters for 2026 planning
-
Actionable horizon: 2026 is the inflection period where demand growth, regulatory tightening, and portfolio-level capital allocation converge. Our study translates market momentum and regulatory trajectories into near-term capacity and product decisions that materially affect next‑cycle returns.
Engineered Quartz Stone (EQS) Market -
Risk-aware positioning: the sector faces asymmetric regulatory and health-risk exposures. The report equips executives to prioritize interventions — from product reformulation to new fabrication practices — that preserve market access and worker safety while protecting margins.
Engineered Quartz Stone (EQS) Market -
Opportunity mapping: rising demand for high-performance surfaces and premium finishes remains the demand engine. The study identifies the product and route-to-market strategies that capture premiumization without overexposing firms to volatile raw-material or labor cost swings.
Market dynamics distilled
At the macro level, EQS is a growth market: a clear recovery trajectory from 2020 through 2025 and a robust outlook into 2032. Momentum is driven by residential renovation, commercial fit-outs, and a continued premiumization of interior finishes. That said, growth is neither uniform nor risk-free; it is shaped by three structural factors that every 2026 plan must address:
-
Regulatory regime shifts — Worker safety rules on crystalline silica have moved from guidance to enforcement. Several jurisdictions have tightened limits or enacted outright prohibitions on certain engineered stone activities. This changes capital planning for fabrication plants, increases compliance costs, and accelerates demand for low‑silica formulations and enclosed, dust‑free fabrication systems.
-
Input-cost volatility — Polyester resins, pigments, and mined quartz feedstock show price swings that compress margins for non-integrated producers. Labor cost and availability in fabrication remain a sensitive margin lever, especially where regulatory compliance requires new controls or tooling.
-
Competitive fragmentation with consolidation potential — The market exhibits a middle degree of concentration. Strong global brands coexist with numerous regional players; capacity expansions and strategic product launches indicate consolidation and scale-seeking behavior among incumbents.
Competitive landscape — who matters and why
Our analysis covers global leaders and influential regional players. Key strategic takeaways for 2026 planning:
-
Cambria (United States) — A family-owned, American-made brand with a premium positioning and lifetime warranty program. Strengths: brand equity and a high-performance slab portfolio. Strategic implications: Cambria’s model shows the premium warranty-plus-brand route can sustain higher price points but requires tightly managed distribution and fabrication partnerships.
-
MSI Surfaces (United States) — A broad-style, scale-oriented player with advanced manufacturing and multiple collections. Strengths: breadth of SKUs and manufacturing scale. Strategic implications: MSI illustrates how SKU breadth and in‑market inventory support accelerate distribution wins but demand efficient SKU rationalization to protect margins.
-
VICOSTONE (Turkey) — Premium product focus with extensive collections. Strengths: design-led innovation and export orientation. Strategic implications: product differentiation through design and finish remains a resilient pathway to margin uplift.
-
Caesarstone (Israel) — A pioneer with sustained innovation in sustainability and low-silica technology. Recent capacity increases and a low-crystalline silica product launch demonstrate a proactive compliance-and-premium strategy. Strategic implications: investing early in safer formulations and flexible capacity pays off where regulation tightens.
-
Cosentino Group (Spain) — A global leader advancing hybrid technologies to reduce crystalline silica content. Strengths: R&D, brand scale, and technology transfer across regions. Strategic implications: technology-led differentiation can create durable competitive advantage if coupled with disciplined cost control.
-
Hanwha L&C (HanStone Quartz) & LG Hausys (Viatera) — South Korean engineering and brand know-how leveraged through localized manufacturing. Strategic implications: coupling global designs with local manufacturing reduces lead times and supports spec-driven projects.
-
Regional manufacturers (e.g., Techstone, LT Quartz and others) — Competitive on price and regional distribution. Strategic implications: these players are attractive targets for consolidation by western brands seeking capacity or faster route‑to‑market in key export corridors.
Recent industry moves that change the 2026 playbook
-
Capacity investments by leading suppliers underscore confidence in medium-term demand — but also signal intensifying competition for skilled fabricators and distribution shelf space.
-
Product launches that lower crystalline silica content shift the trade-off between regulatory compliance and performance. Early adopters gain first-mover advantage in regulated jurisdictions.
-
Regulatory actions (notably jurisdictional bans and tightened workplace silica standards) are creating asymmetric market access. Firms that align R&D and fabrication processes with these rules avoid market disruption; those that do not face either exit or expensive retrofits.
Strategic imperatives for 2026 (operational and corporate)
-
De-risk capacity and supply: Evaluate near-term incremental capacity versus brownfield upgrades. Prioritize investments that enable low-dust fabrication and faster SKU changeover.
-
Product and process innovation: Fast-track formulations and process controls that reduce crystalline silica exposure. Consider selective licensing or partnerships with technology leaders to compress development timelines.
-
Vertical choices: Assess backward integration into resin and quartz supply or forward integration into prefabricated countertops to capture greater margin and quality control.
-
Regulatory hedging: Build regulatory scenario playbooks (base, tightening, ban) and quantify the P&L and capex impact on each. Where feasible, preemptively adopt higher safety standards to protect workforce and brand.
-
M&A and partnerships: Use bolt-on acquisitions to buy fabrication capacity, distribution reach, or low-silica technology. Target transactions where integration can be executed within 12–18 months to capture synergies early.
-
Commercial strategy: Differentiate through warranty design, installation quality assurance, and downstream service offerings such as measured prefabrication programs that reduce site work.
What the full PW Consulting EQS report delivers (practical contents)
Our full study is structured to convert intelligence into executable 2026 initiatives. Highlights include:
-
Top-down market sizing (2020–2025 historical; 2026–2032 forecast) and demand-driver decomposition with sensitivity to construction activity and renovation cycles.
-
Detailed supplier and fabricator mapping, including production capacities, product portfolios, and manufacturing footprints.
-
Regulatory risk matrix with jurisdiction-level scenarios and quantified operational, capex, and compliance cost impacts.
-
Unit-cost and margin models with break-even analysis for new product introductions and low‑silica reformulations.
-
Go-to-market playbooks for expansion, including channel economics, pricing ladders, and distributor incentive structures.
-
M&A playbook and target shortlist methodology, plus modelled case studies illustrating integration timelines and synergy capture.
-
Actionable implementation roadmaps for OEMs, large fabricators, distributors, and investors — prioritized by ROI and execution complexity.
Note: In line with our “trailer” principle, this briefing highlights the strategic contours and omits the granular regional and application split tables, proprietary unit-cost schedules, and full company segment revenue breakdowns. These are accessible in the full report and dataset.
How to use this intelligence in 90–180 days
-
Immediate (30–90 days): Run a regulatory-impact quick-scan on your major fabrication sites; prioritize capital allocation for dust-control retrofits and deploy a SKU rationalization exercise to identify low-contribution SKUs.
-
Near-term (90–180 days): Execute supplier agreements to hedge resin and pigment exposure; pilot low‑silica product lines with select trade partners; and shortlist regional M&A targets if scale or channel access is a priority.
-
Board-level: Use our scenario P&L projections to reset risk-adjusted returns on current and proposed capital projects; adopt the recommended reporting cadence for regulatory and safety KPIs.
Final counsel — what success looks like in 2026
Winning in EQS in 2026 requires combining three capabilities: disciplined capital allocation that favors regulatory-resilient projects, rapid product adaptation toward lower-risk formulations, and commercial models that translate premium product features into durable margin. Companies that invest early in worker-safety technology, product reformulation, and controlled fabrication stand to outcompete peers when regulation intensifies or raw-material volatility re‑emerges.
Next steps
-
Request the full PW Consulting EQS Market Report and dataset to access the segmented tables, jurisdictional regulatory models, company-level revenue splits, and our recommended transaction targets.
-
Contact PW Consulting for a tailored 90-day implementation plan that aligns your capital and commercial priorities with the scenarios most relevant to your portfolio.
For detailed analysis of this topic, please visit the official page: Engineered Quartz Stone (EQS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


