



PW Consulting: Mercury Removal Adsorbents Market to Hit USD 2,370.9 Million by 2032 at 6.2% CAGR

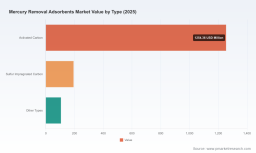
Mercury Removal Adsorbents Market: Strategic Imperatives for 2026 — PW Consulting Preview
As companies calibrate their 2026 investment plans in gas treatment, refining, and industrial emissions control, the Mercury Removal Adsorbents Market demands strategic clarity. Our PW Consulting market study — base year 2025, forecast through 2032 — shows the sector transitioning from compliance-driven deployments into an increasingly efficiency- and lifecycle-cost-driven buyer’s market. With a steady compound annual growth rate of 6.2% projected over the forecast horizon, total market value rises materially from the 2025 baseline into 2032, creating both predictable demand and differentiated value capture opportunities for incumbents and newcomers alike.
Mercury Removal Adsorbents Market
Why this study matters for 2026 decision cycles
-
Translating regulatory imperatives into commercial plans: Many operators will be making final investment decisions in 2026 on mercury control technology selections, vendor partnerships, and longer-term service contracts. Our analysis converts upcoming regulatory and cost pressures into actionable procurement and capital-allocation scenarios.
Mercury Removal Adsorbents Market -
Unit-economics focus for procurement teams: Beyond headline technology claims, the decisive factors in 2026 will be lifecycle cost, disposal and handling fees, and operability across hydrocarbon and wet gas streams. This report models those drivers so procurement teams can compare vendor total-cost-of-ownership (TCO) outcomes, not just up-front metrics.
Mercury Removal Adsorbents Market -
Portfolio strategy for suppliers and investors: With mid-single-digit CAGR and a market size that meaningfully expands from the 2025 base to 2032, suppliers must choose between scale-based plays (volume, distribution) and differentiation (regenerable adsorbents, integrated service packages). For private equity and corporate development teams, we map where premium margins and defensibility are likely to emerge.
Market trajectory and what the headline numbers mean
The market trajectory shows steady expansion emanating from growing gas processing, LNG, and refining activity, coupled with tightening environmental requirements. From the 2025 baseline, our forecasts show a predictable climb through 2032 underpinned by a 6.2% CAGR — a profile that rewards disciplined scale plays, but only where suppliers can mitigate rising disposal and raw-material costs. Put simply: this is a growth market, but cost and regulatory friction will determine who captures margin.
Key dynamics shaping 2026 strategy
-
Regulatory and compliance pressure: Operators are anticipating stricter mercury limits in many jurisdictions. That certainty accelerates demand for validated, field-proven technologies — yet it also raises lifecycle and disposal scrutiny.
-
Disposal and lifecycle costs as first-order economics: Spent-adsorbent disposal is an under-appreciated but material line item. Industry benchmarking indicates disposal costs can range significantly per ton, making spent-media handling and regeneration economics central to investment cases. Procurement teams must incorporate realistic disposal scenarios into their TCO models.
-
Premium for advanced solutions: Advanced mercury removal solutions—particularly regenerable and mixed-metal materials—trade at a meaningful premium versus conventional activated carbon. Expect costs for some advanced products to exceed traditional carbon by a notable margin, even as operators weigh this against reduced waste volumes and longer on-stream life.
-
Raw-material and manufacturing constraints: Feedstock costs and specialized manufacturing steps for impregnated carbons and metal-sulfide products can restrict supply responsiveness. Suppliers with flexible production footprints or upstream integration will have an advantage during 2026 demand spikes.
-
Shift in chemistry mix: There is a clear movement toward selenium- and sulfur-based chemistries as suppliers seek better capacity, selectivity, and sustainability profiles. Technology selection is increasingly a trade-off among capacity, regenerability, and secondary waste complexity.
Competitive landscape — strategic profiles (what to watch in 2026)
The market remains fragmented with a modest top-three concentration, which keeps competitive intensity high and creates pockets of opportunity for specialization. Below we distill the strategic positions of the leading providers and the implications for buyers, partners and acquirers.
-
Calgon Carbon Corporation (Pittsburgh, PA) — Known for sulfur-impregnated granular and powdered activated carbons (HGR, Fluepac, HGR-P) that address mercury across natural gas, flue gas and process streams. Their strength is in traditional carbon expertise combined with tailored formulations; buyers benefit from deep application experience and established distribution.
-
UOP (Honeywell) (Des Plaines, IL) — Offers both non-regenerative metal sulfide adsorbents (GB series) and regenerable molecular sieve solutions (HgSIV). Their proposition is performance at scale and integration into plant-level process units — attractive where buyers require system-level guarantees and engineering support.
-
Johnson Matthey (London, UK) — PURASPEC™ mixed metal sulfide absorbents are positioned for complete mercury sequestration across gas and liquid phases. Their differentiator is metallurgy and chemistry know-how that supports high-capacity duty cycles.
-
Cabot Corporation (Boston, MA) — DARCO® Hg powdered activated carbon products target flue gas applications; strong in high-volume, commodity-like deployments and in retrofit markets where rapid supply response matters.
-
Pall Corporation (Port Washington, NY) — Focuses on systemized solutions for natural gas, offering both non-regenerative and regenerative adsorbent systems. Their edge is system integration, after-sales service and performance guarantees.
-
Nucon International Inc. (Columbus, OH) — MERSORB® impregnated carbons cover air, gas and liquids; they often compete on customized media formulations and fast-turn prototyping for plant trials.
-
Axens (Rueil-Malmaison, France) — AxTrap™ 200 series provides ready-to-use adsorbents aimed at hydrocarbon streams with safe air-loading capability. Their route-to-market is engineered product plus licensing/turnkey deliverables.
-
BASF SE (Ludwigshafen, Germany) — Durasorb® HG mixed metal oxide adsorbents are designed for wet-condition natural gas streams. Their global scale and R&D muscle back offerings where complex feed conditions exist.
-
SLB (Schlumberger) (Houston, TX) — SELECT Hg mixed-metal sulfide adsorbents emphasize crude, condensate and LNG duty cycles, tying adsorbent supply to broader reservoir and processing services.
Strategic implications for buyers, suppliers and investors
-
Buyers should shift from capex-centric decisions to lifecycle procurement: In 2026, procurement must demand full TCO scenarios that include sampling, trial run data, spent-media handling and disposal/regeneration modeling. Contracts should include performance SLAs, warranty clauses addressing multi-phase feeds, and transparent disposal pathways.
-
Suppliers must defend margin through services and circularity: Given disposal economics and premium pricing for advanced chemistries, companies that combine adsorbent sales with regeneration services, logistics, or on-site swapping will expand margin pools.
-
M&A and partnerships will favor technology-plus-service models: Fragmentation and mid-single-digit growth create impetus for bolt-on acquisitions that add regenerable technology, regional logistics, or hazardous-waste management capabilities. Strategic buyers will prioritize assets that improve product lifecycle economics.
-
R&D should target cost-to-per-kg-of-mercury captured: Incremental gains in capacity and regenerability reduce lifecycle cost more than incremental improvements in initial adsorption rates. Expect R&D ROI models to prioritize downstream handling and recyclability.
-
Regulators and sustainability teams will be part of procurement committees: Disposal cost variability and evolving chemistry preferences mean that sustainability and compliance teams must be looped into vendor evaluations early.
Recommended near-term actions for 2026 planning
-
Commission field trials that emulate your worst-case feed conditions, not just idealized lab runs. Validate capacity, pressure-drop behavior, and spent-media profiles to avoid surprise disposal costs.
-
Require vendor TCO models that include disposal/regeneration scenarios with differentiated pricing bands. Stress-test contracts for feed variability and moisture-content sensitivity.
-
Explore strategic partnerships with specialist hazardous-waste handlers or invest in on-site regeneration pilots to insulate against disposal-cost volatility.
-
Prioritize suppliers offering engineering support and system guarantees when deploying at scale — the incremental premium can be offset by operational uptime and compliance risk reduction.
-
For investors, target assets that combine proprietary chemistry with service delivery or regional logistics — these playbooks offer higher barriers to entry and steadier cash flows.
What the full PW Consulting report delivers (practical, executable content)
-
A dynamic market model (2020–2032) that links demand drivers to a scenario-based revenue outlook, enabling sensitivity analysis across regulatory, price and feed-condition variables.
-
Vendor benchmarking that scores suppliers across chemistry, regenerability, service suite, geographic reach and proof points — designed for procurement shortlists and RFPs.
-
Detailed TCO and disposal-cost templates you can drop into capital approval workflows, with modular inputs for feed variability, service frequency and waste-treatment options.
-
Commercial playbooks for suppliers: go-to-market segmentation, pricing strategies, and partnership/bolt-on acquisition targets to build defensibility and margin capture.
-
Regulatory-impact maps and compliance timelines that translate regional policy changes into capital and operational milestones for 2026 planning.
Conclusion — how to use this preview in 2026
For executives preparing 2026 budgets and strategic roadmaps, the Mercury Removal Adsorbents Market represents a growth arena with clear winners and losers. The overall expansion — driven by steady demand and evolving chemistry choices — rewards those who treat adsorbent selection as a lifecycle decision rather than a commodity buy. PW Consulting’s full study provides the granular diagnostics, vendor scorecards and executable TCO tools needed to convert market growth into durable profitability. To move from overview to execution, companies should prioritize lifecycle pilots, contractual protections, and service-integrated business models in the coming 12 months.
For access to the full methodology, granular segmentation, vendor profiles, and downloadable TCO templates, consult our complete report and client portal. PW Consulting’s team stands ready to support tailored workshops and scenario modeling to align your 2026 capital and procurement decisions with the market realities outlined here.
For detailed analysis of this topic, please visit the official page: Mercury Removal Adsorbents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


