



Coal Tar Pitch Market: 4.85% CAGR to 2032 - PW Consulting

Coal Tar Pitch Market 2026: Strategic Preview for Corporate Decision-Makers
As PW Consulting releases its comprehensive Coal Tar Pitch Market study, this preview outlines the research’s strategic value for executive teams planning through 2026 and beyond. The market has exhibited steady recovery and structural transformation across 2020–2025, and our modelling—anchored to a 2025 base year—projects a continuation of moderate expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 4.85% (USD, revenue unit: Million). The market size rose from USD 1,765.2 Million in 2020 to USD 2,185.5 Million in 2025, and is forecast to reach roughly USD 3,044.1 Million by 2032. This brief synthesizes the commercial levers, regulatory stress points, and competitor dynamics that should shape near-term capital, procurement, and portfolio decisions.
Coal Tar Pitch Market
Why this study matters for 2026 decision cycles
- Actionable foresight: The study converts macro momentum (historical 2020–2025 trends and 2026–2032 scenarios) into near-term decision rules—when to commit CAPEX, how to structure offtake agreements, and which grades to prioritize under tightening environmental norms.
- Risk-calibrated planning: We map scenario outcomes across feedstock volatility, PAH regulatory tightening, and end-market substitution to generate board-level risk envelopes for revenue, margin and supply security in 2026.
- Competitive positioning: With the market demonstrating measurable concentration (CR3 ≈ 58.4%; CR5 ≈ 72.3%), the report isolates value pools where mid-sized players can outflank integrated incumbents through grade specialization, logistics corridors, or low-PAH product differentiation.
High-level market trajectory
Following a period of uneven recovery and feedstock pressure in 2020–2025, the industry is transitioning to growth underpinned by steady demand in traditional aluminum smelting and graphite/ electrode applications, partially offset by regulatory-driven substitution and end-use changes. Our base-year benchmarking (2025) and scenario suite show a baseline path consistent with a 4.85% CAGR through 2032; however, downside and upside pathways diverge materially depending on regulatory intensity and availability of coal tar feedstock tied to broader steelmaking trends.
Coal Tar Pitch Market
Core dynamics shaping 2026 strategy
- Feedstock availability and price transmission: Continued shifts toward electric-arc-furnace (EAF) steelmaking reduce available coal tar volume from integrated coke/steel flows, creating episodic supply tightness and spot price volatility. Buyers need to model multi-year supply curves, not just annual spot exposure.
- Regulatory tightening on PAHs: Jurisdictional bans and stricter PAH limits (examples include long-standing state-level actions and evolving EU REACH requirements) are raising compliance costs for legacy grades and accelerating demand for low-PAH formulations and alternative binders in certain applications.
- Concentration and strategic capacity moves: A small group of global integrated producers holds a substantial share of the market. Recent greenfield and expansion investments by industry players indicate targeted growth in capacity and new supply corridors, which will influence regional price spreads and long-term contract terms.
- End-market substitution risk: Roofing, refractory and other industrial segments show selective substitution pressure where regulatory or performance-based alternatives are viable; aluminum and graphite electrode demand remains the dominant structural driver but is itself sensitive to the anode and electrode technology roadmaps.
Competitive landscape: who matters and why
The study profiles the leading producers and their strategic postures—capability, geographic footprint, product portfolio and integration level—spotlighting their implications for buyers, investors and potential acquirers. Representative players covered include:
Coal Tar Pitch Market
- Koppers Holdings Inc. (Pittsburgh, USA) — an integrated carbon-pitch producer serving binding and electrode markets; positioned to leverage downstream relationships with aluminum and EAF steel customers.
- Rain Carbon Inc. (Stamford, USA) — global distillation and pitch specialist; recent capacity investments are explicitly aimed at graphite/battery and aluminum applications.
- Himadri Speciality Chemical Ltd. (Kolkata, India) — vertically integrated with large-scale capacity and growing export corridors; well placed to serve both regional and international demand.
- Deza, a.s. (Czech Republic) — focused on binder-grade and impregnating grades for specialty carbon applications, with a European regulatory and trade perspective.
- Shree Shyam Chemicals (Bhilai, India) — industrial-grade supplier with relevance to regional smelting and carbon industries.
Recent corporate moves documented in our dataset are instructive for 2026 strategy: Rain Carbon announced a greenfield distillation and pitch processing facility in Andhra Pradesh (early 2025 phase), signaling competitive expansion into battery/graphite and aluminum supply chains; Himadri executed an inaugural liquid pitch export corridor from a major Indian port (late 2025); and there are emerging long-term supply dialogues between regional suppliers and large aluminum producers. These actions presage tightening in specific corridors even as global capacity grows incrementally.
Regulatory and ESG risk matrix
- Regional bans and proposed legislation on coal-tar-based pavement products (e.g., established state-level prohibitions and proposed bills) create product-level demand displacement for specific grades—requiring compliance roadmaps and product rationalization.
- EU REACH and similar frameworks are elevating testing, labelling and wastewater compliance costs for legacy high-PAH products; capital investments in emission controls or grade reformulation will alter unit economics and supplier competitiveness.
- Proactive low-PAH product development is both a compliance and commercial lever: firms that can certify lower PAH envelopes can protect existing markets and open procurement channels in stricter jurisdictions.
What the full report delivers (practical contents)
- Supply-demand model (2020–2032) with scenario toggles for feedstock availability, steel production mix, and PAH regulation intensity. Note: detailed regional and application splits are available in the full report.
- Price-formation framework and a three-tier price forecast (base, upside, downside) tied to spot/trade differentials, logistics arbitrage and contract mix.
- Plant-level breakeven and CAPEX/OPEX benchmarks for greenfield and brownfield projects, including sensitivity to emission-control investments and low-PAH processing.
- Trade-flow mapping and logistics corridor analysis highlighting emerging export windows (notably between South Asia, the Middle East and select export hubs) and potential chokepoints.
- Supplier heatmaps and counterparty risk scoring for all major producers and a set of mid-tier regional suppliers, with recommended contractual templates and mitigation clauses for 2026 contracting cycles.
- M&A and partnership playbook: value drivers, typical multiples, integration risks, and buyer-seller negotiation levers specific to coal tar pitch assets.
- Regulatory compliance playbook and ESG upgrade pathways for low-PAH product strategies, including likely timelines and capex phasing.
Recommended 90-day and 12-month actions for 2026
- 90-day: Conduct a supply-security audit prioritizing critical grades and logistics corridors; secure at least two medium-term offtake options (one integrated supplier, one regional producer) with staggered delivery windows to mitigate feedstock shocks.
- 90-day: Commission a rapid compliance gap analysis against target jurisdictional PAH limits and quantify capex needed for grade reformulation or end-of-pipe controls.
- 12-month: Re-evaluate capital projects using plant-level breakeven thresholds from the report; defer or accelerate Greenfield CAPEX depending on the preferred scenario (tight supply vs. moderated growth).
- 12-month: Pursue strategic JVs or toll-processing agreements in export corridors shown to narrow logistics spreads—this is a lower-capex route to secure access to low-PAH and liquid pitch supplies.
- 12-month: Build price pass-through mechanisms into customer contracts where regulatory compliance costs are material and quantifiable.
How PW Consulting’s report supports your 2026 strategy
This study translates the macro-path—historical data for 2020–2025 and a 2026–2032 forecast anchored to a 2025 base year—into decision-grade intelligence. It combines bottom-up plant economics, top-down demand forecasting (consistent with the 4.85% CAGR baseline), and qualitative scenario narratives tied to regulatory and feedstock shocks. The result: a compact set of executable options for procurement, operations, investment, and M&A teams that are calibrated to 2026 planning cycles.
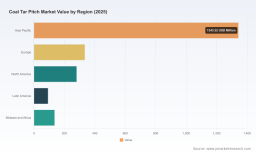
Note: this preview intentionally omits the granular regional and application split tables and some proprietary segmentation metrics to preserve the “trailer” framing. These detailed splits, along with downloadable models, supplier dossiers, and contract templates, are available in the full report on our website.
Next steps
- For procurement and supply-chain teams: request the supply-side model and corridor maps to simulate sourcing scenarios.
- For corporate strategy and M&A teams: commission a targeted diligence pack on specific assets or regions identified in this preview.
- For ESG and compliance leads: obtain the regulatory-costing annex to quantify upgrade pathways for low-PAH grades under alternative regulatory scenarios.
PW Consulting’s Coal Tar Pitch Market report is designed to be a decision-enabler for 2026—equipping leadership with the scenarios, trade-offs and tactical playbooks required to navigate a market that is modestly growing but materially reshaping along regulatory, feedstock and supply-chain lines.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


