



PW Consulting: FeSi Powder Market to Reach USD 2,193.6 Million by 2032 at 5.2% CAGR

Fesi Powder Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a forward‑looking primer on the Fesi (ferrosilicon) powder market that is tailored for executive teams preparing decisions in 2026. This piece synthesizes the high‑level market trajectory, regulatory inflection points, competitive dynamics and practical actions you should be taking now — while deliberately withholding the transaction‑level segmentation tables and granular region/application shares that are contained in our full Fesi Powder Market study. Consider this a strategic trailer: enough context to shape boardroom debate, not the full ledger required for final contracting.
Fesi Powder Market
Market snapshot: the macro trajectory
The Fesi powder market is on a steady expansion path. Using 2025 as our base year and a historical window of 2020–2025, our market systematics project the sector through a 2026–2032 forecast horizon. The market exhibits a mid‑single digit compound annual growth rate (CAGR) of 5.2% over the forecast period. Put simply, the market that was measured in the low‑to‑mid billions (USD, Million unit reporting) in the early 2020s continues to expand, with the 2025 base providing a launch point for 2026 planning and a clear ramp across the late 2020s into 2032.
Fesi Powder Market
Why emphasize the macro numbers? Because procurement cadence, capex timing and contract tenors should be set against an expectation of sustained demand growth rather than a short‑lived cycle. The growth profile creates windows for capacity investments, premium product positioning (high‑purity powders, narrow particle size distributions) and consolidation plays — but those moves must be timed against regulatory signals and supply reactions detailed below.
Fesi Powder Market
Why 2026 is a decisive window
- Regulatory shockwaves are compressing lead times. From late‑2025 onward multiple jurisdictions introduced import and export controls that change trade math and create near‑term price and availability volatility. These changes materially affect sourcing from large exporting hubs and alter the calculus for local versus imported supply.
- Supply adjustments are already visible. Major producers have responded to uncertainty by moderating production in certain assets. At the same time, new greenfield and brownfield capacity investments in exporter regions are being brought online. This simultaneous contraction and expansion creates localized tightness even as aggregated capacity increases — a classic environment favoring agile buyers and position‑taking sellers.
- Application demand is evolving. Traditional metallurgical demand remains foundational, but specialty uses (dense media separation for mining, high‑purity deoxidation grades for advanced steels, powder for electrode and additive applications) are consuming improving shares of the value chain. Product specification matters increasingly as customers seek narrow particle size distributions and trace element control.
Key strategic questions for 2026
- How much price and availability risk do you want to carry through 2026–2027, and which contract structures (term versus spot, indexed pricing, minimum take) best balance cost and continuity?
- What portion of your demand should be shifted to accredited, traceable suppliers versus opportunistic spot purchases from low‑cost exporters?
- Do you have in‑house capabilities to adjust product specification (particle milling, blending) to capture value from higher‑margin grades?
- Which regulatory scenarios (tightening export controls, import duties/tariff rate quotas) have the largest downside for your supply chain, and which early indicators will you monitor?
- Is there an M&A or JV opportunity (e.g., minority stakes in regional producers or toll‑processing arrangements) that can secure preferential allocation for your off‑take?
What our Fesi Powder Market report delivers — practical, execution‑oriented content
The full PW Consulting study is designed as an operational playbook for 2026 action. Highlights include:
- Forward demand model and scenario engine (2026–2032) that lets you stress test demand under alternative macro, regulatory and technology pathways.
- Supplier capacity and utilization database with plant‑level intelligence, commissioning schedules and a risk scorecard for each production asset.
- Price and cost curve analytics, inclusive of energy, alloying inputs and logistics sensitivity — with scenario outputs for contracted vs spot exposure.
- Regulatory impact maps and a playbook that translates new export/import controls into actionable procurement steps (compliance checkpoints, certification requirements, documentation and sample testing protocols).
- Supplier benchmarking and procurement templates — RFP language, specification checklists (particle size, chemical tolerances), contract clauses for allocation and force majeure tailored to the recent trade shifts.
- M&A and partnership shortlists with high‑level financial proxies and integration considerations; an annex with negotiation levers for securing throughput or priority allocations.
- Excel‑based models and slide packs for boardroom briefings so you can convert market insight into procurement and capex decisions within weeks, not months.
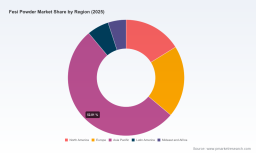
Note: the report contains detailed segmentation by region, type (atomized, milled, other) and application with a full breakdown of shares and values. We omit those granular splits here to preserve the “trailer” purpose of this article and to invite you to access the full dataset and interactive tools on our website.
Competitive landscape — who matters and why
The Fesi powder market shows moderate concentration: the top three producers account for a material share of global sales, and the top five increase that footprint further — a structure that enables coordinated supply responses when market signals shift. Against that backdrop, several firms warrant strategic attention:
- DMS Powders (South Africa) — A focused supplier of milled and atomized grades engineered for dense media separation. Their product suite and quality control for slurry applications make them a preferred partner for mining customers that require narrow density control. If your exposure to mining is material, DMS‑specialized suppliers are an allocation play.
- Elkem ASA (Norway) — An integrated global manufacturer with upstream capabilities and well‑developed metallurgical powders. Recent production curtailments in response to market and regulatory developments signal the strategic balancing act large producers are making between price discipline and market share protection.
- Ferroglobe PLC & Finnfjord AS — European producers with strong footholds in alloy and powder supply. Their positioning matters most where regional safeguards or logistics create a premium on local supply.
- OM Holdings Ltd (Singapore) — A diversified supplier with reach across Asia and downstream relationships that can be leveraged for strategic stocks or preferred pricing agreements.
- Stanford Advanced Materials (United States) — A niche, high‑purity supplier focused on ≥99% FeSi grades for demanding deoxidation and specialty steelmaking applications.
- Anyang Lishi & Zhenan Metallurgy (China) — High‑volume producers and exporters that historically supplied large volumes into global markets. New export licensing regimes and batch testing requirements will reprice and reallocate flows; buyers that previously leaned on low‑cost Chinese origins should revalidate qualification pathways and contingency plans.
For each competitor we map strategic levers in the full report: volume flexibility, quality differentiation, geographic exposure, and willingness to trade long‑term vs opportunistic contracts. URLs and company profiles are included in the annex for procurement teams validating counterparty credentials.
Immediate recommendations for procurement and strategy teams (next 90–180 days)
- Initiate a scenario planning sprint that models three regulatory outcomes (status quo, targeted restrictions, broad export controls) and their impact on price and availability for your specific product specs.
- Secure 6–12 month cover on critical grades where supply‑chain frictions are plausible; favor contracts with allocation guarantees and tiered pricing that align supplier incentives with your reliability needs.
- Qualify at least two alternate suppliers for each critical specification and document accelerated qualification steps (testing labs, sample flows, acceptance criteria).
- Task a commercial analytics cell with monitoring leading indicators: expiring quotas, export licence issuance cadence, vessel/charter rates to key hubs and energy price movements at major production sites.
- Map inventory triggers and working capital tradeoffs — use our downloadable threshold model to define reorder points tied to real market signals rather than calendar rules.
Medium‑term moves (2026–2028)
- Evaluate strategic equity or tolling arrangements in regions where long‑term allocations can be secured at a predictable margin.
- Invest selectively in in‑house powder processing capabilities (milling, classification) if premium differentials for tailored particle sizes justify capital.
- Develop an ESG‑aligned supplier program that incorporates traceability, emissions intensity and compliance auditing — buyers who can credibly claim low‑risk supply will capture a valuation premium in specialty segments.
Using the report in your 2026 boardroom
Boards and procurement committees will be asking for three things: a quantified risk exposure, a set of implementable mitigation steps, and a recommended capital allocation that balances upside capture with downside protection. The PW Consulting Fesi Powder Market report is organized to deliver exactly that: an executive summary with three scenarios, a tactical 90‑day playbook, and the financial sensitivities to support an approval package. We also provide a ready‑to‑use slide deck and a customizable Excel model so teams can present alternatives backed by our data.
Final note and call to action
The global Fesi powder landscape in 2026 is best described as growth with guarded fragility: structural demand drivers support a mid‑single digit CAGR, yet trade measures, export licensing reforms and localized capacity decisions create episodic tightness and price dispersion. Smart market participants will convert visibility into selective, contractual advantage rather than blanket hedging or speculative accumulation.
For access to the full data tables, plant‑level capacity database, segmentation breakdowns and supplier scorecards that underpin this executive preview, visit the PW Consulting Fesi Powder Market report page or contact our team for a tailored briefing. The full study contains the granular intelligence you need to convert the strategic implications outlined here into executed decisions in 2026.
For detailed analysis of this topic, please visit the official page: Fesi Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


