



PW Consulting: Pool Cleaners Market to Reach USD 197.09 Million by 2032 (6.23% CAGR)

Pool Cleaners Market 2026 — Strategic Outlook & Actionable Intelligence
Executive teaser
By 2025 the global pool cleaners market reached a significant inflection point with an estimated market size of USD 115.0 Million (base year 2025). Our forecast through 2032 projects continued healthy expansion at a compound annual growth rate (CAGR) of 6.23%, taking the market to roughly USD 197.1 Million by 2032. For executives making resource allocation and go-to-market decisions in 2026, these headline numbers are more than a growth story — they frame a time-limited window to capture share as product innovation, channel evolution, and supply-side disruption converge.
Pool Cleaners Market
Why this research matters for 2026 decision cycles
-
Prioritization: With mid-single-digit CAGR and accelerating product innovation, companies must choose where to invest R&D and capex to convert macro growth into profitable share gains.
Pool Cleaners Market -
Risk mitigation: New tariff regimes and raw-material pressures introduced in 2025 meaningfully affect cost structures. The research translates these macro shocks into scenario-ready mitigation plans.
Pool Cleaners Market -
M&A and partnering: Consolidation opportunities are concentrated in specific technology niches and manufacturing capabilities. Our work shows where bolt-on acquisitions or JVs create immediate strategic leverage.
-
Commercialization timing: Rapid new-product introductions — notably at CES 2026 — have compressed the product cycle. The report gives timing guidance to accelerate commercialization while protecting margins.
Market dynamics — what is changing and why it matters
The market expansion we model is not uniform. It is being driven by three interlocking forces: (1) product-level innovation (AI navigation, hybrid power systems, cordless autonomy), (2) shifting buyer expectations (smart-home integration, lower energy footprints, improved user UX), and (3) supply-chain and regulatory disruption that is raising the floor on manufacturing costs. Each force creates both opportunity and constraint for incumbent manufacturers and new entrants.
-
Product innovation: 2026 has already shown strong momentum. Several leading players launched next-generation robotic cleaners featuring AI-powered navigation, multi-modal suction and jet systems, and hybrid/cordless power configurations. These advances materially raise buyer willingness to pay and shift competitive parity toward firms that can scale software-enabled features.
-
Channel transformation: E-commerce, subscription service models (maintenance-as-a-service), and value-added installer networks are changing distribution economics. The research maps viable channel mixes by business model archetype and quantifies the sales productivity delta between legacy and new-channel approaches.
-
Supply-side pressure: New tariffs imposed as of March 2025 (including elevated duties on key metals and selective tariffs on imports from specific origins) are increasing input cost volatility and creating incentives to rethink localization, dual-sourcing, and component redesign to avoid tariff buckets.
Competitive landscape — profiles and strategic implications
The market is populated by a mix of long-established incumbents and fast-moving specialty players. Our competitive framework assesses each major player across product breadth, channel reach, innovation capability, manufacturing footprint, and financial flexibility. Key takeaways for 2026 planning:
-
Maytronics Ltd. (Kibbutz Yizre'el, Israel): A clear leader in AI-enabled robotic platforms and strong brand equity in both residential and commercial segments. Their latest generation devices emphasize advanced navigation and hybrid power, reinforcing a product-led premium strategy. Strategic implication: rivals seeking to neutralize Maytronics’ differentiation must invest in comparable software and service ecosystems, not just hardware.
-
Hayward Industries, Inc. (Charlotte, NC, USA): A broad-based player with multi-technology offerings across robotic, suction, and pressure-side solutions. Their scale in distribution and aftermarket parts gives them resilience on price competition. Strategic implication: Hayward can play a defensive role on volume while selectively targeting margin accretion through services and aftermarket subscriptions.
-
Pentair plc (Eden Prairie, MN, USA): Offers a full range of cleaner modalities and benefits from integrated product portfolios across pool systems. Their strength is cross-selling and channel partnerships with installers. Strategic implication: companies competing on product must account for Pentair’s advantage in bundled offers that increase customer switching costs.
-
Fluidra S.A. (Barcelona, Spain): A portfolio player with strong brand lines and global reach. Fluidra’s strategy balances premium robotic products with distribution efficiency. Strategic implication: potential inorganic moves to shore up technology gaps or capacity shortfalls are realistic near-term plays.
-
Aiper Intelligent LLC (USA): A fast innovator in cordless, AI-driven robotic cleaners. Recent launches have signaled an aggressive push into smart, consumer-friendly price points. Strategic implication: nimble entrants can reshape market expectations on features, forcing incumbents into faster innovation cycles.
-
NingBo Poolstar Pool Products Co., Ltd. (Ningbo, China): A major OEM/ODM with scale manufacturing capability. Their value proposition is low-cost production and customization, enabling both own-brand and private-label strategies. Strategic implication: companies requiring cost flexibility or private-label capabilities will continue to engage with large OEMs, but should stress-test quality and IP protections.
Recent developments that reset strategic timelines
-
January 2026 — Aiper unveiled next‑gen Scuba V3 models emphasizing advanced AI navigation at CES 2026, signaling the speed of feature adoption in the cordless segment.
-
January 2026 — Maytronics launched the Dolphin EON with JetIQ and SmartMap navigation; a hybrid power approach that targets both energy-sensitive buyers and commercial operators seeking uptime improvements.
-
February 2026 — iGarden / Fairland Group released an award-honored bionic dual‑vision cleaner, highlighting how new sensor-fusion approaches are moving from concept to consumer-ready products.
Report contents — what you will get and how it is practical
This study combines quantitative forecasting with operational toolkits designed for immediate executive use. Highlights include:
-
Macro sizing & trend analysis from 2020 through 2025, with a forward build and scenario modeling across 2026–2032 (anchored to our base-year estimate and CAGR).
-
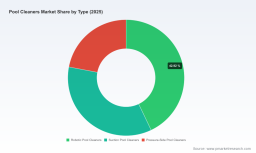
Technology and product roadmap mapping that shows adoption curves for robotic, suction, and pressure-side cleaners — and the conditional triggers that accelerate migration to higher-margin robotic platforms.
-
Competitive intelligence dossiers for leading vendors, including strategic positioning, go-to-market playbooks, recent product launches, and an assessment of who benefits most from current shifts.
-
Supply-chain stress tests and tariff-impact scenarios (post-March 2025 regulatory changes), plus actionable sourcing strategies — from nearshoring to design-for-cost initiatives.
-
Commercial frameworks: pricing-sensitivity models, channel economics, installer incentive designs, and pilot templates for subscription or service-based business models.
-
M&A and partnership heatmaps that identify capability gaps (e.g., AI navigation, battery systems, localized manufacturing) and suggest match candidates by strategic fit and execution complexity.
How to use these insights in the next 90 days
-
Week 1–2: Run a rapid impact assessment against the tariff scenarios included in the report. Identify the three product lines most exposed to input-cost inflation and quantify margin vulnerability.
-
Week 3–6: Undertake a product feature prioritization workshop using our feature-economics matrix. Decide which AI, power, and connectivity features to fast-track into production for 2026 launches.
-
Month 2–3: Execute a channel pilots plan — test a direct-to-consumer subscription bundle and an installer partnership in two contrasting markets to evaluate CAC and lifetime value assumptions.
-
Quarter 1: Formalize a 12-month M&A screening process using our heatmap to pick the right inorganic targets for capability or capacity extension.
Strategic options to consider
-
Invest in software and service: Convert hardware buyers into recurring revenue relationships by embedding diagnostics, predictive maintenance, and subscription maintenance plans.
-
Redesign for tariff resilience: Accelerate design-for-manufacture programs that minimize duty exposure and enable easier local assembly.
-
Differentiate through energy efficiency: Prioritize hybrid and low-energy platforms to capture environmentally conscious buyers and reduce total cost of ownership.
-
Pursue selective consolidation: Use M&A to acquire specialized AI navigation or battery IP rather than building internally on a long timeline.
Concluding note — the strategic value for 2026
With the market on a steady growth trajectory and product innovation accelerating, 2026 is a pivotal operational year. Executives who combine disciplined scenario planning (to offset tariff and supply risk) with rapid commercialization of software-enabled features will capture outsized returns. Our report is designed to be the playbook that translates the broad market trajectory — anchored in our base-year sizing and 6.23% CAGR forecast — into executable moves for the next twelve months.
Next steps
For the full suite of models, segment-level forecasts, company scorecards, and downloadable scenario tools that underpin these conclusions, please consult our detailed market report. The executive summary above intentionally highlights the strategic direction while preserving the granular segment data for the full study to ensure you have the complete intelligence required to act with conviction.
For detailed analysis of this topic, please visit the official page: Pool Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


