



Chargeable Flexible Battery Market to hit USD 932.34 Million by 2032 — CAGR 22.4% | PW Consulting

Chargeable Flexible Battery Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
As organisations plan investments and product roadmaps for 2026 and beyond, the chargeable flexible battery sector is transitioning from niche innovation into a commercially material market. PW Consulting’s latest study—anchored on a 2025 base year and projecting through 2032—quantifies that trajectory in commercial terms while linking it directly to the regulatory, manufacturing and go‑to‑market decisions firms must make now.
Chargeable Flexible Battery Market
In headline terms, the global market (USD, revenue in Million) expanded from approximately 93.15 in 2020 to 226.52 in 2025 and PW Consulting forecasts a continuation of rapid expansion to roughly 932.34 by 2032. This expansion reflects a compounded annual growth rate of 22.4% across our 2026–2032 forecast window. Market concentration today is moderate: the top three firms account for about 25% of revenue and the top five roughly 32%, leaving substantial addressable opportunity for new entrants and adjacent incumbent players.
Chargeable Flexible Battery Market
Why 2026 is a strategic inflection point
- Regulatory timing: New EU battery rules and labelling requirements that took effect around 2026 dramatically change compliance costs and supplier selection criteria for manufacturers and OEMs targeting European markets.
- Commercial scale-up: 2024–2026 was the period when pilot deployments matured into first commercial programs—creating the need for robust supply chain contracting, qualification procedures and lifecycle cost modelling.
- Technology maturation: Multiple cell chemistries and form factors (thin film, printed, solid‑state variants) have reached sufficient TRL to be considered for volume programs; choosing the right technical partner is now a commercial, not just an R&D decision.
Market trajectory and interpretation
Understanding the market trajectory is foundational for capital allocation. Our historical series (2020–2025) shows an early, steady rise followed by a pronounced acceleration as flexible batteries were integrated into new classes of wearables, medical sensors and industrial IoT. The forecast to 2032 anticipates continued high‑teens to low‑twenties CAGR (22.4% in our baseline), driven by unit adoption, new form factor applications, and higher average revenue per device as functionality (fast‑charging, embedded management, certification) is bundled into battery subsystems.
Chargeable Flexible Battery Market
For executives this means: revenue pools will expand quickly, but they will do so unevenly across use cases and geographies. The result is a high‑value window in which early strategic moves—technology licensing, exclusive supply arrangements, or differentiated compliance capabilities—can secure disproportionate commercial returns.
Dynamics reshaping supplier selection and product strategy
- Regulatory and standards pressure: The EU Battery Regulation introduced mandatory carbon footprint verification for larger rechargeable batteries and new labelling and removability guidance. These rules are translating into customer procurement requirements and new vendor pre‑qualification checkpoints.
- Certification and conformity: Accredited notified bodies and testing partners are becoming gating factors. Recent accreditations of major test houses signal faster routes to market for manufacturers that engage early with conformity processes.
- Sustainability economics: Recycling efficiency targets and lifecycle reporting are shifting the cost curve. Buyers increasingly value suppliers with verifiable recycling pathways and lower cradle‑to‑gate footprints.
- IP and technology differentiation: New patents for flexible high‑cycle lithium and scalable flexible battery systems indicate continued innovation around energy density, cycle life and manufacturability—each of which will determine where value pools consolidate.
Competitive landscape: what to watch
The sector combines large, vertically integrated incumbents with specialised innovators. The competitive set we examine includes global battery majors (e.g., Samsung SDI, LG Chem, Panasonic) alongside flexible/patterned battery specialists and printed‑battery pioneers (e.g., Blue Spark Technologies, Enfucell, BrightVolt, Imprint Energy, Cymbet, Jenax, FlexEl).
- Large incumbents (Samsung SDI, LG Chem, Panasonic): Their strengths are scale manufacturing, deep OEM relationships, and materials development capability. They are best positioned to supply tier‑one wearable customers and industrial integrators that require stringent supply continuity, warranty frameworks and technical integration support.
- Specialist innovators (Blue Spark, Enfucell, BrightVolt, Imprint Energy, Cymbet, Jenax): These firms govern important niches: printed batteries optimized for conformal sensors, ultrathin solid‑state solutions for ultra‑low profile devices, and zinc‑based chemistry for specific cost/perf tradeoffs. Their value is speed‑to‑market in new product categories and the ability to adapt form factor and integration approaches quickly.
- Custom converters (FlexEl and others): These players serve medical device and industrial wearable customers where bespoke mechanical and regulatory requirements defeat off‑the‑shelf solutions. They are high touch, high margin partners for regulated end markets.
Strategically, incumbents will compete on reliability, certification and global footprint; specialists will compete on differentiation of form factor, integration ease, and aggressive cost curves. Partnerships and M&A in 2026 will likely follow two patterns: (1) incumbents acquiring or partnering with printed/solid‑state innovators to round out portfolios; (2) strategic alliances between OEMs and flexible battery specialists for co‑developed modules with embedded sensing, firmware and verification.
Recent developments and implications
- Patent activity around high‑cycle lithium and scalable flexible systems indicates that next‑generation chemistries will be selectively proprietary. Licencing strategies and freedom‑to‑operate checks should be pursued early in product development.
- Regulatory actions—specifically EU rules taking effect in early 2026 and due diligence phases in 2027—create a compliance timeline that product and procurement teams must map into their launch schedules.
- Accreditation of conformity assessment bodies accelerates time‑to‑market for compliant products, but firms must engage these bodies early to avoid qualification bottlenecks.
What PW Consulting’s full study provides (practical deliverables)
Our full report is engineered as a decision‑support toolkit for corporate leaders, product managers and procurement teams. Key deliverables include:
- Market sizing and scenario modelling (historical 2020–2025, baseline and two alternative adoption scenarios for 2026–2032 with sensitivity to unit economics and regulatory cost impacts).
- Technology roadmaps that align chemistry, form factor and manufacturing maturity to specific use‑case economics.
- Regulatory compliance playbook—step‑by‑step actions and timelines for EU conformity, labelling and carbon reporting obligations, plus vendor contract clauses to allocate compliance risk.
- Supplier scorecards and sourcing decision matrices tailored by OEM use case: wearables, medical devices, consumer devices and industrial sensors.
- Commercial due diligence templates and valuation heuristics for M&A and licensing transactions in this space.
- Go‑to‑market playbooks for new entrants: channel strategy, pilot program design, and enterprise customer qualification frameworks.
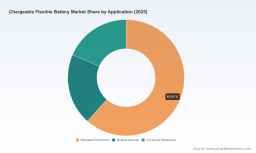
To preserve the report’s role as a strategic asset, we intentionally present headline macro flows publicly while withholding detailed breakouts for regions, types and applications in this introduction—these granular allocations are included in the client report and underpin the revenue forecasts and scenario outputs.
Action framework for executives in 2026
- Map compliance to product roadmaps: Integrate EU labelling and carbon footprint timelines into product launch gates. Non‑compliant products risk market exclusion or costly rework.
- Prioritise platform partners: Choose technology partners based on a mix of technical fit, certification readiness and IP posture—not just on price per cell.
- Design for circularity: Make recyclability and removability upstream design criteria; this reduces total cost of ownership as recycling targets and reporting requirements tighten.
- Stage investments: Use the 2026–2028 window to pilot, standardise and modularise battery subsystems before scaling manufacturing investments that are harder to reverse.
- Hedge with multiple chemistries: Given rapid innovation and patenting activity, maintain optionality across solid‑state, thin‑film and printed approaches for key product lines.
Final thoughts — the opportunity and the trade‑offs
The chargeable flexible battery market presents a classic growth‑with‑complexity opportunity: fast expanding revenue pools (our baseline projects near fourfold growth from 2025 to 2032), meaningful differentiation on technical and regulatory axes, and a supplier base split between scale and specialist capability. The winners will not be those who merely move fastest, but those who align technical choice, regulatory readiness and commercial partnerships into a coherent, executable plan.
PW Consulting’s full study provides the actionable intelligence and tools to do exactly that: quantified scenarios, supplier assessments, compliance playbooks and deal templates that translate market potential into executable strategies. For teams making 2026 decisions—whether to partner, acquire, enter new segments or re‑engineer products—the difference between a pilot and a profitable, repeatable program will be the quality of the market and risk insights that guide those choices.
Learn more
This introduction is a synopsis of the study’s strategic findings. For the full dataset, segmented forecasts, supplier benchmarking and our actionable 90‑day implementation playbook, please consult the full PW Consulting report and client portal.
For detailed analysis of this topic, please visit the official page: Chargeable Flexible Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


