



PW Consulting: Automatic Deburring Machine Market to Reach USD 691.27M by 2032 at 3.85% CAGR

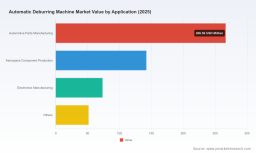
Automatic Deburring Machine Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As the manufacturing sector moves deeper into higher-mix, higher-precision production paradigms, automatic deburring machines have migrated from an efficiency play to a strategic production lever. PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies that maturation: the global market has expanded steadily over the past half decade and is projected to grow at a compound annual growth rate (CAGR) of 3.85% through 2032 (all values in USD Million). For corporate strategists planning capital allocation, capacity expansion, or M&A in 2026, this research is designed as an operationally focused intelligence pack — showing where to act and why, while preserving the granular datasets behind a gated analysis for subscribers and clients.
Automatic Deburring Machine Market
Market trajectory and what it means for 2026 planning
- Between 2020 and 2025 the reported market exhibited steady recovery and growth in line with broader capital equipment investment cycles, reflecting renewed spending in metal fabrication, automotive components, aerospace, and electronics supply chains.
- With a 2025 base established, our forecast through 2032 assumes steady technology substitution and selective capacity additions. The market’s moderate CAGR of 3.85% signals a mature growth profile: not explosive, but predictable — a profile that favors disciplined, ROI-driven investments rather than speculative expansion.
- For CFOs and heads of operations, that predictability enables multi-year capital planning tied to measurable productivity and quality KPIs (scrap reduction, first-pass yield, cycle-time improvements) rather than exposure to volatile demand swings.
Why automatic deburring matters now — strategic drivers
- Labor economics: Ongoing skilled-labor shortages and escalating wage pressure are pushing manufacturers to eliminate manual deburring from critical workstreams where tolerance and repeatability are determinative of downstream process yield.
- Quality & throughput: Automated systems bring reproducibility that manual operations struggle to match across mixed-batch runs, making them attractive as OEMs shorten lead times and tighten specifications.
- Regulatory and sustainability pressure: New energy-efficiency targets and waste-reduction regulations are accelerating demand for machines that minimize consumables, enable closed-loop fluid management, and reduce secondary finishing steps.
- Materials and abrasives: Advances in engineered abrasives and polymer components are expanding the addressable part geometries for automatic systems, unlocking retrofit and greenfield opportunities in precision metal finishing.
Market structure and competitive dynamics — a pragmatic read
The market is characterized by fragmentation: numerous specialized OEMs and systems integrators provide solutions across vibratory, tumbling, centrifuge, water-jet, and robotized deburring technologies. No single supplier dominates; top vendors account for less than a third of total revenue, which creates a competitive landscape composed of niche specialists and regional champions.
Automatic Deburring Machine Market
For 2026 strategic programs, this structure creates two evergreen plays:
Automatic Deburring Machine Market
- Acquire or partner for capability: Large fabricators and automation players can accelerate time-to-market through bolt-on acquisitions of niche deburring technology providers or by partnering with best-of-breed OEMs for co-developed systems.
- Differentiate on integration and services: Vendors that combine machine capability with robust material handling, part tracking, and consumable management will capture higher-margin aftermarket revenue and longer customer lifecycles.
Competitive snapshot — vendors to watch
The market’s vendor universe includes equipment specialists, systems integrators, and global machine builders. Our study profiles the competitive strategies of leading names and what their moves imply for buyers and competitors:
- Timesavers LLC — Known for a comprehensive line of automated deburring and metal finishing systems leveraging advanced abrasives. Their strength lies in end-to-end finishing lines suited to mid- and high-volume metal shops.
- ARKU GmbH — German engineering focused on coil- and sheet-level edge processing with strong automation concepts and material handling for stamped and cut-part workflows.
- Sugino Corp. — Japanese specialist in high-pressure water-jet CNC deburring and washing systems, particularly for complex geometries common in precision industries.
- United Surface Solutions LLC — U.S.-based centrifugal deburring and water recycling systems provider, with offerings aimed at sustainability-conscious operations.
- Valgro India Limited — A regional player leveraging brush and belt grinding technologies for sheet metal processing, with expanding international trade-show visibility.
- Autopulit S.A. — Spanish firm delivering CNC and robotized solutions tailored to sheet metal and precision manufacturing, emphasizing flexibility for small- to medium-batch production.
- Fladder Danmark A/S — Danish supplier of programmable deburring and surface finishing machines covering multiple substrates including metal and plastics.
- Murata Machinery, Ltd. — Integrates deburring machines into larger automated lines, targeting customers seeking turnkey high- and low-volume solutions.
- Kramer Industries Inc. — Offers finishing equipment serving metal fabrication, automotive, and aerospace segments, positioned for retrofit and replacement demand.
Recent product and commercial activity underscores shifting competitive priorities: notable trade-show reveals in 2025 included demonstrations by Timesavers and ARKU at major fabricator exhibitions and Valgro’s showcase of finishing systems in North America — evidence that OEMs are using live events to accelerate product validation and customer acquisition.
What PW Consulting’s report delivers — operationally actionable insight
We built this research to be a tool that drives decisions in 2026. The deliverables are organized around executable outcomes rather than raw charts:
- Market sizing and validated historical series (2020–2025) plus forward projections (2026–2032) by technology class and application — enabling capital budgeting and addressable-market calculations.
- Adoption-roadmaps mapping technology fit to part families and production models, helping engineering leaders select the right architecture (vibratory, tumbling, centrifugal, water-jet, robotic) for their SKU mix.
- Buyer’s playbook — procurement scorecards, expected TCO ranges, lead-time sensitivities, and negotiation levers tied to consumables and service agreements.
- Vendor impact matrices — comparative positioning of the key OEMs, integration capabilities, aftermarket economics, and go-to-market tendencies (direct vs. distributor, retrofit focus, industry specialization).
- Regulatory and sustainability checklists — energy and waste-reduction benchmarks, compliance pathways, and supplier audit templates to accelerate procurement approvals.
- Supply-chain stress tests — scenario-based analysis on abrasives and polymer components, highlighting single-supplier risks and substitution pathways.
- M&A and partnership screening — tactical criteria and shortlists for acquirers and corporate development teams to fast-track diligence on strategic targets.
- Case studies and ROI models — real-world deployment examples quantifying cycle-time gains, labor-content reduction, and quality improvements with modeled payback periods.
How executives should use this intelligence in 2026
- Capital planners: Use the report’s segmented demand outlook to phase investments in deburring assets against product ramps, testing alternate CAPEX sizing tied to productivity KPIs.
- Operations leaders: Apply the adoption-roadmaps and case-study templates to pilot machine classes in selected lines, measuring throughput, rework, and consumable cost impacts over a 12–24 month horizon.
- Procurement & supply chain: Leverage vendor impact matrices and supply-chain stress tests to re-shape supplier contracts and secure redundancy for critical consumables.
- M&A and corporate development: Prioritize targets that deliver either technological differentiation (robotized, water-jet) or service-led aftermarket growth — then use our screening criteria to speed diligence.
Risks, unknowns, and what we conceal here (intentional)
True to the “trailer” principle of this preview, we surface strategic direction and high-level metrics but intentionally withhold the detailed segmentation matrices, regional shares, and line-item market splits that buyers and competitors find most actionable. Those guarded datasets — including discrete regional, application, and technology share tables and our ranked supplier revenue estimates — are included in the full report and in our client-ready data feeds.
Key uncertainties we model explicitly in the full analysis (but do not publish in this preview) include: sensitivity of demand to macro-construction cycles in target geographies, pricing elasticity for aftermarket consumables, and the pace at which OEMs adopt closed-loop waste systems under tightening regulation.
Final recommendation — what to do before Q3 2026
- Adopt a staged investment approach: prioritize pilot deployments in lines where manual deburring is a measurable bottleneck and financial payback is under three years.
- Lock consumable and parts supply terms: secure multi-year agreements with alternate suppliers to mitigate potential abrasives and polymer constraints.
- Explore partnerships with best-of-breed OEMs: co-development agreements for machine integration can shorten deployment timelines and create differentiated finishing capabilities.
- Subscribe to the full PW Consulting dataset: obtain the granular regional, type, and application splits necessary for precise addressable-market and ROI modelling.
Next steps
PW Consulting’s full Automatic Deburring Machine Market report provides the data tables, vendor models, and decision frameworks required to translate this strategic preview into a 90–180 day executable plan. For procurement teams, operations leads, and corporate development groups planning actions in 2026, the detailed datasets and scenario tools in the full study are the logical next step to de-risk investments and accelerate time-to-benefit.
For detailed analysis of this topic, please visit the official page: Automatic Deburring Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


