



PW Consulting: FM market USD 2,145B in 2025, set to grow at 6.8% CAGR to 2032

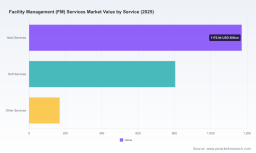
Facility Management Services Market 2026: Strategic Preview for C-Suite and Procurement Leaders
As organizations enter 2026, facility management (FM) is no longer an operational backwater—it is a strategic fulcrum for resilience, cost control, and sustainability. PW Consulting’s forthcoming Facility Management Services Market study (base year 2025; historical review 2020–2025; forecast 2026–2032) synthesizes macro trajectories, competitive moves, regulatory pressures, workforce dynamics, and technology inflection points to give leaders the intelligence required to make high-stakes decisions this year. This introduction outlines the study’s strategic value for 2026 decision cycles while intentionally withholding the granular segment tables and contract-level benchmarks to encourage direct access to the full report for procurement- and portfolio-level action plans.
Facility Management (FM) Services Market
Top-line market context you need to internalize
The FM market has demonstrated both resilience and acceleration through recent cycles. From a global market size in 2020 through 2025, the sector has expanded materially—reaching an estimated USD 2,145.0 billion in 2025—and is forecast to continue growing robustly. Over the study’s forecast window (2026–2032) PW Consulting projects a compound annual growth rate (CAGR) of approximately 6.8%, taking the market to an estimated USD 3,380.32 billion by 2032. The implication for enterprise leaders is straightforward: FM will capture increasing operational and strategic spend, and decisions made in 2026 about suppliers, technology investments, and operating models will shape cost, risk, and sustainability profiles for the rest of the decade.
Facility Management (FM) Services Market
Why this study matters for 2026 decisions
- Timing matters: 2026 is a pivot year where investments in decarbonization and digitalization begin to compound in impact. Early movers capture outsized operational efficiencies and regulatory compliance advantages. The report furnishes tactical roadmaps and ROI timeframes suitable for board-level business cases.
- Risk mitigation & continuity: Labor scarcity, wage inflation, and regulatory acceleration increase service delivery risk. The study quantifies delivery exposure and provides mitigation playbooks—helpful to buyers deciding between insourcing, co-sourcing, or outsourcing models.
- Vendor strategy under pressure: With market concentration remaining relatively low (the top three and top five vendors account for modest shares of global revenue), the sector presents both partnership opportunities and supplier risk. The research helps procurement teams build diversification, partner-tiering, and performance-guarantee strategies.
- CapEx vs OpEx trade-offs: Capital-intensive decarbonization projects and tech modernization require new financing and commercial models. The report includes templates for structuring blended finance and performance-linked contracts aligned to sustainability KPIs.
Key dynamics shaping FM through 2026
- Labor & skills crunch: The labor market pressures are acute. Forecasts point to a shrinking active workforce participation into the early 2030s, exacerbating shortages in HVAC, electrical, and plumbing technicians—skills crucial to FM operations. Higher wages and longer time-to-service are already pressuring margins and delaying maintenance programs in some portfolios.
- Regulation and sustainability: Government building codes, corporate net-zero targets, and frameworks such as ISO 41001 are raising the bar for how FM is procured and delivered. Decision-makers must integrate energy management, emissions reporting, and compliance workflows into vendor KPIs.
- Technology convergence: Digital twins, IoT-enabled predictive maintenance, integrated workplace management systems (IWMS), and AI-driven scheduling are moving from pilots to scale. Software vendors and systems integrators are now critical partners in FM transformation programs.
- Service integration & buyer expectations: Buyers increasingly demand outcome-based contracts that bundle hard and soft services with energy and workplace experience deliverables. This forces providers to orchestrate cross-disciplinary capabilities and creates new procurement complexity.
Competitive landscape — what we observed in market activity
The provider ecosystem is diverse—global outsourcing specialists, integrated services firms, niche technical contractors, and software/platform vendors all compete for slices of the expanding market. Notable competitive themes surfaced from recent corporate actions and deal flow:
Facility Management (FM) Services Market
- Consolidation with capability expansion: Major players continue to pursue acquisitions that either expand service breadth (workplace experience, catering, security) or deepen technical capability (decarbonization, energy management). These moves are often accompanied by new dedicated business units focused on building operations and experience.
- Tech partnerships and platform plays: Several providers are forming partnerships with spatial-data, digital-twin and IWMS vendors to deliver integrated asset and workspace management. This trend elevates software and analytics as a competitive differentiator, not just an operational tool.
- Contract wins centered on integrated offerings: Outsourcing contracts awarded in recent quarters favored providers that could demonstrate global delivery scale plus local technical depth for specialized maintenance and energy services.
- Emergence of outcome-oriented services: Decarbonization and energy optimization services are being packaged as discrete commercial offerings—often with performance guarantees and measurement frameworks—reflecting buyer demand for measurable sustainability outcomes.
PW Consulting’s full report contains benchmarked company profiles, competitive scorecards, and M&A trend maps covering leading providers across the FM ecosystem—including global facilities managers, specialist contractors, and software/platform firms. These profiles analyze strategy, gaps, and fit for different buyer archetypes. (Note: detailed vendor revenue splits and contract-level pricing models are reserved for the full report.)
What the full study delivers — practical content for immediate 2026 action
This research is intentionally operational. Beyond market sizing and high-level forecasting, the report delivers tools that procurement and operations teams can use today:
- Actionable go-to-market and supplier-selection frameworks tailored to buyer size, asset mix, and sustainability ambitions.
- Contract design templates that align incentives, allocate risk, and embed sustainability and digital KPIs.
- ROI and payback models for common technology investments—predictive maintenance, energy management platforms, and space optimization tools—customizable for portfolio-level sensitivity analyses.
- Decarbonization playbooks and measurement frameworks map to regulatory milestones and corporate net-zero pathways.
- Workforce strategies for 2026—recruitment, upskilling, blended labor models, subcontractor ecosystems and wage stress mitigation.
- Scenario-based stress tests and readiness checklists for continuity planning under labor shortages or regulatory shifts.
For executives seeking to accelerate pilot-to-scale timelines, the report includes a phased adoption roadmap and procurement timelines that reflect vendor readiness and market capacity constraints. To maintain the “trailer” principle, granular tables (including regional splits, service-type revenue breakdowns, and contract-level benchmarks) are accessible in the full report data packs.
Strategic recommendations for 2026
- Prioritize decarbonization as a buyer differentiator: Embed energy and emissions KPIs into core FM contracts now. Align payment milestones to verified energy savings and emissions reductions to accelerate provider investment in retrofit and O&M optimization.
- Adopt hybrid delivery models: Where technical labor is scarce, combine provider delivery with certified sub-contractors and upskilled in-house teams. Require providers to submit resourcing contingency plans and apprenticeship commitments as part of RFP responses.
- Invest in interoperability and data governance: Make platform interoperability a contractual pre-condition. Define a single source of truth for asset and energy data to enable portfolio-level optimization and benchmarking.
- Shift to outcome-based commercial models selectively: Use outcome contracts for assets with predictable baselines (e.g., HVAC efficiency, energy use intensity), while retaining traditional models for episodic repair and highly variable services.
- Plan for supplier consolidation and diversity simultaneously: Given the market’s relatively low top-end concentration, pursue strategic partnerships with tier-one providers for scale, while maintaining a diverse network of specialists to ensure technical depth and local responsiveness.
- Embed workforce resilience into vendor SLAs: Include requirements for cross-training, certification targets, and advanced hiring pipelines to reduce service disruption risk from labor shortages.
How PW Consulting’s study supports board and procurement briefings
Boards and procurement committees require succinct, defensible options. This research equips leaders with executive-ready materials—decision trees, investment cases, contract comparators, and a phased implementation calendar tied to supplier capability maps. For buyers evaluating digital twin pilots, the report provides vendor shortlists and expected time-to-value estimates. For organizations facing new government mandates or ISO 41001 considerations, the study supplies compliance pathways and auditing checklists that speed certification and reduce legal exposure.
Next steps — where to get the full intelligence
This introduction provides the strategic contours you need to prioritize FM decisions in 2026. For procurement teams, real estate executives, and sustainability leaders who must translate strategy into contracts and CAPEX/OPEX plans, PW Consulting’s full Facility Management Services Market study delivers the granular models, regional and service-level splits, vendor scorecards, and downloadable templates needed to act. Access to the complete dataset and playbooks is available via PW Consulting’s research portal; the full report includes the proprietary segmentation detail intentionally omitted here to preserve the value of the primary data pack.
In a market growing into the trillions of dollars globally and evolving under the twin pressures of labor disruption and regulation, the decisions you make this year will shape operational risk, sustainability performance, and total cost of occupancy for the next decade. PW Consulting’s study is designed to convert uncertainty into a defensible plan.
For detailed analysis of this topic, please visit the official page: Facility Management (FM) Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


