



PW Consulting: Law Enforcement Software Market to Reach USD 30.02B by 2032 (10% CAGR)

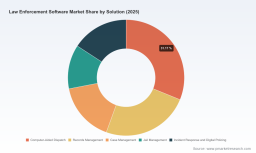
Law Enforcement Software Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present an executive preview of our new Law Enforcement Software Market study — a practical intelligence product designed to shape procurement, investment and operational decisions in 2026. The market is in the middle of a multi‑year expansion driven by cloud migration, evidence digitization, and mandate‑driven compliance. Our analysis shows the sector growing from a mid‑teens billion USD base in 2025 toward a substantially larger market by the end of the decade, underpinned by a forecast compound annual growth rate (CAGR) of 10.0% during the planning window. This preview highlights strategic implications, competitive dynamics and the core levers public‑safety leaders and solution providers must prioritize; detailed segment data and model outputs are reserved for the full report to preserve the “trailer” effect and drive direct engagement with the research portal.
Law Enforcement Software Market
Why this study matters for 2026 decisions
-
Timing: 2026 is the year many agencies finalize cloud‑first roadmaps, consolidate evidence and records platforms, and trade tactical fixes for longer‑term IT architectures. Procurement cycles, grant calendars and staffing constraints create a narrow window where roadmap choices can lock an agency’s operating model for a decade.
Law Enforcement Software Market -
Scale and momentum: The market is expanding rapidly off a 2025 base (our study uses 2025 as the primary reference year), with forecasts showing the sector continuing to accelerate through 2032. The growth is broad‑based across dispatch, records, case/evidence management and digital policing modules — producing recurring revenue opportunities for suppliers and recurring cost obligations for agencies.
Law Enforcement Software Market -
Decision gravity: Choices made in 2026 around deployment model (cloud vs. on‑premises), data residency, vendor lock‑in and integration approach will determine operational resilience, compliance posture and total cost of ownership for years to come.
Market dynamics that will determine winners and losers
-
Cloud and sovereign‑data constraints: Cloud adoption is accelerating, but CJIS and regional data localization rules make “one‑size‑fits‑all” public clouds impractical. Vendors that offer flexible regional hosting and CJIS‑attested architectures will command a premium in procurements.
-
Staffing shortfalls and automation imperatives: Persistent shortages in sworn and civilian staff are forcing agencies to pursue automation-driven efficiencies. Grants and federal funding programs (for example, Byrne‑style assistance) are materially accelerating modernizations — but they also shorten procurement windows, favoring vendors with ready‑to‑deploy modules and clearly demonstrable ROI.
-
Regulatory and audit risk: Compliance is increasingly structural, not transactional. Platforms must bake in evidence integrity, chain‑of‑custody workflows and audit trails to meet CJIS and other jurisdictional standards. Narrow technical non‑compliance can create outsized legal and operational liabilities.
-
Consolidation and concentration: Market concentration is substantial; a relatively small group of incumbents control a majority of institutional deployments, creating high switching costs. At the same time, specialists and point‑solution disruptors are winning pockets of demand by delivering focused functionality or superior integration into camera/LPR and body‑worn systems.
-
Feature velocity and productization: Continuous product updates — from CAD/RMS integrations to AI‑assisted incident triage — are reshaping buyer expectations. Recent vendor activity (for example, feature updates in leading RMS offerings in early 2026) underscores how the competitive battle is now about platform extensibility and upgrade experience as much as feature lists.
Strategic questions for 2026 stakeholders
-
For agency executives: Should you prioritize rapid cloud adoption to get immediate efficiencies, or adopt a hybrid approach to minimize regulatory and legal risk? What is the optimal cadence for consolidating legacy records and evidence silos while preserving case integrity?
-
For procurement and IT teams: How do you design RFPs and SLAs that capture long‑term costs (including migration and sunset of legacy systems) and guard against inadvertent vendor lock‑in?
-
For vendors: Do you double down on platform breadth (end‑to‑end suites) or pursue best‑of‑breed integrations? How do you price multi‑year support and cloud hosting to reflect compliance overheads?
-
For investors and M&A strategists: Which capability gaps (analytics, LPR/AI, evidence lifecycle) justify tuck‑in acquisitions to accelerate time‑to‑value for public‑safety customers?
Competitive landscape — who to watch and why
The vendor field includes large enterprise suites, specialized point vendors, and regional players. Our full report contains a vendor matrix and scoring model; here we summarize strategic positions of core firms that are materially shaping procurement dynamics in 2026:
-
Caliber Public Safety — Known for comprehensive CAD, RMS and CJIS‑secure cloud hosting. Competitive where agencies demand integrated records with strong compliance guarantees.
-
Vector Solutions — Strong in agency readiness and personnel management; competitive advantage when buyers prioritize workforce optimization alongside records modernization.
-
Motorola Solutions — A key incumbent with deep capabilities in CAD/RMS and multi‑agency dispatch coordination; benefits from integration into critical communications ecosystems.
-
Tyler Technologies — Enterprise public‑safety suite vendor with analytics and mobile access strengths; often wins on breadth and existing municipal relationships.
-
Flock Safety — Point‑solution innovator integrating LPR video, AI and investigational workflows. Attractive to agencies seeking rapid intelligence uplift.
-
Axon Enterprise — Differentiates through evidence management and direct integrations to body‑cam ecosystems; strong chain‑of‑custody story.
-
Versaterm — Cloud CAD/RMS player with community engagement modules; competitive in regions looking for modern dispatch and citizen interfaces.
-
CODY Systems — Emphasizes NIBRS native support and mobile RMS, appealing to agencies focused on reporting compliance and cross‑platform data sharing.
-
EIS — Supplier of core CAD, RMS and jail solutions with depth in traditional public‑safety capabilities.
-
PsPortal — Specialist in CJIS‑compliant cloud access for NCIC/NLETS; offers secure gateway capabilities that are essential for compliant cloud deployments.
-
Verint — Focused on emergency call handling and recording; wins where operational efficiency in dispatch centers is mission‑critical.
-
Oracle — Enterprise public‑safety suite with strong system integration, appealing to large jurisdictions and federal customers.
Each vendor’s near‑term performance will depend on the clarity of their compliance posture, hosting footprint, integration APIs, and a field service footprint capable of driving migrations with minimal operational disruption.
What the PW Consulting report delivers (practical contents)
-
Proven market sizing and base‑case forecasts (base year 2025; multi‑scenario projections through 2032) — enabling budgetary planning and revenue modeling for vendors and agencies.
-
Decision frameworks and procurement checklists — RFP language templates, SLA guardrails for CJIS and data residency, and migration risk matrices.
-
Vendor diagnostic scorecards — coverage of architecture, compliance posture, upgrade experience, and third‑party ecosystem strength (non‑public scoring reserved for subscribers).
-
Implementation playbooks — phased migration plans for records and evidence consolidation, rollback triggers and costed staffing models for transition periods.
-
Integration and API maturity assessment — practitioner guidance for integrating CAD, RMS, body‑worn camera systems, LPR feeds and analytics pipelines while preserving chain‑of‑custody.
-
Funding and procurement safeguard guidance — alignment of Byrne‑style grants, capital planning and multi‑year procurement to accelerate adoption with compliance safeguards.
-
M&A and partnership signals — capability gaps likely to attract consolidation and the functional areas where tuck‑ins will create the most immediate customer value.
How to use this intelligence in 2026
-
Procurement teams should treat the report as a short‑list tool: use the scorecards and RFP language to materially lower bid evaluation time and to surface hidden TCO risks that commonly appear during implementation.
-
Agency executives must align funding cycles with migration roadmaps: choose phased technical approaches that prioritize continuity of operations for dispatch and evidence systems.
-
Vendors should use the market sizing and scenario outputs to prioritize product investments — specifically, regional hosting, CJIS attestation, and integration bundles that accelerate agency adoption.
-
Investors and M&A teams can use our triggers list and capability gaps section to identify high‑leverage targets that shorten sales cycles or unlock cross‑sell opportunity for incumbent suites.
Final note and next steps
2026 will be a defining year for law enforcement IT modernization. The market’s trajectory is clear: sustained double‑digit expansion backed by funding flows, pressing operational needs and an accelerating requirements set for compliance and integration. This preview is a tactical orientation; the complete PW Consulting report contains the detailed segmentation, vendor scoring, and downloadable models you need to operationalize decisions. To access the full datasets, scenario models and procurement artifacts referenced here, please obtain the full report through PW Consulting’s research portal — the granular numbers, regional breakdowns and downloadable tools are available to subscribers and purchasing clients.
For immediate advisory engagements — vendor selection workshops, procurement document reviews, or integration assurance — PW Consulting is available to support short‑term deliverables calibrated to 2026 timelines.
For detailed analysis of this topic, please visit the official page: Law Enforcement Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


