



PW Consulting: Titanium Diboride Market to Expand at 4.5% CAGR Through 2032

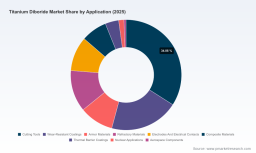
Titanium Diboride Market — Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a concise strategic primer that frames the Titanium Diboride (TiB2) market through the 2026 decision window. This “teaser” synthesizes the report’s most consequential macro findings and strategic implications while intentionally withholding granular segment-level datapoints to steer market participants to the full study. The objective: give C-suite and corporate development teams the contextual clarity needed to prioritize actions in 2026, while reserving the detailed, transaction‑relevant intelligence for the report itself.
Titanium Diboride Market
Macro snapshot you need now
- Base year and scope: The analysis uses 2025 as the base year, traces historical dynamics through 2020–2025, and projects the market across a 2026–2032 forecast horizon.
- Market trajectory: The TiB2 market is expanding at a moderate compound annual growth rate (CAGR) of about 4.5% over the forecast period. After a multi‑year recovery, the market value reached the mid‑double digits (Million USD) range by 2025 and is modeled to continue steady expansion into 2032.
- Market structure: Concentration is material—roughly three firms account for a clear majority of supply, and the top five consolidate an even larger share—indicating an industry with meaningful scale advantages, specialized know‑how, and barriers to rapid fragmentation.
These macro datapoints frame the economics for investment, capacity planning, procurement, and M&A through 2026. They also imply that scale and technology leadership will likely determine winners as demand niches mature.
Titanium Diboride Market
Why TiB2 matters to strategic agendas in 2026
- Cross‑sector leverage: TiB2’s unique combination of hardness, electrical conductivity, and thermal stability underpins a widening set of high‑value applications—from defense armor and aerospace ceramics to sputtering targets for semiconductor thin films and additive manufacturing feedstock. For firms active in adjacent material value chains, TiB2 is increasingly a strategic input rather than a niche commodity.
- Technology inflection points: Improvements in powder grades, nano‑structuring, and AM‑compatible formulations are unlocking new design options for lightweight armor, cutting tools, and high‑temperature components. These technology shifts reframe product roadmaps and supplier selection criteria.
- Supply‑side sensitivity: Boron feedstock dynamics, environmental regulation of mining and processing, and freight/logistics volatility directly affect cost curves and available capacity. Notably, global boric acid prices moved modestly downward in early 2026 amid stable supply conditions, but regulatory and logistical factors remain material risk drivers for 2026 procurement strategies.
What PW Consulting’s full report delivers (practical, transaction‑grade content)
The full Titanium Diboride Market report is built for action; it is designed to support investment committees, procurement teams, product leaders, and M&A advisors. Key deliverables include:
Titanium Diboride Market
- Robust market sizing and growth scenarios—base, upside, and downside—driven by demand trajectories across end markets and technology adoption curves.
- Segment and regional intelligence with quantifiable volumes and revenue breakdowns (note: granular splits are omitted from this primer to preserve advisory value in the full report).
- Price and feedstock sensitivity analysis that models boron input cost swings, regulatory cost pressure, and freight variability across short‑ and medium‑term horizons.
- Supplier and capacity map with capability matrices—identifying incumbent producers, niche specialists (e.g., sputtering‑grade suppliers), and low‑cost producers—plus capex commitments and near‑term capacity changes.
- Technology and product roadmaps evaluating nanostructured vs. bulk TiB2 developments, additive manufacturing grade emergence, and implications for product specifications and qualification timelines.
- Commercial playbooks tailored to different buyer profiles: OEMs, defense primes, semiconductor fabs, and specialty chemical companies—covering procurement levers, qualification, and tier‑1 supplier strategies.
- Risk matrix and mitigation playbook—covering regulatory, feedstock, logistical, and geopolitical scenarios with recommended contracting and hedging approaches.
- M&A and partnership playbook—valuation frameworks, target screening criteria (technology, capacity, customer access), and integration pitfalls specific to TiB2 businesses.
Competitive landscape — what we see and why it matters
The TiB2 sector exhibits a mix of legacy specialty producers, diversified materials conglomerates, and regionally important manufacturers. Strategic implications differ by player type:
- Treibacher Industrie AG (Austria) — a European leader in high‑purity TiB2 powders. Its strength lies in quality and relationships with industrial and aerospace end users; competitive strategy should focus on premiumization and long‑cycle supply contracts.
- 3M/Ceradyne (United States) — dominant in defense and armor applications through longstanding government procurement relationships. For military and aerospace suppliers, aligning to defense qualification timelines remains a lucrative but resource‑intensive route.
- Materion Corporation (United States) — a go‑to for sputtering targets and thin‑film materials for semiconductor and electronics markets. Their business highlights the high margins and technical barriers in electronic‑grade TiB2 segments.
- Japan New Metals Co., Ltd. — focused on specialty, precision, and export markets; strategic edge is quality control and niche application development in advanced tooling and electronics.
- H.C. Starck GmbH (Mitsubishi Materials Group) — positioned as a high‑purity producer with recent product introductions aimed at additive manufacturing. Such moves accelerate adoption curves in aerospace and automotive sectors.
- Shandong Pengcheng and Dandong Chemical Engineering Institute (China) — large regional producers supplying ceramics, cathode materials for aluminum smelting, and industrial cutting tool markets; they emphasize scale and cost competitiveness.
Recent industry moves underscore shifting dynamics. In mid‑2025, Kyocera expanded capacity in South Korea to strengthen regional production presence; shortly before that, a major European producer launched a new TiB2 grade optimized for additive manufacturing. These actions point to two near‑term trends: a regional rebalancing of capacity, and product innovation that compresses qualification timelines for AM and aerospace buyers.
Strategic scenarios and decision levers for 2026
Executives can translate market context into specific, prioritized actions for 2026. We outline three pragmatic scenarios and the associated levers:
- Protect and optimize margins (incumbent producers)
- Secure long‑dated boron feedstock contracts with indexed pricing and force majeure protections; establish multi‑sourcing to reduce vulnerability to regulatory or logistic disturbances.
- Invest selectively in higher‑margin product grades (e.g., AM‑ready or sputtering grades) while rationalizing low‑margin, high‑volume SKUs.
- Accelerate market entry or scale (new entrants and investors)
- Target bolt‑on acquisitions to rapidly obtain certification assets and customer access rather than greenfield capacity, given the market’s moderate CAGR and concentration dynamics.
- Pursue tolling and JV models with regional partners to limit capital intensity and shorten commercialization timelines.
- Downstream hedging and integration (OEMs and strategic buyers)
- Consider dual‑sourcing strategies and strategic stockpiles for critical programs (defense, aerospace) and implement qualification roadmaps to reduce single‑supplier dependency.
- Explore co‑development contracts for AM‑tailored grades to accelerate product performance while sharing development costs and lead times.
Risk checklist — what could materially alter 2026 plans
- Feedstock shocks: Even modest shifts in boric acid availability or logistics can cascade into spot price spikes and margin compression. Early 2026 saw a softening in boric acid spot values, but regulatory and freight volatility remain latent threats.
- Qualification lag for AM and aerospace: New TiB2 grades can be technically superior but require long certification cycles; misjudging timelines can lead to overcapacity or missed demand windows.
- Geopolitical/regulatory shifts: Environmental rules affecting boron mining and processing can change cost structures and force regional reshoring of certain value chain elements.
How to use this primer — and where to find the full intelligence
This briefing is designed to orient boardrooms, corporate development teams, and procurement leaders ahead of 2026 planning cycles. It highlights the market’s steady growth profile (CAGR ~4.5%), concentrated supplier base, and technology‑led demand inflection points—elements that should shape capital allocation, sourcing, and product roadmaps for the coming 12–18 months.
For transaction‑grade analysis, detailed regional and application breakdowns, supplier scorecards, calibrated price models, and executable M&A playbooks, please consult the full Titanium Diboride Market report. The complete study contains the granular segmentation and financial models that firms require to underwrite investments, negotiate supply contracts, and build qualification programs with confidence.
PW Consulting stands ready to brief management teams on the full findings and translate the report’s implications into a prioritized 90‑day action plan tailored to your strategy and role in the value chain.
For detailed analysis of this topic, please visit the official page: Titanium Diboride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


