



PW Consulting: Ultrafast Lasers Market to hit USD 6,887 Million by 2032 (16.62% CAGR)

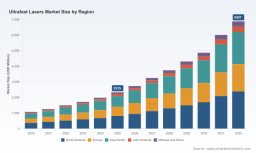
Ultrafast Lasers Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this strategic preview of our Ultrafast Lasers Market study to help executive teams, corporate development units, and R&D leaders prioritize decisions in 2026. The objective here is to surface the high-fidelity signals that matter—market trajectory, competitive positioning, structural risks, and where actionable value can be captured—while reserving the full segmented detail for the primary report. Think of this as a briefing trailer: rigorous, directional, and designed to accelerate a decision to obtain the full playbook.
Ultrafast Lasers Market
Market trajectory and what it means for 2026
Ultrafast lasers are in a clear growth phase. Using 2025 as the study base year, the global market expanded materially through the first half of this decade, and the outlook from 2026–2032 is robust. Our model (USD, revenue unit: Million) shows the market crossing the multi-billion-dollar threshold in the late 2020s and accelerating toward several billion by 2032. The forecast period (2026–2032) is characterized by a compound annual growth rate of approximately 16.6%, reflecting sustained demand across materials processing, medical & healthcare, scientific research, and advanced electronics.
Ultrafast Lasers Market
Why this matters for 2026 decisions:
Ultrafast Lasers Market
- Capital allocation windows are open now. A double-digit CAGR means earlier movers can secure development, capacity, and contracts at terms that will be harder to obtain later as demand concentrates.
- Product roadmaps that hit market readiness in the 2026–2028 window are positioned to capture disproportionate share as adoption curves steepen.
- Supply chain and regulatory constraints (detailed below) create optionality value for firms that can build resilient sourcing and compliance capabilities in 2026.
Competitive landscape — who matters and why
The ultrafast lasers market exhibits moderate concentration: the top three firms account for a majority share of industrial revenue, and the top five together hold an even larger portion. This concentration creates two strategic realities—market leaders can shape price, standards, and channel structures, while mid-tier and niche players can capture value by specializing in adjacent segments or by offering integrated solutions that reduce customer switching costs.
Principal companies we track (representative profiles):
- Coherent Corp (United States) — Offers a complete range of ultrafast scientific oscillators and amplifiers across research, OEM, and industrial channels ( https://www.coherent.com).
- TRUMPF (Germany) — Strong in industrial materials processing and precision manufacturing solutions, with deep machine-integration expertise ( https://www.trumpf.com).
- IPG Photonics (United States) — Known for compact, cost-effective ultrafast fiber lasers optimized for microprocessing and industrial usage ( https://www.ipgphotonics.com).
- Amplitude Systèmes (France) — Femtosecond systems leader focused on micromachining and medical device applications ( https://amplitude-laser.com).
- Ekspla (Lithuania), NKT Photonics (Denmark), Light Conversion (Lithuania), Menlo Systems (Germany), IMRA America (United States), Clark-MXR (United States), Thorlabs (United States) — each brings specialized product, systems, or OEM engineering capabilities relevant to targeted use cases (see full profiles in the report).
Recent competitive moves highlight evolving battlegrounds:
- IPG Photonics showcased ultrafast innovations at Laser World of Photonics in mid-2025 and won a major SPIE award in May 2026 for a high-power compact source—signaling continued R&D and branding momentum in high-power fiber solutions.
- NKT Photonics has moved from product delivery into strategic partnerships, notably delivering subsystems to a quantum computing supplier—an example of lasers enabling adjacent high-value ecosystems.
- IMRA America’s 2026 Foreign-Trade Zone production notification in Michigan signals onshoring of femtosecond fiber manufacturing capacity within the U.S., with implications for lead times, compliance, and U.S. supply resilience.
Structural headwinds and operational risks (and practical mitigations)
Several non-market forces will shape winners and losers in 2026. Our study integrates these "industry context" factors and provides playbooks to mitigate them.
- Regulatory constraints: Certain optical sources and components fall under defense-related export controls (e.g., items identified on the U.S. Munitions List), raising ITAR/ export compliance costs and limiting go-to-market pathways for some advanced products. Strategic recommendation: establish a compliance-first product taxonomy and segregate export-controlled product lines from those that can scale globally without restrictions. The report includes a compliance checklist and decision tree for product development and partnership selection.
- Labor and skills gap: Skilled labor shortages for precision assembly and optical engineering constrain scaling. Tactical moves: partner with regional universities for apprenticeship programs, invest in automation of repeatable assembly stages, and design modular subsystems that reduce manual integration time. We quantify the trade-off between automation CAPEX and shortened time-to-revenue in our financial models.
- Raw material and supplier constraints: Lead times for specialty components (nonlinear crystals, gain media, precision optics) remain extended. Mitigations include strategic inventory hedging, dual-sourcing programs, and selective vertical integration for “bottle-neck” components. The report maps supplier concentration and recommends which components are priority candidates for in-house production versus long-term contracts.
- Supply chain fragility: Low-volume, high-risk commodity supply chains require collaborative risk sharing. Recommended approaches: develop supplier scorecards tied to performance SLAs, invest in supplier development, and use geographically diversified sourcing to minimize single-point failures.
Commercial and product strategy recommendations for 2026
Based on scenario modelling, customer interviews, and technology assessments, firms should prioritize the following:
- Define a two-track product strategy: (1) defend and extend core modules for established industrial customers (service contracts, integrated laser-heads, system-level guarantees), and (2) accelerate a “disruptor” line aimed at high-growth pockets (consumer electronics microprocessing, advanced medical device manufacturing, and quantum subsystem suppliers). The full report provides a timeline-driven roadmap and R&D milestones for each track.
- Negotiate supplier financing and forward-purchase contracts in 2026 to lock down critical optics and pump diodes; include clauses for demand-growth scalability. Our procurement playbook includes model contracts and sensitivity analyses for price and lead-time volatility.
- Leverage partnerships with OEM integrators and system houses to provide bundled solutions that reduce customer integration risk; value-capture models in the report quantify margin uplift from systems sales versus component sales.
- Pursue targeted M&A or strategic JV plays focused on thin but critical capabilities—nonlinear crystals, compact amplifier modules, or real-time beam-monitoring electronics—rather than broad, horizontal consolidation. The report ranks acquisition targets by strategic fit and integration complexity.
What PW Consulting’s full study delivers (practical, executable content)
This preview highlights themes; the full Ultrafast Lasers Market report contains the operational tools that senior teams will use to act in 2026:
- Detailed market-sizing and validated demand scenarios (historical 2020–2025 base, forecast 2026–2032, revenue unit: USD Million) and sensitivity runs tied to adoption curves.
- Go-to-market playbooks for product, pricing, and channel strategies across industrial, medical, scientific, and electronics end-markets.
- Supplier and component maps with recommended sourcing strategies, dual-sourcing candidates, and suggested inventory policies to manage lead-time risk.
- Regulatory and compliance roadmaps (including ITAR/export-control decision trees) and an implementation checklist for product development and international sales.
- Commercial models—TCO, pricing elasticity, and ROI calculators—designed to evaluate leasing vs. outright sale, service tiering, and spare-parts strategies.
- Competitor dossiers with capability matrices, recent strategic moves, and M&A targets, plus stakeholder matrices to support diligence and negotiations.
- Operational playbooks for workforce upskilling, automation deployment, and quality-management practices specific to ultrafast laser assembly and testing.
How to use this preview in your 2026 planning cycle
If you are budgeting, negotiating supplier contracts, or refining your product roadmap for 2026, use this preview to:
- Accelerate capital allocation decisions for R&D and capacity by referencing the market’s growth trajectory and the timing of opportunity windows in the next 24 months.
- Prioritize compliance and supply-chain programs now; regulatory and sourcing lead times will materially affect your time-to-market.
- Prepare tactical M&A playbooks focused on capability fills rather than market share grabs—our scenarios show higher near-term ROI from bolt-on capabilities that shorten customer integration cycles.
Next steps — how PW Consulting can help
For teams ready to act in 2026, PW Consulting offers tailored briefings, acquisition diligence support, supplier negotiation workshops, and integration planning built from the full study. The complete report contains the granular segmented data, exact regional and application breakdowns, and financial schedules you’ll need to finalize investments and contracts. Use this preview to align executive priorities—then commission a customized deep-dive to convert strategy into executable programs.
In short: the ultrafast lasers sector is entering a phase where technological leadership, supply-chain resilience, and regulatory-savvy commercialization will define value creation. The market’s growth dynamics make early 2026 the decisive moment to set the terms of competition for the latter half of this decade.
For detailed analysis of this topic, please visit the official page: Ultrafast Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


