



PW Consulting: Portable Toilets Market to Hit USD 327.72M by 2032 at 7.94% CAGR

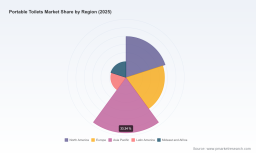
Portable Toilets Market 2026: Strategic Insights for Action — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic preview of our full Portable Toilets Market study — an evidence‑based roadmap intended to shape high‑confidence commercial decisions in 2026. This preview conveys the report’s core takeaways, the decision levers executives must prioritize, and why immediate action will materially affect revenue, cost and risk profiles over the next planning cycle. To preserve the tactical advantage embedded in our proprietary segmentation and scenario models, the granular sub‑segment matrices and vendor scorecards are reserved for the full report.
Portable Toilets Market
Why this market matters in 2026
The portable toilets market is transitioning from a largely transactional rental industry to a technology‑enabled, sustainability‑driven ecosystem. After a steady recovery period in the early 2020s, the market reached a meaningful scale in our base year (2025) and is now on a structurally higher growth trajectory. Our topline model shows the global market moving from the 2025 base through the forecast period (2026–2032) at a compound annual growth rate (CAGR) of 7.94%. Under our central forecast, that trajectory drives the market toward roughly USD 327.7 million by 2032.
Portable Toilets Market
Two structural shifts underpin this growth: first, the professionalization and consolidation of rental and servicing models; second, accelerated product innovation around vacuum systems, luxury sanitation, ADA compliance, and circular manufacturing. Together these forces increase average revenue per unit, create higher aftermarket revenue streams (consumables, deodorants, servicing subscriptions), and raise barriers to entry for low‑cost incumbents.
Portable Toilets Market
What the full study delivers: pragmatic, transaction‑ready intelligence
PW Consulting designed this study to be directly actionable for C‑suite, corporate development, procurement, and field operations teams. The full report contains:
- Topline market sizing and a seven‑year forecast with scenario sensitivity (base, upside, downside) and clear assumptions tied to construction activity, live events recovery, and regulatory pacing.
- Unit economics models for rental fleets (capex, opex, utilization) and ROI breakeven timelines by equipment class.
- Segmentation matrices across product type, application, and region — with elasticities on price, service frequency, and maintenance intensity. (Note: detailed segment share tables are available in the full report.)
- Competitive landscaping and a ranked M&A target list with valuation heuristics, integration risks, and synergies (cost, route density, cross‑sell potential).
- Procurement playbooks — supplier scorecards, sourcing strategies for recycled polymer inputs, and mitigation steps for raw‑material volatility.
- Regulatory and tender tracker covering municipal bid behavior, tax treatments, ADA compliance trends, and environmental permitting that materially affect service obligations.
- Operational blueprints for digitalization: telematics, fill‑level sensing, predictive routing and staffing models that reduce empty miles and service costs.
- Risk matrices covering supply chain, labor, environmental fines, and reputational risk — with mitigation playbooks tailored to rental operators, manufacturers, and event planners.
Competitive landscape: consolidation runway and capability gaps
The market remains moderately fragmented: concentration metrics show that the top three firms account for under one‑quarter of global share, with the top five still well below one‑third of the market. This dispersion creates both acquisition runway for scale‑seeking players and white‑space for differentiated product and service plays.
- PolyJohn (Whiting, Indiana) — A manufacturing stalwart known for portable toilets, sinks, and accessories. Its February 2026 acquisition of EcoFab signals a deliberate expansion into advanced vacuum toilet systems, accelerating its product roadmap and creating a technology arbitrage opportunity for customers seeking lower water usage and improved odor control.
- Satellite Industries (United States) — The largest manufacturer with a broad portfolio spanning restroom trailers, septic trucks, modular solutions and consumables. Satellite’s scale in both hardware and aftermarket supplies positions it as a one‑stop provider for large event and municipal contracts.
- United Site Services (USS) (United States) — The nation’s leading rental provider; strong in standard and ADA‑compliant offerings. USS’s route density and national footprint deliver operational advantages for time‑sensitive tenders but leave opportunity to increase per‑unit profitability through tech‑enabled services.
- Rumpke (Cincinnati, Ohio) — A provider leveraging recycled plastic in unit manufacture and offering VIP trailers and ADA units. Rumpke’s focus on circular inputs aligns with corporate sustainability mandates and creates differentiation where green procurement criteria influence public and private tenders.
- WM (United States) — The broader environmental services firm provides portable sanitation as part of an integrated waste services portfolio. WM’s bundled selling approach is especially effective in construction and long‑duration municipal engagements.
- Stallion Infrastructure Services (United States) — A niche provider of premium and high‑rise solutions and luxury trailers. Stallion illustrates a viable premiumization path that captures higher margins in event and hospitality verticals.
Together, these players illustrate three playbooks that will shape M&A and competitive strategy in 2026: scale consolidation (roll‑ups to capture route density), technology plays (vacuum systems and telematics), and premium/sustainability verticalization (luxury units, recycled materials, and compliance solutions).
Market dynamics that will dictate near‑term strategic moves
- Sustainability and circular manufacturing: Manufacturers increasingly use blow‑molding with recycled plastics for unit bodies. This is not only a marketing differentiator but a procurement lever — clients with ESG targets will prefer vendors with demonstrable recycled content and end‑of‑life recovery programs.
- Regulatory and municipal procurement: Several US municipalities issued tenders for portable toilet rental and servicing for 2026 (including county and municipal bids). In some jurisdictions, rental services receive tax treatment that materially affects contract economics. Firms should map local tax and tender cycles into their go‑to‑market calendars.
- Product innovation and performance: Vacuum toilet systems and luxury flushing units are moving from pilot projects to commercial deployments. These technologies change utilization patterns (longer productive life, different cleaning cadence) and create aftermarket service opportunities.
- Digital operations: Telematics (fill‑level sensors, route optimization) are proven ROI drivers. Early adopters cut empty‑mile costs substantially and improve responsiveness in event deployments.
Strategic implications and recommended 2026 priorities
For executive teams planning 2026 initiatives, our study prioritizes the following actions — each paired with practical KPIs that appear in the full report:
- Adopt a differentiated fleet strategy: Segregate assets into cost‑efficient standard units and higher‑margin premium or vacuum units. Track utilization, maintenance cost per service, and PPE & consumable attachment rates. Run pilots to quantify margin differentials before large‑scale fleet transitions.
- Make targeted technology investments: Invest in telematics across a representative fleet cohort to validate savings in routing and servicing. Shortlist vacuum and advanced flushing systems for high‑value contracts where water scarcity or hygiene standards are non‑negotiable.
- Pursue consolidation where route density creates synergy: Use the full report’s M&A heatmap to identify targets with complementary geographies, under‑utilized fleets, or strong public tender pipelines. Expected outcomes include faster route density improvements and cross‑sell into events and construction segments.
- Embed circular procurement and recycling economics: Negotiate recycled polymer supply contracts and secure takeback agreements. Incorporate lifecycle emission metrics into bids to win ESG‑weighted tenders.
- Revise commercial models for municipal and large event contracts: Account explicitly for local tax treatments, compliance obligations, and service frequency requirements. Structure multi‑year pricing with CPI or input‑price collars.
- Develop aftermarket and consumables revenue streams: Bundled servicing, deodorant subscriptions, and preventive maintenance plans increase ARPU and create more predictable revenue.
How to use this preview — and the next step
This preview is intended to align leadership around the strategic tradeoffs and near‑term priorities we see as essential in 2026. The full PW Consulting Portable Toilets Market report provides the playbooks, models, and deal scoring required to execute these moves with confidence — including:
- Detailed segment economics and pricing sensitivity tables;
- Vendor scorecards and M&A target dossiers with integration checklists;
- Operational templates for telematics deployment and route optimization pilots;
- Regulatory tender calendars and a matrix showing tax and compliance impacts by jurisdiction.
Leaders preparing budgets or pursuing M&A in 2026 should treat this study as prescriptive: the difference between incremental improvement and meaningful market capture will come from combining fleet modernization, targeted acquisitions, and service innovation — executed with a clear, data‑driven plan. For organizations that want to convert these insights into a 100‑day plan, PW Consulting offers tailored workshops and scenario modeling to operationalize the findings.
Closing perspective
The portable toilets sector is no longer a low‑margin, commoditized corner of services. It is evolving into a modular, capital‑efficient market where technology, sustainability and tender‑savvy operators will earn a disproportionate share of growth. With the market growing at an expected 7.94% CAGR through 2032 and compelling opportunities for differentiation across product, service and geographic plays, 2026 represents a critical inflection year. PW Consulting’s full report equips decision‑makers with the actionable intelligence required to convert that inflection into durable competitive advantage.
For access to the full dataset, proprietary segment breakdowns, and the operational playbooks referenced here, please contact PW Consulting. The detailed annexes and vendor scorecards are provided exclusively with the full research package.
For detailed analysis of this topic, please visit the official page: Portable Toilets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


