



PW Consulting: Blood Tubing Set Market to Reach USD 1,370.0M by 2032 at 4.12% CAGR

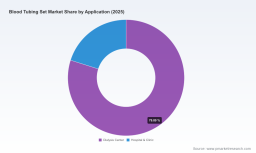
Blood Tubing Set Market — Strategic Preview for 2026 Decision-Makers
As healthcare providers, device manufacturers, and investors prepare plans for 2026, the Blood Tubing Set market is entering a phase where modest compound growth masks structurally important shifts in concentration, regulation, and procurement behavior. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — identifies the commercially actionable inflection points that will determine winners and laggards over the coming investment cycle. Our high-level findings: the market expanded from a steady baseline in the early 2020s to exceed USD 1 billion in the 2025 base year and is projected to approach roughly USD 1.37 billion by 2032 under a 4.12% compound annual growth trajectory. That trajectory coexists with a high degree of supplier concentration, making strategic partner selection and operational resilience central to 2026 planning.
Blood Tubing Set Market
Why this analysis matters in 2026
- Decision clarity for capital allocation: The market is growing steadily but not explosively. Firms deciding whether to invest in new manufacturing capacity, automation, or M&A need forward-looking margin and volume scenarios — not just historical growth rates.
- Regulatory and reimbursement alignment: Blood tubing sets remain Class II devices under FDA 510(k) pathways and are embedded in dialysis reimbursement regimes. Regulatory readiness and coding strategy materially affect time-to-revenue and capture rates in tendered contracts.
- Supplier and product risk management: High market concentration raises counterparty risk; a single device correction or supply shock can ripple through procurement networks and contracts.
- Commercial segmentation playbooks: Differences between procurement in dialysis centers vs. hospital systems, product compatibility across dialysis machines, and single-use sterilization logistics create pathways for premium positioning or cost competition.
Report composition — what you get (practical and deployable)
- Concise executive summary with strategic imperatives tailored for manufacturers, contract manufacturers, large buyers (dialysis networks), and private equity.
- Validated market sizing and a transparent forecast model (2026–2032) with scenario and sensitivity modules you can run for alternate price, volume, and raw material scenarios.
- Demand-side analysis covering clinical drivers (CKD prevalence, modality mix), procurement cycles, and pricing dynamics across care settings.
- Supply-side diagnostics: capacity maps, technology footprints (materials, connector systems, airless/low-volume designs), and a supplier risk heatmap.
- Regulatory and reimbursement dossier: FDA pathways, ISO biocompatibility expectations, sterilization validation protocols, and implications for market access timelines and cost-of-goods.
- Competitive intelligence: company profiles, go-to-market archetypes, contract structures, and a playbook to win tenders and long-term supply agreements.
- Actionable commercial plans: pricing levers, tender strategies, cross-sell opportunities, and sample contracting clauses to de-risk supply continuity.
- Strategic M&A and partnership targets, plus diligence checklists focused on manufacturing quality, sterile supply chain, and regulatory histories.
Macro takeaways and near-term dynamics
The forecasted CAGR of approximately 4.12% conceals heterogeneity that matters. Growth is underpinned by stable demand from hemodialysis programs coupled with incremental value capture from product innovation (e.g., airless systems, low-volume tubing, and machine-specific bundles). At the same time, the market exhibits high concentration among a handful of global suppliers, producing clear advantages for incumbent manufacturers but also exposing buyers to supplier-side disruptions. Our concentration analysis shows that the top three suppliers command a substantial share of the market, with the top five even more dominant — a structural fact that tightens competition for smaller players and elevates consolidation as an effective route to scale.
Blood Tubing Set Market
Cost dynamics are pragmatic: manufacturing economics are driven by medical-grade polymer supply and customization levels (connector types, lengths, and machine compatibility). Material unit economics are modest at the per-set level, but they compound across volume and customization complexity; even small changes in raw-material pricing, sterilization method selection, or yield can swing margins materially. All blood tubing sets in the market are single-use and require validated sterilization prior to release (gamma irradiation and ethylene oxide are the mainstream methods), and biocompatibility testing consistent with ISO 10993 is a gating requirement for market entry.
Blood Tubing Set Market
Regulatory and reimbursement context
- FDA: Hemodialysis blood tubing sets are regulated as Class II devices requiring 510(k) submissions demonstrating substantial equivalence. Post-market vigilance and labeling accuracy are increasingly scrutinized.
- ISO: Compliance with ISO 10993 biocompatibility standards is essential for blood-contacting devices; sterilization validation and leachables testing create non-trivial time and cost hurdles.
- Reimbursement: Dialysis procedures are reimbursed under established outpatient codes in major markets. Manufacturers should align pricing models to procedure-level economics and bundle strategies where possible.
Competitive landscape — profiles and strategic implications
- Nipro Corporation (Osaka, Japan) — Nipro offers machine-specific blood tubing solutions designed for close integration with hemodialysis platforms. Their strategy emphasizes component validation and machine compatibility, which supports long-term OEM relationships and replacement part sales. For incumbents and challengers alike, Nipro’s approach underlines the commercial value of device compatibility and OEM certification pathways. ( https://www.nipro-group.com/en)
- B. Braun Melsungen AG (Melsungen, Germany) — B. Braun’s Streamline Airless System and DiaStream product families highlight differentiation through safety and handling features. However, recent events require careful monitoring: in April 2026, an Urgent Medical Device Correction was issued for certain Streamline Airless System and Low Volume bloodlines due to potential microbubble and leakage risks, illustrating how product quality events can create immediate reputational and supply disruptions. ( https://www.bbraun.com)
- Fresenius Medical Care AG (Bad Homburg, Germany) — Fresenius groups product and service strategies, offering integrated blood tubing solutions like the CombiSet SMARTECH, and often bundles disposables with machine sales and service agreements. Their playbook demonstrates how vertical integration and service contracts can create stickiness in buyer relationships. ( https://freseniusmedicalcare.com/en)
Implications: product differentiation (safety, air elimination, low priming volume), machine interoperability, and field support are decisive commercial levers. Quality incidents — even when resolved quickly — can shift procurement toward alternate suppliers or longer qualification processes, amplifying the importance of robust post-market surveillance and rapid field corrective action capability.
Strategic playbook for 2026
- Supply resilience and cost control: Diversify polymer and connector sources, qualify secondary sterilization partners, and build safety stock for critical SKUs. Use the forecast model to stress-test gross margin under raw-material shocks and sterilization pricing changes.
- Regulatory-first product development: Prioritize designs that reduce microbubble risk, ease of priming, and simplified labeling to shorten 510(k) cycles. Invest early in biocompatibility and sterilization validation to avoid costly post-market actions.
- Commercial packaging and contracting: Design bundled offers that tie bloodline sales to service, warranties, or training for dialysis staff — emphasizing total cost-of-use rather than per-set price alone.
- Tender and regional go-to-market: Tailor contract terms by buyer type (chain dialysis centers vs. independent hospitals) and incorporate supply assurance clauses and rapid field-replacement commitments into bids.
- M&A and partnerships: Target niche technology providers (e.g., microbubble mitigation, smart sensors), regional CMOs with validated sterile capacity, or distributors with deep access to dialysis clinic networks.
- Quality and communications: Strengthen post-market surveillance and communications protocols. The April 2026 corrective action by a major supplier underscores how quickly public trust and procurement patterns can pivot following a safety advisory.
How PW Consulting helps execute
Our deliverable is more than a slide deck. We provide an integrated toolkit: an editable financial model with baseline and alternate scenarios; a supplier map with qualification checklists; tender-play templates; a regulatory timeline with required testing and documentation; and a prioritized action matrix for immediate (0–6 months), medium (6–18 months), and strategic (18–36 months) initiatives. All findings are backed by primary interviews with procurement leads, OEM engineers, and sterilization specialists, cross-checked against regulatory filings and publicly available alerts.
Closing — the strategic choice for 2026
For executives planning resource allocation in 2026, the choice is not binary between cost leadership and product innovation. In a market with modest topline growth, concentrated supplier dynamics, and strict regulatory gates, winning strategies will blend disciplined cost engineering with clear, verifiable safety differentiation and supply resilience. PW Consulting’s full Blood Tubing Set Market report provides the granular segmentation, contract templates, supplier risk scores, and model outputs that enable those strategic choices. We have intentionally withheld the detailed segment-by-region and application-level breakdowns from this preview; those granular insights and the downloadable forecast workbook are available in the full report on our portal.
To move from competitive awareness to operational readiness in 2026, stakeholders need a playbook that connects regulatory timelines, procurement cycles, and manufacturing levers — exactly what our study delivers. Contact PW Consulting or visit the full report page to access the complete dataset, scenario models, and supplier diligence materials.
For detailed analysis of this topic, please visit the official page: Blood Tubing Set Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


