



PW Consulting: AAC Market to Grow at 6.98% CAGR (2026–2032)

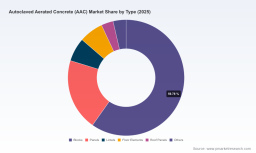
Autoclaved Aerated Concrete (AAC) Market: Strategic Imperatives for 2026 — A Preview
Executive snapshot
Autoclaved Aerated Concrete (AAC) sits at an inflection point. Between 2020 and 2025 the global AAC market expanded steadily, rising from roughly USD 178.5 Million to USD 227.8 Million (base year 2025). Our forecast model projects continued momentum through the 2026–2032 horizon, with a compound annual growth rate of approximately 6.98%, driving the market to roughly USD 359.4 Million by 2032 under the base case. These macro dynamics — steady demand growth, evolving regulation, and supply-side stress — create a landscape where near-term choices (capex, supply agreements, product mixes) will materially affect total returns over the next five years.
Autoclaved Aerated Concrete (AAC) Market
Why this preview matters to executives in 2026
- Validate or challenge current investment plans: The market’s mid-single-digit CAGR supports growth-oriented capital allocation, but timing and geography of capacity additions will determine IRR.
- Price and margin protection: Input volatility — notably cement and lime — has already pressured margins episodically; procurement and hedging strategies are now strategic priorities.
- Regulatory-driven demand swings: Energy codes and low-carbon policies are materially shifting specification choices in construction procurement, accelerating adoption in some markets and creating adoption barriers in others.
- M&A and partnership decisions: Moderate-to-high concentration at the top tiers of the industry points to attractive consolidation opportunities — but value capture requires disciplined target screening.
What the full PW Consulting AAC Market Study delivers (practical, transaction-ready outputs)
The full report is designed for commercial leaders, corporate strategy teams, and private equity investors who need executable intelligence, not just descriptive statistics. Key deliverables include:
Autoclaved Aerated Concrete (AAC) Market
- Top-down and bottom-up market sizing with transparent assumptions (historical 2020–2025 calibration and 2026–2032 scenario funnels).
- Demand-driver heatmaps by policy, construction segment, and technology adoption curves to prioritize markets and product formats.
- Supply-side cost models that isolate the impact of cement, lime and supplementary inputs on manufacturing economics, with sensitivity testing for commodity shocks and carbon-pricing scenarios.
- Regulatory impact analysis (building codes, green certification requirements, waste and fly ash policies) translating compliance into unit demand and specification shifts.
- Competitor landscape and capability matrices to support buy/sell-side diligence, including plant-level capacity, licensing models, and route-to-market footprints.
- Deal origination playbook: acquisition screens, valuation multiples observed in comparable transactions, integration risk checklists and quick-win synergies.
- Commercial growth playbook: product bundling, channel partnerships, specification roadmaps for architects and developers, and pilot frameworks for modular construction strategies.
- Risk & resilience framework: supplier concentration analysis, procurement hedges, inventory strategies, and contingency playbooks for seasonal cement price spikes.
Competitive landscape — positioning and strategic takeaways
The market features an assortment of legacy manufacturers, regional champions, licensed-technology providers, and new entrants. A handful of established players account for a majority share at the top end of the market, creating a competitive environment where scale, technology access, and distribution reach matter.
Autoclaved Aerated Concrete (AAC) Market
- Legacy North American producers: Long-tenured manufacturers with deep project references and established distribution channels retain pricing power in their home markets. Their strengths are brand recognition, developer relationships, and operational know-how for blocks and panels.
- Technology licensors: Firms that offer production technology and licensing know-how enable rapid market entry for new plants while monetizing intellectual property. Licensing models reduce upfront capex for entrants but create a dependency on technology partners for process improvements.
- Regional scale players and recent capacity expansions: Recent capacity expansions and new product launches by regional producers have materially changed competitive dynamics in several markets. These moves create near-term pressure on utilization rates but also accelerate market education and specification adoption.
- Distributors and project-focused specialists: A cohort focused on distribution, system integration, and end-user support is expanding the product footprint into retrofit and modular construction segments — areas where specification and logistics add value beyond commodity pricing.
For dealmakers, the implication is clear: targets should be evaluated not only on current volumes, but on their channel access, specification credentials with architects/developers, and the flexibility of their manufacturing footprint to switch between blocks, panels and engineered elements.
Notable recent moves and what they signal
- Capacity expansion by a regional manufacturer completed in late 2024 doubled production capability at a strategic factory, demonstrating operators’ willingness to back demand growth with tangible asset investments.
- New product introductions from a cement producer in 2025 underline the convergence between raw-material suppliers and finished-product manufacturers — signaling vertical integration and product diversification as active strategic paths.
- New green-building regulations and building-code enforcement in several advanced markets are already influencing procurement committees to favor AAC for thermal performance and embodied-carbon considerations.
Material and regulatory dynamics that will shape 2026 decisions
Cement and lime remain the dominant input cost drivers for AAC production. Recent seasonal cement price surges and ongoing volatility have resulted in compressed margins for many producers, particularly where pass-through is delayed by procurement contracts. At the same time, policy levers — from fly ash substitution strategies in some jurisdictions to stricter energy codes in others — are reshaping the inputs mix and the lifecycle emissions profile of AAC.
- In markets where fly ash substitution is enabled, embodied-carbon reductions and raw-material cost relief can materially improve the business case for AAC adoption.
- Green building certification requirements and energy-code compliance (e.g., country-level thermal performance mandates) are increasing AAC specification wins in new construction and certain retrofits.
- Conversely, regions exposed to cement-supply shocks or logistical bottlenecks will see slower margin recovery unless producers adopt hedging, vertical integration, or alternative binders.
Strategic playbook for 2026 — recommended moves for executives
Based on our modelled scenarios and competitive analysis, PW Consulting recommends a tiered action plan for companies and investors entering or scaling in the AAC market in 2026:
- Immediate (0–12 months): Secure long-term raw-material contracts with indexed pricing clauses; prioritize small, high-impact pilots with developers to convert specification inertia into demonstrable performance cases; and run stress tests on working capital under commodity price swings.
- Near-term (12–36 months): Evaluate selective capacity additions aligned with regional demand signals; pursue licensing or JV arrangements to accelerate market entry where green codes are tightening; implement product modularization pilots that reduce onsite labor and logistics costs.
- Mid-term (36+ months): Consider M&A focused on acquiring channel access, specification leadership, or complementary product lines (e.g., engineered panels, lintels, floor/roof elements) to capture higher-margin system sales rather than only commodity blocks.
Decision-support tools included in the complete study
The full PW Consulting report equips decision-makers with practical tools: scenario-based valuation models, plant-level break-even calculators, a supplier-risk heatmap, and a prioritized list of intervention levers (procurement, product, policy engagement) with quantified impact on EBITDA under multiple commodity and policy scenarios.
Closing: what to expect if you act (and what you miss if you don’t)
For market participants who align strategy with the structural drivers highlighted in this preview — regulation, raw-material dynamics, and modular construction trends — the projected growth offers a clear runway for profitable expansion. Those who delay or treat AAC as a purely tactical product risk being outpaced by better-capitalized and more integrated competitors as specifications and supply chains tighten.
This preview is a strategic teaser: it demonstrates the depth of analysis and the practical tools PW Consulting provides, while reserving detailed segmentation, plant-level economics, and the full competitor scorecards for the comprehensive report. For executives preparing 2026 budgets, M&A pipelines, or procurement strategies, the full study will convert the high-level signals above into concrete, executable decisions.
Next steps
- Request the full report to access the granular segmentation models, regional demand curves, and downloadable valuation and scenario tools.
- Set up a 60–90 minute strategic briefing with our industry team to map these insights onto your specific portfolio or investment thesis.
For detailed analysis of this topic, please visit the official page: Autoclaved Aerated Concrete (AAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


