



PW Consulting: Nitrocellulose Market to Grow at 5% CAGR Through 2032

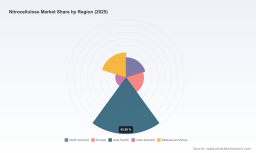
Nitrocellulose Market — Strategic Brief for 2026 Decision‑Makers
Executive snapshot
By the end of the 2025 base year, the global nitrocellulose market had recovered from pandemic-era disruption and structural raw‑material shocks, reaching an estimated USD 1,030 Million in annual revenue. Our model projects a steady acceleration through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of approximately 5.0%, taking the market toward the USD 1.45 Billion range by 2032. This trajectory captures the interplay of steady end‑use demand in coatings, inks and speciality finishes, episodic defence procurement, and increasingly volatile upstream feedstock dynamics.
Nitrocellulose Market
Why 2026 is a pivotal year
-
Price and input shock normalization vs. structural reset: 2024–2025 saw sharp input cost movements (notably cotton linter shortages) that materially raised production costs and forced a series of price pass‑through actions among major converters. While some price pressure is cyclical, our scenarios show a new baseline cost structure that buyers and producers must adopt in 2026 planning cycles.
Nitrocellulose Market -
Geopolitics and defence demand are reshaping supply priorities: Reallocation of capacity toward defence and energetic applications — along with strategic acquisitions to secure feedstock — has created localized shortfalls for industrial grades in several jurisdictions. Procurement teams should expect intermittent tightness in at‑risk supply corridors.
Nitrocellulose Market -
Regulatory and safety testing expectations have hardened: Stability and classification testing (including established methods accepted by global authorities) now factor into sourcing and certification timelines. Compliance lead times must be built into supplier qualification programs.
-
Market concentration with room for disruption: The market remains moderately concentrated (CR3 ≈ 40%, CR5 ≈ 55%), which creates both risk—through supplier bottlenecks—and opportunity, as well‑capitalized players execute capacity expansions and M&A to capture premium segments.
Key market dynamics you must plan for in 2026
-
Raw material sensitivity: Even single‑digit percentage swings in cotton linter availability translate into outsized margin impacts across the value chain. Our sensitivity matrices in the full report quantify break‑points where suppliers will either absorb costs, pass them to customers, or curtail volumes.
-
Pricing volatility: Across 2025, we observed double‑digit month‑over‑month spikes in some regional price benchmarks and very large year‑over‑year increases in other markets. That volatility is likely to persist into 2026 in the absence of coordinated inventory and sourcing strategies.
-
Segmentation nuance matters: Demand drivers and margin structures differ sharply between industrial lacquers, printing inks, nail and cosmetic finishes, and energetic grades. Tactical choices—e.g., prioritizing industrial customers versus defense contracts—will materially affect supply risk exposure and working capital requirements.
-
Sustainability and certification as commercial differentiators: Buyers increasingly require suppliers to demonstrate lifecycle credentials. Recent certifications by leading producers are already being used as commercial leverage in contract negotiations.
What PW Consulting’s Nitrocellulose Market Report delivers (practical, actionable modules)
-
Integrated market model: a calibrated, year‑by‑year demand and supply model spanning 2020–2032, with scenario toggles for raw‑material shocks, defence procurement surges, and regulatory constraints. (Note: granular region/application line items are included in the report; this brief intentionally omits those splits.)
-
Price sensitivity toolkit: breakpoint analyses and pass‑through thresholds tailored for procurement and commercial teams; ready‑to‑use negotiation playbooks indexed to supplier archetypes.
-
Supplier risk matrix: quantified exposure scores for capacity, geographic concentration, raw‑material sourcing and compliance lead times, enabling rapid short‑listing of alternative suppliers.
-
M&A and capex playbook: prioritized target profiles, valuation multiples observed in recent transactions, and a risk‑adjusted return model for greenfield vs. bolt‑on expansion — built for C‑suite decision scenarios in 2026.
-
Regulatory and safety roadmap: implications of current classification and testing standards for lead times, on‑boarding and cost of goods, with recommended compliance checkpoints for procurement and quality departments.
-
Sustainability monetization guide: how to translate certifications and lifecycle claims into commercial premiums and preferred supplier status with large customers.
Competitive landscape — who matters and why
The supply map is global and heterogeneous, mixing specialist producers with converters and diversified chemical houses. The following firms are strategically important either because of capacity, vertical integration, geographic reach, or recent strategic moves:
-
Nitrocellulose Group (Thailand) — A large regional producer with industrial product forms serving inks and coatings; notable for manufacturing scale in Asia and for being a reliable regional supplier for converters seeking stable granular and fibrous grades.
-
GRN Cellulose Pvt. Ltd. (India) — A vertically capable producer with both powder and solution forms, active across paints, lacquers, inks and specialty applications. Their diversification across form‑factors makes them an attractive partner for formulators.
-
Companhia Nitro Quimica Brasileira (Brazil) — A global producer with modern facilities and a footprint that matters for Latin American supply resilience, particularly when northern hemisphere supply tightness emerges.
-
Rheinmetall NC GmbH (Germany) — Following the 2025 acquisition of a European incumbent, Rheinmetall’s NC operations are strategically positioned to service energetic and defence markets, and their move underscores defence‑led vertical consolidation.
-
Synthesia Nitrocellulose (Czech Republic) — A European energetic and industrial supplier that has expanded capacity after strategic restructuring; crucial where European buyers need proximate supply for propellants and industrial uses.
-
Major Chinese suppliers (multiple companies) — A cluster of manufacturers supplying film‑forming resins and industrial NC across coatings, inks and adhesives. These players drive cost competition at the global level and are key levers for buyers pursuing low‑cost sourcing.
-
Specialist converters and chemical partners (Europe, North America) — Firms that blend, formulate and add value (including sustainability credentials) to nitrocellulose products; they are often the price setters for finished goods and therefore focal points for downstream risk management.
Recent industry moves you cannot ignore (selected, directional)
-
Strategic acquisitions to secure supply: a notable defence‑oriented acquisition completed in 2025 underscores how state and defence procurement priorities can reallocate capacity away from industrial markets.
-
Input cost pass‑throughs: major global converters have applied price increases on nitrocellulose‑containing products in 2025/26 cycles, reflecting persistent upstream cost inflation and forcing commercial teams to reassess pricing governance.
-
Supply additions tied to defence: announcements of production commencements in Europe to solve artillery and propellant demand point to segmented capacity that may not be fungible for industrial buyers.
-
Sustainability certifications as a competitive lever: recent certifications obtained by select producers are already being used to win preferred supplier status with formulators and brands prioritizing lifecycle footprints.
Strategic implications and recommended 90‑ to 180‑day moves for 2026
-
Update procurement playbook: embed our price‑sensitivity thresholds into contract templates, set indexed pricing clauses tied to agreed raw‑material baskets, and create rolling 90‑day supplier reviews for at‑risk categories.
-
Shortlist dual‑sourcing candidates: target a mix of regional and low‑cost suppliers to balance security and margin pressure; prioritize suppliers with validated certifications and acceptable compliance lead times.
-
Inventory and working‑capital triage: apply our scenario outputs to determine tactical safety stock levels for critical SKUs and build conditional release rules linked to price windows and supply signals.
-
Commercial renegotiation and cost‑to‑serve reviews: use the report’s cost breakdowns to reframe commercial conversations with converters, seeking longer notice periods for price moves and partial cost absorption mechanisms where strategic.
-
Capex and M&A screening for 2026: if your strategy involves vertical integration or securing feedstock, use our M&A playbook to prioritize assets with the best risk‑adjusted returns and the lowest regulatory friction.
How to use this brief and where to get the full intelligence
This brief synthesizes the strategic signals that should inform boardroom and procurement decisions in 2026. PW Consulting’s full Nitrocellulose Market Report contains the granular, transaction‑grade datasets, regional and application splits, supplier scorecards, and downloadable models you need to operationalize these recommendations. To preserve competitive value for clients, the complete section‑level figures and scenario model outputs are available only in the full report.
If your 2026 planning cycle requires hedged sourcing strategies, supplier reclassification, or M&A due diligence, the full report supplies ready‑to‑deploy templates and a calibrated market model. PW Consulting can also deliver executive workshops and bespoke scenario runs tailored to your exposure profile.
For detailed analysis of this topic, please visit the official page: Nitrocellulose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


