



AI in Agriculture: Market Set to Expand at 22.85% CAGR — PW Consulting

Artificial Intelligence in Agriculture Market: Strategic Imperatives for 2026 Decision‑Makers
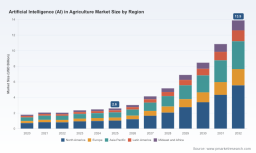
As agribusinesses, equipment OEMs, technology vendors and public-sector leaders enter 2026, the AI in agriculture market is shifting from experimental pilots to enterprise-scale deployments. Our PW Consulting baseline finds the market valued at USD 2.6 Billion in 2025 and accelerating rapidly: modeled growth to USD 13.9 Billion by 2032 at a compound annual growth rate of 22.85% underscores both the scale of the opportunity and the urgency of strategic action in the next 12–18 months. This executive introduction summarizes the report’s practical value for corporate strategy, investment prioritization, and implementation roadmaps — while preserving the report’s proprietary segment-level detail to guide readers to the full study for transaction‑grade intelligence.
Artificial Intelligence (AI) in Agriculture Market
Why this report matters for 2026 strategic decisions
-
Timing decisions: 2026 is a hinge year. Technology maturity, regulatory guidance and capital availability are converging — creating windows for first‑mover advantage in core farm-management and automation services.
Artificial Intelligence (AI) in Agriculture Market -
Resource allocation: The report translates broad market momentum into actionable capital deployment plans — clarifying where to allocate R&D, M&A, and go‑to‑market spend to accelerate ROI.
Artificial Intelligence (AI) in Agriculture Market -
Partnership and ecosystem strategy: The landscape is multi‑layered — OEMs, cloud platforms, crop‑science firms and niche AI specialists are all competing and co‑creating. Our analysis helps firms choose when to partner, when to buy and when to build.
-
Regulatory and data governance readiness: With evolving frameworks from regional authorities and federal initiatives for agricultural AI, the ability to demonstrate accountable, explainable AI will be a contract and compliance differentiator.
What the report delivers — practical, operational intelligence
-
Market sizing and scenario planning: A rigorous bottom‑up market model (historical 2020–2025 base, forward forecasts 2026–2032), with alternative adoption scenarios tied to key technology, regulatory and commodity price inflection points.
-
Use‑case ROI playbooks: Field‑tested templates for precision farming, crop health monitoring, autonomous equipment, irrigation optimization and livestock monitoring — each with unit economics, payback sensitivities and scaling checklists.
-
Vendor evaluation framework: A decision matrix that scores vendors on technical fit, data interoperability, deployment risk, and commercial terms — designed for procurement and piloting teams.
-
Deployment blueprints: Integration architectures for cloud‑edge‑sensor stacks, reference implementation for data pipelines, and an operations guide for moving from pilot to fleet‑level orchestration.
-
Regulatory & risk playbook: Practical templates to operationalize compliance with regional AI guidance, agricultural safety rules and data‑sharing agreements, including clauses for model transparency and ethical use.
-
Case studies and supplier diligence: Real-world deployments across farm sizes and crop systems, plus a diligence checklist for investment teams evaluating target companies or technologies.
Market dynamics shaping strategic choices
-
Macro demand drivers: Food security pressures, sustainability targets, and persistent labor shortages are pushing farm operators to deploy AI solutions that reduce input waste, close labor gaps, and lift yield per hectare.
-
Infrastructure and cost realities: Field‑level data collection requires capex — IoT sensors, solar‑powered connectivity and edge compute introduce meaningful upfront cost. Our report models these infrastructure vectors and their impact on TCO across farm archetypes.
-
Regulatory momentum: Policy frameworks in major markets are maturing — coordinated AI plans and federal strategies are introducing standards for transparency, accountability and dataset benchmarking. Organizations must design AI governance into product roadmaps to avoid deployment delays and procurement exclusions.
-
Standards and dataset benchmarking: New initiatives to standardize agricultural machine learning datasets and evaluation benchmarks are reducing model development risk but will favor players who contribute to and adopt common data formats and APIs.
-
Technology stack evolution: Advances in computer vision, machine learning, multispectral/hyperspectral sensing, and autonomous robotics are deepening value capture but shifting the economics from one‑off hardware sales to recurring data and analytics subscriptions.
Competitive landscape — strategic positioning of key players
The competitive environment is differentiated by capability clusters rather than single‑player dominance. Four archetypes emerge, each with distinct implications for partnerships and market entry.
-
Integrated equipment OEMs: Established agricultural machinery manufacturers are embedding AI into autonomous guidance, precision application and fleet telematics. Their strength lies in hardware integration and dealer networks; their challenge is transitioning to service and software economics. Strategic action: pursue OEM partnerships for field trials, insist on open data access and anticipate bundled commercial models.
-
Cloud and enterprise platform providers: Large cloud vendors are packaging IoT, satellite, and analytics capabilities into farm‑grade platforms that support rapid scaling. These platforms lower the barrier to data aggregation and model training but create vendor lock‑in risks. Strategic action: evaluate hybrid cloud strategies and negotiate interoperability clauses.
-
Ag‑science and input firms: Crop‑science companies are embedding digital agronomy and AI advisory into their product suites to drive yield and input optimization. Their advantage is agronomic data and advisory networks; the tradeoff is impartiality when recommending inputs. Strategic action: structure transparency provisions and independent validation for advisory outputs.
-
Specialist AI and sensing startups: Niche vendors focus on hyperspectral imaging, leaf‑level analytics, and machine‑vision driven disease detection. These innovators accelerate feature development and often become M&A targets or strategic partners for scale. Strategic action: use targeted investments or partnership pilots to capture innovation while protecting IP and data rights.
Recent market activity validates these archetypes. Notable developments in the last 18 months include strategic startup collaboration programs from major OEMs, cross‑sector partnerships combining generative and agronomic intelligence, consolidation moves among hyperspectral analytics firms, and product launches that expand precision spraying and robotics capabilities. Collectively these events signal accelerated commercialization and increased capital deployment into operational AI systems.
Actionable framework for 2026 decisions
-
Define prioritized business outcomes: Translate broad ambitions (e.g., sustainability credentials, labor reduction, yield uplift) into quantifiable KPIs that will drive vendor selection and pilot metrics.
-
Structure defensible pilots: Design pilots to validate economics at scale — include data maturity assessments, sensor placement plans, and success criteria tied to financial outcomes rather than purely technical benchmarks.
-
Build a data & governance baseline: Adopt standardized schemas and compliance checklists; require vendor commitments for data portability and model explainability as part of contracting.
-
Choose partnering and procurement models: Evaluate tradeoffs between platform adoption, bolt‑on specialist tools, and co‑development. Negotiate commercial terms that align incentives for long‑term data sharing and model improvement.
-
Plan for scale: Use our scaling checklist to budget for sensor refresh cycles, connectivity upgrades and workforce reskilling — and to model the transition from capital expenditures to subscription revenue models.
How to use the full PW Consulting study
The full Artificial Intelligence in Agriculture Market report is designed as a plug‑and‑play strategic toolkit for 2026. It contains the detailed segmentations, regional and application-level analyses, vendor scorecards, transaction compendia, and downloadable financial models needed for board‑level investment decisions, M&A diligence, and product roadmaps. If your team is preparing capex plans, negotiating strategic partnerships, or designing a pilot‑to‑scale program, the full study provides the raw tables, sensitivity analyses and vendor comparisons necessary to execute with confidence.
Final perspective — prioritize speed with discipline
The numbers tell a clear story: rapid market expansion creates both upside for incumbents with scale and acute risk for organizations that delay foundational choices. In 2026, winning requires moving faster than a multi‑year adoption timeline while embedding governance, interoperability and measurable economics into every deployment. PW Consulting’s study equips leaders with the analytical depth to justify investment and the practical templates to operationalize AI across farm systems — while reserving the full, transaction‑grade segmentation and vendor benchmarking for the complete report.
For a hands‑on briefing and access to the core data tables, vendor scorecards and ROI models that underpin these conclusions, please consult the full PW Consulting Artificial Intelligence in Agriculture Market study.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence (AI) in Agriculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


