



PW Consulting: Billet Casters Market Set for 5.5% CAGR to 2032

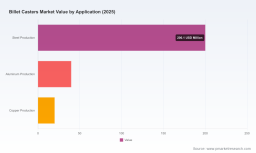
Billet Casters Market: Strategic Outlook for 2026 — A PW Consulting Executive Brief
As industrial supply chains and heavy-metal metallurgy enter a new phase of modernization, the billet casters market presents a blend of enduring capital intensity and differentiated technological trajectories. This PW Consulting industry brief previews our comprehensive Billet Casters Market report (base year 2025, historical 2020–2025, forecast 2026–2032). Below we synthesize the high-level market trajectory, the decision-relevant findings our full study provides, and the strategic questions every procurement, engineering, and M&A team should be asking in 2026. This is an executive “trailer”: we demonstrate analytical depth and the report’s practical value while reserving detailed segment tables and project-level models for the full publication.
Billet Casters Market
Why this market matters for 2026 decision-making
Billet casters sit at the intersection of metallurgy, process automation, and heavy equipment investment. Our top-line sizing shows the market expanding materially through the 2020s — growing from around USD 200 Million in 2020 to approximately USD 260 Million by 2025 and projected to approach USD 376 Million by 2032. The forecast period (2026–2032) reflects a compound annual growth rate of 5.5%, driven by replacement cycles, upgrades for higher-alloy and larger-section capabilities, and continued mini-mill expansions that favor modular, compact caster platforms.
Billet Casters Market
For executives making capex, sourcing, or product roadmap choices in 2026, that trajectory has three practical implications: (1) timing matters — early investment in modernization yields a differentiated yield on product quality and throughput; (2) supplier selection is strategic — a relatively concentrated supplier base means technological and after-sales capabilities are decisive; and (3) total project economics go well beyond the machine price — civil works, integration, and operating performance shape lifecycle returns.
Billet Casters Market
What our full report delivers (practical, operational content)
- Actionable market sizing and forecast model at the industry level (base year 2025; historical series 2020–2025; forecast 2026–2032), including sensitivity scenarios for alloy demand, energy cost shocks, and mini-mill adoption curves.
- Capital and lifecycle cost frameworks: comprehensive capex/opex templates that map machine category (modular vs. high-end multi-strand) to expected total project outlays, commissioning timelines, and NPV breakeven under several throughput profiles.
- Technology dossiers that compare vertical, horizontal and curved caster architectures across quality outcomes (inclusion control, internal soundness), casting speed envelopes, and retrofit friendliness.
- Supplier benchmarking: capability matrices that evaluate engineering depth, global service footprint, spare-parts lead times, and digitalization maturity — essential for risk-weighted procurement.
- Regulatory and compliance playbook: certification requirements for ultra-large sections and high-alloy grades, and a checklist for contracting competitive warranty and performance guarantees.
- Practical procurement tools: RFQ templates, scoring rubrics, and a phased acceptance test plan tailored for multi-strand high-end machines.
Market structure and concentration — what to infer
The market exhibits moderate-to-high concentration: the top three suppliers account for a majority share of installed high-end capacity, and the top five extend that dominance further. For buyers this creates both risk and opportunity. On one hand, incumbent vendors with decades of metallurgical know-how and global spares networks command pricing power for premium configurations. On the other, their dominance means differentiated niche vendors can win by focusing on modularity, short lead-times, or highly localized service models.
Competitive landscape — core players and recent strategic moves
Our competitive analysis focuses on suppliers that shape technology trajectories and service expectations. Below are high-level profiles and notable developments that underscore strategic positioning in 2025–early 2026:
- SMS group GmbH (Düsseldorf, Germany) — A legacy engineering house with deep capabilities in complex billet caster designs (multi-strand, vertical and curved). SMS has been active on modernization projects, delivering advanced mechanical soft-reduction and quality-focused retrofits that target internal billet soundness.
- Danieli & C. Officine Meccaniche S.p.A. (Buttrio, Italy) — Known for integrated plant solutions and oscillation technologies that prioritize surface and internal quality for demanding grades. Danieli continues to secure orders for ultra-large, high-alloy billet lines and runs a service organization focused on upgrades and lifecycle support.
- Primetals Technologies (London / global) — With modular offerings aimed at mini-mill and rebar-integrated operations, Primetals builds systems optimized for square/rectangular sections and high-speed downline integration. Its ownership structure and Indian manufacturing footprint reinforce competitiveness in price-sensitive retrofit segments.
- Electrotherm E&T Ltd. (Ahmedabad, India) — A specialist in compact, modular casters suitable for induction-melt shops and ingot-to-billet conversions; attractive where footprint and small heat sizes are constraints.
- Concast India Private Ltd. (Primetals subsidiary) — Focused on delivering modular 5–7 strand solutions to domestic mini-mills, emphasizing quick delivery and integration with existing rolling lines.
Notable recent developments (indicative, non-exhaustive) illustrate how competition is unfolding: large orders for ultra-large section lines and modernization contracts for multi-strand casters signal sustained demand at the high end, while modular suppliers continue to capture mini-mill retrofit opportunities. These contrasting deal types — high-capex flagship projects versus compact, rapid-delivery modular machines — define two parallel competitive plays in 2026.
Cost, input risks, and project economics
Project procurement teams should treat machine price as the start, not the finish, of evaluation. Our analysis synthesizes industry cost composition and identifies the cost buckets that matter most in negotiation and lifecycle assessment:
- Raw material content (high-grade alloy steels, refractory parts, copper mold components) typically comprises a material portion of the machine bill of materials; supply-chain volatility in these inputs directly transmits into lead-time and price risk.
- Precision fabrication, welding and hydraulic/electromechanical integration are significant labor-intensive cost drivers; these activities also determine field reliability and commissioning duration.
- R&D, certification, and metallurgical process validation—especially for high-alloy grades and ultra-large sections—add a non-negligible premium and can extend project timelines if not planned early.
- Advanced multi-strand machines with electromagnetic stirring and dynamic cooling command premium pricing and deliver superior rolling yields; lifecycle returns depend on alloy mix, scrap reduction and downstream rolling yield improvement.
- Typical total greenfield project costs for high-end caster installations can cross substantial capital thresholds once civil works and ancillary equipment are included; even modular projects have non-trivial integration costs.
Opportunities, risks and strategic moves for 2026
We identify three near-term strategic plays where companies can extract disproportionate value:
- Quality-led differentiation — For producers targeting premium alloy markets, investing in advanced caster features (soft reduction, electromagnetic stirring, dynamic cooling) converts directly into downstream premium pricing by reducing internal defects and improving tensile/creep performance for critical grades.
- Modularity and speed-to-market — Mini-mill operators and retrofit projects prioritize compact, modular casters with short lead times; OEMs that standardize modular platforms and spare-parts kits will win these high-velocity deals.
- Service and lifecycle contracting — Given the concentration of supplier capability, extended service contracts, predictive maintenance packages, and performance guarantees are becoming negotiation levers; buyers should quantify the present value of uptime and quality improvements when choosing suppliers.
Key risks that could materially alter the 2026–2032 outlook include sustained spikes in energy prices, an unexpected slowdown in construction of long steel plants, or trade-policy changes that disrupt raw-material flows. Conversely, rising demand for high-alloy sections in power-generation and petrochemical applications could accelerate high-end machine orders beyond our base-case forecast.
How to use the full PW Consulting report
Our full Billet Casters Market study is designed as a working tool for procurement teams, plant engineers, strategy groups, and investors. It includes downloadable models, an RFQ checklist, supplier scorecards, and scenario-capable financial models that allow you to stress-test purchase decisions under alternative alloy-mix and throughput assumptions. The report also contains detailed segmentation tables and granular regional/application breakdowns that are intentionally withheld in this preview — these are essential inputs for deal-level decisions and are available via the report portal.
Methodology note
The study uses a 2025 base year with historical tracking from 2020–2025 and a forecast horizon of 2026–2032. Market sizing blends bottom-up equipment shipments, validated order-intake data, and capital expenditure signals from steel producers; sensitivity scenarios model alloy-demand elasticity, project-level capex variation, and vendor-market-share displacement. Concentration metrics reported in the study reflect installed base and recent order flows and are summarized at the top-line level in this brief.
Next steps for readers
- If you are evaluating a caster purchase or upgrade in 2026, map your decision against the report’s capex/opex templates and request the supplier scorecards to build a risk-weighted shortlist.
- For M&A or investor diligence, use the scenario models in the full report to simulate demand shocks and to quantify integration value from spare parts and service-platform consolidation.
- To operationalize improvements in yield and quality, deploy the report’s technology dossiers and commissioning checklists during vendor selection and FAT/SAT negotiations.
PW Consulting’s Billet Casters Market study provides the actionable intelligence that industrial leaders need to make defensible, value-accretive decisions in 2026. For access to the full data tables, supplier scorecards, and downloadable financial models, please consult the report portal where the complete analysis is published.
For detailed analysis of this topic, please visit the official page: Billet Casters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


