



PW Consulting: DOTP Market to Hit USD 3,129M by 2032 with 5.55% CAGR (2026–2032)

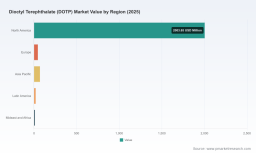
Dioctyl Terephthalate (DOTP) Market — Strategic Outlook for 2026 Decision‑Making
Executive preview
As companies prepare capital, sourcing and product strategies for 2026, DOTP is moving from niche replacement chemistry toward mainstream industrial adoption. Our base‑year synthesis (2025) frames a market that has expanded from an estimated USD 1,631.5 million in 2020 to roughly USD 2,150 million in 2025, and—under our central forecast—continues to grow at a compound annual growth rate of about 5.55% through the 2026–2032 window to reach nearly USD 3,129 million by 2032. Those headline numbers understate the complexity behind supply chains, regulatory pressure, and product differentiation that will determine winners and losers over the next 18–36 months.
Dioctyl Terephthalate (DOTP) Market
Why this research matters for decisions you must make in 2026
-
Timing: Procurement cycles, contract renegotiations and planned capacity projects initiated in 2024–25 will come to a head in 2026. Strategic clarity on supply, duty exposure and product-spec compliance will materially affect COGS and market access.
Dioctyl Terephthalate (DOTP) Market -
Regulatory turnarounds: DOTP’s broad confirmation for food‑contact and medical indirect uses under major frameworks provides commercial opportunity — but also requires rigorous documentation and supplier qualification to realize value without unexpected recalls or non‑compliance costs.
Dioctyl Terephthalate (DOTP) Market -
Competitive positioning: The industry is mid‑consolidation. Leading producers combine differentiated feedstock strategies, technical grades and route‑to‑market strength. Understanding concentration and capability is a prerequisite to commercial planning and M&A prioritization.
Market dynamics shaping DOTP through 2026
-
Demand substitution and end‑use adoption: Industry momentum toward non‑phthalate plasticizers has driven broad adoption across flexible PVC, cables, automotive interiors and packaging. This is a structural trend rather than a short impulse; manufacturers that secure qualified DOTP supplies and fast‑track compatibility testing will capture outsized value.
-
Regulatory and trade signals: Two sets of developments materially alter the trade and pricing environment. First, DOTP has been explicitly affirmed compatible with FDA 21 CFR 177.2600 migration rules and EU REACH for relevant food‑contact and medical uses, creating a pathway for food/medical applications where documentation and chain‑of‑custody matter. Second, trade enforcement activity in the U.S. — including antidumping investigations and a subsequent determination of material injury for certain DOTP imports — introduces duty and quota risk that can re‑route volumes and raise landed costs for U.S. buyers. Firms active in North American supply chains must build duty‑scenario contingencies into 2026 contracts.
-
Feedstock and cost structure dynamics: The chemistry is straightforward but the economics are sensitive to PTA and 2‑ethylhexanol (2‑EH) availability and pricing. Stoichiometrically, about 1.000 kg of PTA combined with 1.568 kg of 2‑EH produces roughly 2.352 kg of DOTP per theoretical ton basis — a simple fact that can be modelled into per‑ton cost curves, yield assumptions and working capital needs. Vertical integration or preferred sourcing of 2‑EH (or captive production) is a clear defensive move for producers seeking margin protection.
-
Supply concentration and investment cadence: The market shows moderate concentration at the top (our CR3 and CR5 metrics signal that the top suppliers together control a meaningful portion of capacity without offering monopoly pricing). That structure supports selective pricing power but also generates vulnerability: a single plant outage, capacity ramp or regulatory action can move regional balances rapidly. New product introductions and incremental capacity announcements by established players indicate an environment of measured expansion rather than a free-for-all buildout.
-
Technology and grade segmentation: Producers differentiate by purity, volatility, and thermal performance (e.g., high‑temperature grades for cable applications vs. high‑compliance grades for food/medical). Customers who require cross‑grade qualification early can avoid costly reformulations down the line.
Competitive landscape — what matters to buyers, integrators and investors
Across global suppliers, we observe distinct strategic postures:
-
Producers with technical‑grade offerings and flexible delivery (drums, totes, bulk) position themselves as reliable contract suppliers for film, sheet and conventional PVC downstream processors. Their commercial playbook emphasizes fast qualification and supply flexibility.
-
Large regional players that control upstream feedstock (or dedicated esterification lines) can protect margin via integrated supply and higher technical reliability for high‑spec applications such as cables and automotive interiors.
-
Specialist manufacturers focused on regulatory compliance and product stewardship target food‑contact and medical markets where traceability and certification unlock price premiums and long‑term contracts.
Representative company developments illustrate these dynamics: a major EU producer has celebrated a decade of its flagship DOTP brand while confirming stable production and feedstock integration; a technical supplier in Italy has introduced a higher‑performance DOTP grade for flexible packaging; several Chinese suppliers emphasize high‑temperature and bulk supply for cable and synthetic leather markets. Each move should be evaluated through the lens of your 2026 procurement timeline, technical acceptance windows and cross‑border trade exposure.
What the PW Consulting DOTP report contains — operationally actionable deliverables
We designed this study to move beyond thematic commentary into executable guidance for 2026 decisions. The report bundles the following tools and outputs, each built on primary interviews, plant‑level capacity mapping, trade flow reconstruction and modeled price scenarios:
-
Forward demand engine to 2032 with scenario branches for high substitution, duty‑shock and slower adoption — built to integrate customer‑side product qualification timelines.
-
Supplier scorecards and capacity overlays that link technical grade, feedstock integration, geographic footprint and delivery modality to commercial risk indicators.
-
Bottom‑up cost‑to‑produce models (PTA/2‑EH linkage), logistics and landed cost calculators so buyers can simulate supplier bids under multiple duty scenarios and freight shocks.
-
Regulatory matrix and trade‑policy heatmap that flags jurisdictional compliance thresholds and antidumping/duty exposure for sourcing strategies.
-
Commercial playbooks and contract language templates for 12–36 month offtakes, qualification checklists for food/medical use, and a supplier‑diversification decision tree tuned to 2026 planning cycles.
-
M&A and investment screening: target shortlists, valuation sensitivities and a red‑flag checklist for technical liabilities and environmental compliance.
Note: To preserve the strategic value of granular segmentation and proprietary supplier volumes, this preview deliberately omits region‑by‑region and application‑level percentage breakdowns. The full report contains the detailed tables, regional flows and per‑application forecasts necessary for transactional work.
How to use these insights in 2026 — practical recommendations
-
Procurement and sourcing: Lock in multi‑year contracts with flexibility for duty pass‑throughs and put options that reflect likely enforcement scenarios. If your cost model is exposed to PTA/2‑EH volatility, negotiate indexation clauses or co‑sourcing arrangements that include feedstock pass‑through terms.
-
Product and regulatory strategy: Fast‑track DOTP grades requiring food/medical certification with prioritized supplier audits — regulatory compliance is a gatekeeper to premium segments and long‑term contracts.
-
Portfolio and pricing: Create tiered product offerings aligned to grade performance. In parallel, stress‑test pricing models against a 5–8% duty shock (historical outcomes from trade cases provide a reference) to understand margin absorption and end‑customer pass‑through capacity.
-
Capacity and investment: Favor incremental capacity additions or tolling agreements over greenfield builds unless you can secure feedstock and off‑take. Vertical integration into 2‑EH or strategic partnerships with feedstock suppliers materially improves resilience and ROIC.
-
M&A and partnerships: Prioritize targets that close supply gaps (geography or grade) and offer documented regulatory compliance for high‑value applications. Avoid assets with opaque feedstock provenance or unresolved duty exposure.
Final note — what you get from the full PW Consulting study
This executive preview demonstrates the analytical scaffolding and decision levers we use to counsel clients active in the DOTP value chain. The complete study delivers the numeric and scenario granularity you will need to operationalize the recommendations above — including region/application forecasts, supplier volume tables, price trajectories and duty‑scenario P&L impact matrices. We have intentionally withheld those segmented tables here to preserve the report’s marketplace value and to encourage a direct engagement where we can map our findings onto your commercial cadence and risk tolerances.
For procurement teams, product leaders, investors and corporate strategists planning for 2026, the question is no longer whether DOTP will play a pivotal role — it is how you will position your firm to capture margin and protect access. PW Consulting’s full DOTP market study translates that strategic imperative into tactical action plans and modeled outcomes ready for board and transaction use.
For detailed analysis of this topic, please visit the official page: Dioctyl Terephthalate (DOTP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


