



PW Consulting: Media-Based Water Filters Market to Hit USD 27.2B by 2032 (6.69% CAGR)

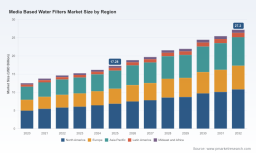
Media-Based Water Filters Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a concentrated strategic preview of our new Media Based Water Filters Market study — designed to orient executive decision-making for 2026 and beyond. This briefing synthesizes the market’s macro trajectory, regulatory and input-cost headwinds, and competitive posture, while preserving the granular segmentation intelligence within the full report to drive demand for the complete dataset and operational playbooks.
Media Based Water Filters Market
Market at a Glance: Growth Trajectory and Structural Signals
The media-based water filters market has shown persistent expansion through the 2020–2025 base period and is positioned for continued growth across our 2026–2032 forecast horizon. On a total-market basis (USD, denominated in billions), the market climbed materially during the historical window and is projected to continue expanding at a steady compound annual growth rate (CAGR) of 6.69% over the forecast period. The dataset underpinning our analysis provides annualized totals from the 2020 baseline through 2032, enabling scenario modeling for CAPEX planning, procurement cycles, and channel investments.
Media Based Water Filters Market
Two high-level implications follow. First, the predictable mid-single-digit CAGR gives procurement and product teams time to phase investments in media technologies and supply chains rather than forcing binary, near-term strategic bets. Second, steady expansion amplifies the value of incremental share gains: given the market breadth, marginal improvements in product differentiation, certification, or service models can compound into meaningful revenue uplifts over multi-year horizons.
Media Based Water Filters Market
Why This Study Matters for 2026 Decisions
- Timing of Investments: With a clear forward growth path, 2026 is the pivot year for converting exploratory R&D and pilot programs into scaled deployments. The study isolates the tactical entry points — product-configurations, certification sequences, and go-to-market models — that minimize time-to-revenue while containing regulatory exposure.
- Risk Calibration: Regulatory and disposal constraints materially affect lifecycle costs and project timelines. Our analysis translates regulatory enforcement vectors and end-of-life obligations into scenario-specific cost multipliers and compliance timelines to inform procurement and capital approval processes.
- Supplier & Contract Strategy: The market’s structure is moderately fragmented (top-three and top-five concentration metrics indicate limited dominance by a handful of players). That fragmentation creates room for incumbents to defend margins via service differentiation and for new entrants to carve niches through specialized media or certification-led propositions.
- Operational Playbooks: The report supplies actionable operational tools — including replacement-interval modeling, backwash scheduling benchmarks, and media disposal routing templates — that facilities operators can apply immediately to reduce OPEX and extend asset uptime.
Key Market Dynamics — What Will Drive Wins and Losses in 2026
- Regulatory Tightening and Certification as a Market Gatekeeper: Standards and guidance such as longstanding FDA controls for water purification components in clinical applications, and evolving certification expectations for drinking-water treatment units, elevate certified product offerings to a premium position. For companies targeting regulated end-markets (healthcare, municipal, and certain commercial verticals), certification timelines and audit-readiness are now strategic bottlenecks.
- Input Cost and Waste Management Pressures: Granular activated carbon (GAC) and other media face both price volatility and regulated disposal regimes. Replacement and disposal costs — along with hazardous-waste permitting in some jurisdictions — should be built into multi-year TCO models rather than treated as one-off line items. Firms that optimize media life, offer take-back or regeneration services, or develop lower-cost recyclable media will realize competitive cost advantages.
- Service & Lifecycle Economics: Typical maintenance rhythms (e.g., periodic backwashing cycles and scheduled media replacement) create recurring-revenue and aftermarket opportunities. Service-led business models — especially those bundling monitoring, predictive maintenance, and consumables — have outsized potential to increase lifetime customer value compared with one-time equipment sales.
- Technology Convergence and Product Differentiation: Advances in redox media, multi-media beds, and hybrid systems that combine adsorption and biological control are closing performance gaps across applications. However, meaningful differentiation increasingly comes from integrated systems thinking — combining media selection, control logic, and maintenance protocols — rather than from single-media claims alone.
Competitive Landscape: Strategic Profiles and Implications
The market is served by a mixture of specialized media manufacturers, systems integrators, and distributors. While the market concentration metrics show the top players do not fully dominate, a small set of firms exerts clear influence through technology ownership, established distribution, and certification pedigrees. The study provides a close look at core firms that exemplify current strategic archetypes:
- Kymera International (United States): A technology-led player whose KDF® redox media underpin water-treatment applications where oxidative control complements adsorption. Their strength is specialized media IP and formulations that address specific contaminant removal challenges.
- Crystal Quest (United States): A portfolio player focused on media and resin manufacturing. Their vertical integration across media production and consumer-facing systems provides flexibility in tailoring product mixes for both aftermarket and OEM channels.
- Pure Aqua (United States): A supplier of multimedia filter systems and packaged media solutions; positioned as a systems integrator across commercial and industrial segments that require turnkey delivery and performance certifications.
- Pentek, Inc. (United States): A manufacturer historically focused on filter media for commercial and industrial applications; their product breadth supports customers that prioritize standardized cartridges and scalable filtration assemblies.
- Pure Water Products, LLC (United States): A regional distributor and specialist in backwashing filter media; plays a critical role in supply continuity, aftermarket resupply, and installation support for service providers.
Strategic takeaways for market participants: incumbents must balance certification investments with targeted technology bets; challengers can attack by bundling lifecycle services and lower-TCO media replacements; and distributors that can offer fast-channel logistics and regulatory-compliant disposal solutions will gain share, especially in fragmented end-markets.
Report Contents — What Practitioners Will Find Inside
The full PW Consulting report is structured to be operationally useful to strategy teams, product managers, procurement leaders, and business development executives. Highlights include:
- Market sizing and trend analysis with annual totals from the historical base through the forecast horizon, enabling scenario-based revenue and unit planning.
- Regulatory and standards matrix mapping relevant controls (clinical-grade water, drinking-water certification, and regional disposal/handling rules), with impact scoring for each end-market and adoption pathway guidance.
- Technology and media taxonomy that organizes media types, performance attributes, lifecycle profiles, and procurement implications without exposing client-specific or sensitive segment shares.
- Operational playbooks: replacement-interval modeling, backwash optimization templates, and vendor selection checklists that translate market intelligence into immediate cost and reliability improvements.
- Competitive profiles and go-to-market archetypes, illustrating where to compete on price, certification, service, or proprietary media blends, and the trade-offs each choice implies for margin and scale.
- Commercial scenarios and risk matrices that combine input-cost volatility, regulatory timelines, and adoption curves to inform three investment confidence levels (conservative, base, and accelerated).
Strategic Recommendations for 2026
- Prioritize Certification Roadmaps: Allocate budget and cross-functional resources to achieve relevant certifications early. For regulated end-markets, certification unlocks premium pricing and preferred-vendor status.
- Design for Lifecycle Advantage: Embed aftermarket service, media regeneration, or recovery programs into your commercial offering. Lifecycle revenue streams stabilize cash flow and create defensibility against purely price-led competition.
- Hedge Input-Price Risk: Negotiate mixed supply contracts, explore media blends that reduce cost-per-cycle, and evaluate circular strategies (regeneration, reclamation) to contain disposal liabilities.
- Segment Go-to-Market by Value Driver: Use a two-track approach: defend margin in high-compliance, high-service verticals; scale volume in lower-compliance, cost-sensitive channels through efficient manufacturing and distribution partnerships.
- Invest in Data-Enabled Reliability: Deploy monitoring and predictive maintenance capabilities that reduce unplanned downtime and increase the value proposition for service contracts.
Data Integrity, Coverage and How to Use the Model
The study uses a bottom-up revenue-construction methodology aligned with industry shipment data, supplier financials, certification records, and validated end-user maintenance cycles. The base year is 2025, with historical series covering 2020–2025 and forecasts through 2032. We deliberately modeled multiple uptake curves for emerging media technologies and regulatory-driven adoption to produce conservative and upside scenarios that feed into the strategic playbooks.
Note: this preview refrains from publishing detailed regional, type, or application splits contained in the full report. That granularity is intentionally reserved for subscribers and buyers because the segmentation tables and channel-level elasticity matrices are the operative intelligence used for commercial execution.
Conclusion — Where to Focus in 2026
Media-based water filtration is a structurally growing market with a measured CAGR, regulatory tailwinds in safety-sensitive applications, and operational levers that convert market activity into recurring revenue. For firms positioning for 2026, the imperative is clear: combine certification-led access, lifecycle service models, and input-cost mitigation to capture disproportionate returns in a market that rewards steady, differentiated execution.
PW Consulting’s full Media Based Water Filters Market report contains the actionable segmentation, supplier scorecards, and implementation templates required to translate this strategic direction into a 90–180 day operational plan. For access to the complete dataset, scenario models, and executive briefing materials, please visit the report landing page.
For detailed analysis of this topic, please visit the official page: Media Based Water Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


