



PW Consulting: 3D AOI Market at USD 1,506M in 2025, 9.8% CAGR to 2032

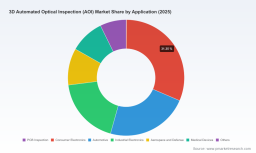
3D Automated Optical Inspection (AOI) Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As manufacturers and equipment investors reset capital plans for 2026, 3D Automated Optical Inspection (AOI) has moved from a productivity enabler to a strategic linchpin for electronics and semiconductor assembly. PW Consulting’s latest market study — base year 2025, forecasting through 2032 — quantifies a market that expanded from below one billion USD in 2020 to approximately USD 1.506 billion in 2025, and that is on a sustained growth trajectory (compound annual growth rate of 9.8%). Under our central forecast, the global 3D AOI market more than doubles by the end of the forecast window.
3D Automated Optical Inspection (AOI) Market
Why this preview matters for 2026 strategy
-
Capital allocation: Buyers and OEMs face a narrow window to align automation CAPEX with product life cycles. The market’s near‑term momentum implies that decisions taken in 2026 will lock-in inspection architectures for the next five to seven years.
3D Automated Optical Inspection (AOI) Market -
Technology selection: The choice between inline and offline AOI, sensor modalities, and AI-enabled analytics is no longer purely a cost-performance tradeoff. It is also a supply‑chain and compliance decision — affecting time‑to‑volume and geopolitical resilience.
3D Automated Optical Inspection (AOI) Market -
M&A and partnerships: With a moderate level of market concentration among incumbents, there are strategic opportunities for vertical integration, niche consolidation, and software-enabled differentiation that can materially change competitive positioning.
-
Regulatory and procurement risk: New export-controls and component‑level licensing introduced in recent years materially affect sensor sourcing and program timelines — making procurement strategy a first‑order business risk in 2026.
What PW Consulting’s full study delivers (practical, action‑oriented)
-
Robust market sizing and trajectory models — base year 2025 with historical context (2020–2025) and scenario forecasts through 2032. These models are built for sensitivity analysis and direct integration into capex planning tools.
-
Driver and restraint mapping that links end‑market dynamics (consumer electronics, automotive electrification, advanced packaging, medical devices, aerospace) to AOI demand by inspection mode and deployment pattern.
-
Supply‑chain heatmaps and lead‑time matrices for critical subsystems (high‑speed imaging, laser modules, optics, and processing electronics), including trade‑control and sourcing risk overlays.
-
Competitive intelligence dossiers on leading OEMs, with comparative capability matrices covering sensor technology, throughput, AI/ML analytics, inline integration, and post‑sales support models.
-
Commercial benchmarking and procurement playbooks — RFP templates, TCO (total cost of ownership) models, and criteria checklists for pilot to volume ramp decisions.
-
Strategic playbook for OEMs and integrators, including three prioritized growth strategies: product leadership (sensor/AI differentiation), solution leadership (line‑level integration and analytics), and footprint leadership (regional manufacturing & service hubs).
-
Regulatory impact scenarios and mitigation options — mapping export‑control permutations and supplier diversion strategies that materially change program timelines and costs.
Competitive landscape — who matters and why
The 3D AOI vendor universe blends established capital‑equipment leaders, specialist imaging firms, and assembly‑equipment OEMs. Market concentration is meaningful but not prohibitive: the top three players account for a significant share of revenue, and the top five together represent about half of the market — a structure that supports both scale economies and targeted disruption.
-
KLA Corporation — brings advanced substrate and IC‑level 3D inspection pedigree to AOI through high‑resolution metrology and AI‑enhanced defect detection. Their portfolio has been extended to address complex substrate formats and high‑density interconnect inspection needs.
-
Omron Corporation — differentiates with multi‑angle imaging and AI workflows tailored for high‑mix PCB and automotive electronics lines. Recent product enhancements emphasize pre/post‑reflow solder and component inspection for demanding manufacturing environments.
-
CyberOptics Corporation and Nordson — both leveraging advanced sensor technologies (including MRS®-style suppression methods) to deliver high‑resolution SMT inspection and, increasingly, multifunction platforms that combine AOI with SPI and inline metrology.
-
Test Research, Inc., Viscom AG, Koh Young, Saki, Mirtec, Mycronic, GÖPEL electronic, and JUKI — each occupies a distinct niche: ultra‑high resolution for advanced packaging, precision coplanarity and height metrology, phase‑shift 3D sensing, high‑speed dense‑PCB inspection, integration expertise for high‑mix assembly, AR‑augmented inspection workflows, and SMT line integration respectively. Buyers evaluate these vendors not only on headline throughput but on how their systems integrate into existing MES/line control and analytics stacks.
Recent industry developments and their strategic implications
-
Product refresh cycles among major vendors accelerated in 2025–2026, with new catalogs and trade‑show debuts emphasizing higher resolution, AI‑driven analytics, and multifunction consolidation. For buyers, this raises the question: buy now and retrofit later, or plan for next‑generation platforms that deliver step‑change capability?
-
Export controls and component licensing have tightened for high‑speed imaging sensors and laser modules. The US Bureau of Industry and Security and other jurisdictions have expanded review scopes, and some supplier nations have introduced countermeasures — extending procurement cycles. Strategic implication: procurement teams must vet alternate sources and build longer lead‑time buffers into production ramp plans.
-
Reshoring and CHIPS‑era incentives have redirected demand toward new inline inspection investments in target manufacturing regions. This is creating regional pockets of accelerated demand — an opportunity for service‑oriented players and for OEMs that localize assembly and service footprints.
Practical strategic recommendations for 2026
-
Adopt a two‑track procurement strategy: secure capacity now for existing line requirements while reserving allocation for next‑generation systems. This reduces risk from both supplier lead‑time volatility and imminent product upgrades.
-
Prioritize sensor‑level due diligence. Given regulatory and component supply risk, assess suppliers’ vertical exposure (e.g., reliance on specific imaging sensors or lasers), their compliance posture, and their contingency plans for sourcing constrained components.
-
Invest in AI and analytics integration early. The long‑term value of AOI is increasingly realized through data — closed‑loop defect analytics, adaptive process control, and predictive maintenance. Build integration requirements into RFPs and require demonstrable API and data‑model compatibility during pilots.
-
Pursue partnerships for service and localization. Suppliers that can establish regional service hubs, spare‑parts pools, and rapid calibration turnarounds will win share in markets driven by near‑shoring and high‑uptime SLAs.
-
Use scenario planning for trade‑control permutations. Our report includes playbooks that quantify P&L and schedule impact under alternative regulatory outcomes — necessary inputs for board‑level risk conversations and contingency budgeting.
-
Consider strategic M&A or alliance moves to obtain sensor technologies, AI stacks, or in‑country service capabilities — particularly in markets where local presence materially lowers procurement friction and time‑to‑volume.
How PW Consulting’s report supports fast, defensible decisions in 2026
This study is built to be executable. Beyond headline forecasts (the market reached approximately USD 1.506 billion in 2025 and is growing at an estimated 9.8% CAGR), the deliverables are designed as board‑level and operational toolkits: downloadable forecast models that plug into CAPEX pipelines, vendor scorecards you can use during RFP evaluations, and supply‑chain risk heatmaps you can present to procurement committees.
We intentionally keep this preview high‑level — showcasing the framework, the strategic levers, and the vendor landscape — while preserving the detailed segmentation, regional breakdowns, and interactive forecast tables for subscribers. Those granular datasets power drill‑down analysis (by inspection mode, application end‑market, and region) that are essential when dollars and factory lines are on the table.
Next steps
-
For equipment buyers and manufacturing leaders: request the interactive model to map AOI investments against your product roadmaps and ramp schedules.
-
For OEMs and component suppliers: use our vendor benchmarking to identify capability gaps and partnership targets for 2026 execution.
-
For investors and corporate development teams: schedule a briefing with PW Consulting to review M&A opportunity maps and regulatory‑scenario stress tests.
PW Consulting’s full 3D AOI market study provides the empirical backbone and the decision templates that executives need to navigate a market that is growing rapidly and being reshaped by technology, geopolitics, and policy. For access to the segmented forecasts, vendor scorecards, and the downloadable scenario models referenced in this preview, please visit our report page or contact our research team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: 3D Automated Optical Inspection (AOI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


