



PW Consulting: Organic Bread Flour Market to Reach USD 253.1M by 2032 at 6.96% CAGR

Organic Bread Flour Market 2026: Strategic Preview for Decision-Makers
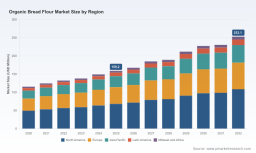
As PW Consulting’s lead industry analyst, I present a strategic preview of the Organic Bread Flour market designed specifically to inform high-stakes decisions in 2026. Our full study, anchored on a 2025 base year and projecting through 2032, shows the market expanding at a compound annual growth rate of 6.96%. To ground the narrative: the market progressed from approximately USD 115.4 Million in 2020 to USD 159.2 Million in 2025, and is forecast to reach roughly USD 253.1 Million by 2032, with an interim projected size of about USD 167.5 Million in 2026. These macro dynamics frame a market that is both maturing and offering distinct windows for differentiation, scale, and consolidation.
Organic Bread Flour Market
Why this matters for 2026 strategy
2026 is the inflection year when supply-chain constraints, regulatory shifts, and consumer premiumization coalesce into actionable risks and opportunities. For executives and investors, the central strategic question is not whether the organic segment will grow—our topline forecast confirms it will—but how you capture value within a market that commands pricing premiums, requires supply-chain transparency, and remains fragmented in supplier power.
Organic Bread Flour Market
- Premium dynamics: Organic flours carry a meaningful premium versus conventional equivalents due to certification and production costs. This premium creates margin upside but also raises expectations for quality, traceability, and branding investments.
- Supply elasticity and raw-material risk: Certified-organic wheat availability is improving—North American certified acreage expanded materially in recent years—but remains supply-constrained versus conventional wheat. Policy moves and trade frictions can quickly reroute flows and compress margins.
- Regulatory and trade volatility: Emerging trade measures and evolving organic rules will alter cross-border sourcing economics. Executives must model these variables into procurement, capacity, and channel strategies starting in 2026.
Market dynamics and structural drivers
Demand drivers are multi-dimensional. Health and sustainability narratives continue to underpin consumer willingness to pay, while artisanal and in-home baking trends sustain steady volume from specialty and retail channels. At the same time, commercial bakery demand for consistent, high-performance organic bread flour is rising as industrial bakers retrofit formulations to meet retailer and foodservice callouts.
Organic Bread Flour Market
On the supply side, there has been meaningful growth in certified-organic farm supply in key producing markets over the past half-decade, improving raw-material availability but not yet eliminating volatility. Packaging and labeling also play a direct role: organic products typically command a 30–40% price premium over conventional equivalents, which places additional emphasis on premium packaging and certification claims that can justify that spread.
Overlaying these fundamentals are two regulatory developments that will materially affect 2026 planning. First, in March 2025 Canada implemented retaliatory tariffs covering selected agricultural goods, including certain wheat and flour products—an active trade-policy headwind that has already altered short-term regional sourcing economics. Second, the European Commission moved in late 2025 to simplify labelling and organic certification for third-country imports; this has implications for exporters and market-entry strategies and should be modeled into compliance and go-to-market timelines.
Competitive landscape: profiles and strategic implications
The Organic Bread Flour market shows low to moderate concentration: the three-largest firms account for a minority share of the market and the top five still capture less than a third overall—an indicator of fragmentation and opportunity for scale plays or differentiated positioning.
- Ardent Mills (Denver, CO) — Ardent Mills has signaled its strategic intent through capacity expansion investments in 2025 to meet growing organic demand. Their strength is scale-based supply programs, grower networks, and the ability to offer USDA-certified organic lines to both commercial bakers and ingredient customers. For incumbents, Ardent’s moves raise the bar on logistics and private-label supply capability.
- King Arthur Baking Company (Vermont, USA) — Positioned as the artisanal benchmark, King Arthur focuses on product performance and brand trust. Their organic bread flours are tailored to artisan bakers, a segment where differentiation is quality-driven rather than price-driven. Competitive defensive strategies must consider King Arthur’s strong retail and direct-to-consumer channels.
- Bob’s Red Mill Natural Foods (Oregon, USA) — With a product launch in early 2025 emphasizing stone-ground organic flours optimized for home bakers, Bob’s Red Mill is reinforcing its specialty-baking credentials. Their approach highlights the importance of formulation and consumer-facing innovation in protecting premium margins.
- Fairhaven Mill (Washington State, USA) — As a regional, community-focused miller with a long heritage in certified organic production, Fairhaven underscores the strategic value of local sourcing, provenance storytelling, and niche quality segments.
- Great River Milling (Minnesota, USA) — Strong on traceability and supporting both artisan and commercial customers, Great River is illustrative of mid-sized players that bridge the gap between local authenticity and commercial reliability.
- General Mills (Minneapolis, MN) — As a diversified food company, General Mills leverages integrated organic wheat sourcing programs and broad retail reach. Their presence illustrates how corporate buyers can move the market through integrated procurement and retailer partnerships.
New entrants and adjacent-category players are also active—most notably a U.S. retail entrant into the organic flour category in late 2024—signaling low barriers to brand entry so long as credible supply and certification are secured.
What PW Consulting’s full report provides (practical, operational content)
To support immediate 2026 action plans, our full study contains a suite of decision-grade, executable deliverables. Highlights include:
- Top-down market sizing and validated forecasts (2020–2032) with sensitivity lanes tied to tariff scenarios and organic acreage expansion assumptions.
- Demand-shift matrices by channel and buyer persona, with elasticities calibrated for premium pricing and promotional tactics.
- Supply-side maps: supplier & mill capability matrices, grower network overlays, and a traceability maturity model for organic flour sourcing.
- Pricing and margin models that factor certification costs, packaging premiums, and shipping differentials under multiple trade-policy scenarios.
- Regulatory-impact playbook that translates specific policy moves—such as tariff events and EU organic-labeling amendments—into operational checklists for procurement, QC, and export compliance.
- Packaging and go-to-market toolkits that convert the 30–40% premium opportunity into SKU, pack-size, and channel recommendations with ROI timelines.
- M&A and partnership screen for 2026–2028 including target qualification criteria and accretion/dilution modeling under varying integration costs.
- Risk matrices and scenario-running tools: price shocks, crop yield variance, and certification disruptions with mitigation playbooks.
Note: core segmentation tables and granular supplier or region-level shares are intentionally omitted from this preview to preserve the proprietary value of our datasets. Subscribers to the full report gain access to those tables and the underlying models.
Priority strategic moves for 2026 decision-makers
Our analysis points to a set of prioritized actions that can be implemented rapidly in 2026 to capture upside while containing downside risk:
- Secure multi-year contracts with certified-organic growers or enter into revenue-sharing grower programs to lock-in volumes and improve margin predictability.
- Invest in batch-level traceability and documentation; buyers will pay premiums for provenance, and traceability reduces compliance risk under emerging EU and North American rules.
- Re-examine the SKU portfolio to shift toward premium, higher-margin bread-flour SKUs while optimizing pack sizes for both commercial and retail channels.
- Adopt a hedged sourcing strategy that blends local/regional supply with vetted third-country sources to insulate from tariff-induced dislocations.
- Accelerate packaging and labeling upgrades that communicate organic credentials and sustainability—these convert the 30–40% price premium into repeat purchase behavior.
- Consider selective capacity expansion or tolling partnerships (including with larger millers expanding organic capacity) rather than full-scale greenfield builds to limit CapEx while scaling quickly.
- Pursue bolt-on M&A targets that provide traceability, regional sourcing, or formulation IP rather than large-market-share acquisitions—this preserves agility in a fragmented landscape.
Closing: how PW Consulting helps you translate the preview into a 2026 roadmap
The Organic Bread Flour market is moving from niche to mainstream premium: growth is steady, margins are attractive, and structural changes—policy shifts, packaging premiums, and supply evolution—create a narrow window in 2026 to secure advantaged positions. Our full report supplies the transactional and operational playbooks executives will need to mobilize investment committees, supply-chain teams, and commercial organizations.
For competitive intelligence, actionable scenario models, and the proprietary segmentation matrices referenced in this preview, visit the PW Consulting report page to access the complete study and downloadable tools. The preview above outlines the strategic contours; the full report equips you to act.
For detailed analysis of this topic, please visit the official page: Organic Bread Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


