



PW Consulting: SSPA Satcom Amplifiers to reach USD 624.6M by 2032 (5.2% CAGR)

SSPA Satcom Amplifiers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As satellite networks proliferate — from GEO and MEO backbone systems to dense LEO constellations and emerging mmWave uplinks — the market for solid-state power amplifiers (SSPAs) is transitioning from component replacement to systems-level strategic investment. Our SSPA Satcom Amplifiers Market study, anchored on a 2025 base year and covering historical performance from 2020–2025 with forecasts through 2032, shows a sustained market expansion driven by GaN adoption, gateway modernisation, and defence-led procurement. The market is set to grow at a compound annual growth rate (CAGR) of 5.2% over the forecast horizon, reflecting steady demand for higher-efficiency uplink solutions and increasing deployment of small-footprint, high-frequency terminals.
SSPA Satcom Amplifiers Market
Why this study matters for 2026 strategic choices
- Timing matters: 2026 is the inflection point at which short-cycle procurement (transportables, gateways upgrades) and long-cycle investments (satellite payload co-design, ground infrastructure refresh) converge — creating windows for market entry, consolidation, or premium positioning.
- Technology arbitrage: The transition to GaN-on-SiC and GaN power modules has reduced operating cost and size metrics for ground stations. Buyers and system integrators making decisions in 2026 will lock in multi-year TCO profiles that favour specific amplifier architectures and supply chains.
- Regulatory and defence tailwinds: Military standards and reimbursement mechanisms in major markets (for example, recent US Space Force and Wideband program requirements) are accelerating procurement cycles for MIL-grade SSPAs — a dynamic that procurement teams must internalise when drafting RFQs in 2026.
Market trajectory in concise numbers
Our model traces the overall market from the early 2020s recovery into a stable growth pattern. By the 2025 base year the market had recovered and consolidated around high-efficiency solid-state designs; the forecast to 2032 anticipates continued expansion with compound growth at 5.2% annually. The trajectory is driven by a mix of capacity upgrades at gateways, replacement of legacy TWTAs in many ground segments, and new deployments for higher-frequency uplinks (including mmWave bands). These macro totals underpin scenario planning for CAPEX timelines, inventory strategies, and R&D roadmaps across suppliers and users.
SSPA Satcom Amplifiers Market
What the market means for strategic stakeholders
- OEMs and component suppliers: Prioritise GaN linearity and thermal management improvements. Modular, block-up-converter (BUC)-integrated offerings and power-combining approaches for V/ E/ Ka bands are high-leverage product paths.
- System integrators and service providers: Balance upfront premium on GaN SSPAs against lifecycle operational savings — energy reductions and smaller mechanical footprints materially affect gateway OPEX and siting decisions.
- Defence procurement offices: Embed MIL-STD compliance and long-term sustainment clauses into contracts now; reimbursement programs and LEO gateway modernisation funds can be structured to accelerate fielding while protecting industrial base capacity.
- Investors and M&A teams: Seek targets with differentiated module IP, demonstrated production scalability, and access to defence certifications; market concentration indicates several leaders capture a meaningful share but room persists for niche specialists.
Competitive landscape — where value is being created
The SSPA market exhibits a mid-level concentration (top-three and top-five combined shares demonstrate incumbent strength but not insurmountable barriers). Competitive advantage is clustering around a few capability axes: GaN expertise and module linearity, multi-band BUC/SSPA integration, ruggedisation for military use, mmWave power-combining, and system-level integrations for VSAT and gateway platforms.
SSPA Satcom Amplifiers Market
- Communications & Power Industries (CPI): Known for GaN-based SSPAs and high-power block-up-converters across C through Ka bands, CPI is positioned for fixed, transportable and airborne satcom use cases where power density and system integration matter.
- Comtech Telecommunications: The Puma series underlines a strategy around compact, high-efficiency GaN SSPAs with accessory features (redundancy, web control) that appeal to managed service providers and VSAT operators.
- L3Harris Narda-MITEQ: Leverages reliability and breadth across standard SATCOM bands, targeting commercial, military and scientific ground stations and payload support markets.
- Filtronic: Focused on mmWave and high-frequency uplinks with GaN Cerus products; recent UK Space Agency funding and a 100W V-band product demonstrate a bet on high-frequency ground segment growth.
- MACOM, Mission Microwave, Advantech, Teledyne Paradise, Kratos, Gilat and others: These firms differentiate across module IP, form-factor innovations (BUC-integrated lines), and tailored defense-grade offerings. MACOM’s 2026 Ka- and Q-band announcements underscore supplier emphasis on payload and direct-to-device experimentation.
Recent developments to put on your radar
- Filtronic secured public funding to advance a high-power Ka-band GaN SSPA project and released next-generation V-band SSPAs in 2025 — signalling commercial confidence in mmWave uplink demand and government support for commercial amplifier innovation.
- MACOM’s product launches and trade show presence in 2026 highlighted demonstrations for direct-to-device payloads and linearised Q-band modules — important if your roadmap assumes tighter payload-hooks with amplifier vendors.
- L3Harris Narda-MITEQ’s exhibition emphasis on LEO-optimised amplifier assemblies illustrates supplier response to constellation-era gateway requirements.
- Policy and procurement shifts: recent defence contracting language and reimbursement pathways are actively shaping procurement cycles and the opportunity window for MIL-qualified SSPAs.
Operational levers and go-to-market playbook (practical contents of the report)
The full study provides executable modules for different stakeholder types. Highlights include:
- Proprietary forecast model (2026–2032) with scenario toggles for technology adoption rates, gateway refresh timelines, and defence procurement accelerants.
- Supplier scorecards and risk matrices assessing manufacturing capacity, IP ownership, certification status, and product roadmaps — ideal for sourcing teams evaluating preferred vendors.
- Build vs. buy decision frameworks combining TCO, sustainment cost curves, and supply-chain lead-time sensitivity to guide in-house amplifier development versus contract procurement.
- Go-to-market playbooks covering channel strategies for OEMs, value propositions for systems integrators, and bundling options for VSAT service providers.
- Operational worksheets: CAPEX/OPEX calculators, energy and footprint savings estimators (reflecting observed GaN efficiency improvements), and procurement timing calendars aligned with major defence and civil program release windows.
Risks, regulatory considerations and mitigation
- Standards and certification risk: Military standards such as recent MIL-STD requirements for Ka-band systems create a barrier to entry but also an annuity stream for certified suppliers. Early certification investment is a strategic hedge.
- Supply chain concentration: GaN substrate access and module assembly capacity can be pinch points; dual-sourcing strategies and design-for-repairability reduce exposure.
- Market substitution: TWTA-to-SSPA replacement is ongoing; however, pockets of TWTA persistence remain where extreme power or specific linearity profiles are required. Positioning products for the right use cases avoids commoditisation.
- Policy and funding volatility: Grant programmes (for example, national space innovation funds) materially accelerate product development but can shift with political cycles — diversify route-to-market to include commercial anchor customers.
How to use this study in 2026 planning cycles
- Procurement: Use the report’s scenario model to set budget phasing for gateway refresh and transportable terminal upgrades across 2026–2028, aligning RFQs to supplier certification timelines.
- R&D prioritisation: Allocate development resources to GaN linearity, thermal management, and modular BUC integration — the areas with the highest expected near-term ROI.
- M&A and partnerships: Target suppliers with demonstrable production scalability and complementary system integration capabilities rather than solely component IP.
- Energy and footprint optimisation: Quantify OPEX benefits from GaN adoption to accelerate business cases for early replacements of legacy amplifiers.
What we intentionally withhold here (and why)
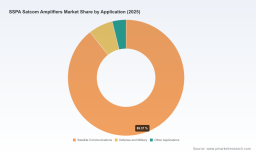
In keeping with the “trailer” approach of this preview, we present the strategic line-of-sight — market growth rate, concentration dynamics, competitive vectors and practical playbooks — while purposefully omitting core segment-level tables and the detailed region/application share matrices that sit at the heart of procurement decision analytics. Those granular splits, supplier-specific revenue breakdowns and pricing ladders are available in the full report and interactive datasets for subscribers and direct purchasers.
Final thought
For decision-makers planning capital allocation, supplier selection, or product roadmaps in 2026, SSPA strategy is now a cross-functional priority spanning engineering, procurement, and finance. The market’s steady CAGR and the technological momentum behind GaN create an environment where early, well-informed choices capture sustained advantage. Our full SSPA Satcom Amplifiers Market report provides the detailed levers, numbers, and vendor-level intelligence you need to move from strategic intent to executable plans — precisely the inputs that turn 2026 opportunities into multi-year value.
For detailed analysis of this topic, please visit the official page: SSPA Satcom Amplifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


