



PW Consulting: Acoustic Vents Market Poised for 6.32% CAGR Through 2032

Acoustic Vents Market — 2026 Strategic Preview
As cities densify and building performance expectations rise, acoustic vents have shifted from a niche product to a strategic building component. This PW Consulting preview translates the latest market modelling, supplier dynamics and regulatory imperatives into a concise playbook for executives planning decisions in 2026. Our base-year modelling (2025) and a 2026–2032 forecast horizon indicate a steady expansion driven by retrofit programmes, urban noise mitigation and energy-conscious ventilation design. The market, which grew through the first half of the decade, is projected to expand at a compound annual growth rate of approximately 6.32% over the forecast period — a profile that rewards focused product innovation, specification-led commercial models and disciplined supply-chain management.
Acoustic Vents Market
Why this research matters for 2026 decision-making
-
Policy and compliance are converging with occupant expectations. In several mature markets, acoustic vents must now satisfy background ventilation needs without compromising sound insulation targets — a dynamic driven by building regulations and independent acoustic testing standards.
Acoustic Vents Market -
Retrofit activity and urban noise abatement are creating sustained, repeatable demand. Where once acoustic venting was a specialist topic for high-noise projects, it is increasingly being specified in mainstream residential and commercial refurbishment programmes.
Acoustic Vents Market -
Material and manufacturing stability create strategic windows. The primary materials in use — UV-stabilised ABS and aluminium — have shown relative pricing stability amid volatile raw-material markets, enabling manufacturers to plan product roadmaps and margin strategies with greater confidence.
What the full report delivers — practical, executable intelligence
-
Market sizing and topline forecast (2020–2032) with scenario modelling to stress-test demand under alternative policy and energy-price paths.
-
A regulatory and standards matrix covering typical compliance pathways (including background ventilation requirements and sound reduction testing requirements), plus a checklist for product specification and certification.
-
Competitive landscape and supplier profiles with capability maps, go-to-market models and a short-list of strategic partners and acquisition candidates.
-
Product benchmarking and performance specification templates — acoustic attenuation, throughput, weathering and aesthetic options — for use in procurement and tender evaluation.
-
Material-cost and sourcing analysis that identifies leverage points in procurement and manufacturing, including recommendations on hedging and supplier diversification.
-
Commercial playbooks for OEMs, distributors and installers, including channel segmentation, specification-targeting and pricing tactics tailored to retrofit and new-build routes.
-
Financial modelling tools and KPIs designed to support investment cases for R&D, capacity expansion, and M&A decisions.
Data-driven signals you can act on in 2026
-
Growth runway: The market has expanded consistently since 2020, with the 2025 base supporting near-term acceleration. Our forecast shows an upward trajectory through 2032, underpinned by policy-driven retrofits and product upgrades — a strategic environment in which early commercial investment can capture specification-led wins.
-
Specification over price in many tenders: In noise-sensitive projects, procurement increasingly prioritises demonstrated acoustic performance and independent testing over lowest-cost bids. Firms that invest in third-party verification and transparent labelling gain a clear competitive edge.
-
Design integration is a differentiator: Recent product updates by established suppliers highlight the value of aesthetic options — for example, colour-matching and slimline profiles — that allow acoustic vents to be specified without aesthetic compromise. Product families that combine acoustic attenuation with façade integration are winning broader project adoption.
-
Materials and testing standards matter: Independent testing to accepted ISO and EN standards is a gating factor for many public and institutional contracts. Ensuring compliance and publishing verified performance data reduces sales friction in specification processes.
Competitive landscape — what to watch among tier-one and specialist suppliers
The acoustic vents field remains characterised by a mixture of highly specialised manufacturers and a broader cohort of component suppliers. The market is not highly concentrated; leadership is earned through technical credibility, testing pedigree and close relationships with specifiers.
-
Titon (United Kingdom): A well-established manufacturer emphasising high sound attenuation and compliance. Recent moves to expand colour-matching across plastic and aluminium ranges signal a strategic push into projects where design integration and acoustic performance are jointly required. For competitors and partners, Titon represents a benchmark for combining certification, product breadth and spec-channel access.
-
R.W. Simon Ltd (United Kingdom): A specialist in slimline, aesthetic acoustic trickle vents designed to meet building-regulation needs. Their positioning is instructive for companies targeting heritage, retrofit and architect-specified projects where visual impact is a constraint.
-
Caice Acoustic Air Movement Ltd (United Kingdom): Focused on attenuators and louvres with a strong emphasis on independent performance testing. Their product-driven credibility makes them an attractive partner for ventilation system integrators who need verified acoustic components.
-
DUCO Ventilation & Sun Control (Belgium): Differentiates through combined acoustic and energy-efficiency claims; their recent launch of a quiet combined-ventilation system highlights the premium commanded by dual-benefit solutions in Europe. Such multi-functional systems are a leading-edge development to monitor for product roadmaps.
-
TEK Ltd, DGS Group, Greenwood Airvac, Brookvent: Each brings particular strengths — from wall-vent systems to acoustic airbricks and high-attenuation residential vents. Collectively, these specialists illustrate the breadth of routes to market: direct specification, distributor partnerships and installer-focused channels.
Strategic imperatives for executives in 2026
-
Prioritise certified acoustic performance: Invest in independent testing to internationally recognised standards. Include performance data in BIM objects and specification packs to reduce friction in design-team assessments.
-
Design for specification: Offer aesthetic options (colour-matching, slim profiles) and modular form-factors that meet both façade architects and retrofit contractors halfway. Small product features can materially increase spec-in rates.
-
Differentiate around combined benefits: Pair acoustic performance with energy efficiency or integrated ventilation control. Systems that demonstrably deliver multiple compliance outcomes have outsized value in tenders and are less exposed to commodity pricing pressure.
-
Hedge materials and stabilise costs: Lock flexible supply arrangements for UV-stabilised ABS and aluminium, and consider dual-sourcing to mitigate concentration risks. Use the relative material-price stability to plan three-year product roadmaps and margin targets.
-
Pursue spec-driven commercial models: Invest in technical sales capabilities and partnerships with window and façade OEMs. Specification wins drive volume and reduce customer acquisition cost in this market.
-
Evaluate targeted M&A and partnerships: Look for tuck-in specialists with strong testing pedigrees or distribution footprints in retrofit channels. Acquiring a recognised acoustic brand can accelerate spec penetration faster than organic development.
-
Operationalise rapid iterations: Short development cycles for colour ranges, installation kits and retrofit fixings can be the difference between winning and losing specification rounds in 2026.
Scenarios and near-term triggers to monitor
-
Regulatory shifts: Any tightening of ventilation or acoustic requirements in national building codes will quickly re-weight demand toward independently tested products. Maintain a regulatory watch and scenario overlay for procurement and R&D timelines.
-
Material price shocks: Aluminum or polymer supply disruptions would stress margins for producers without flexible sourcing. Early supplier engagement and strategic inventory policies are prudent.
-
Product innovations: New combined ventilation solutions or major product launches by established suppliers can alter specification dynamics. Recent product updates from leading vendors demonstrate how quickly specification preferences can evolve.
-
Consolidation moves: Watch for acquisitive behaviour among larger façade or HVAC players seeking to internalise acoustic vent capabilities — this could compress supplier choice in some channels and create partnership opportunities in others.
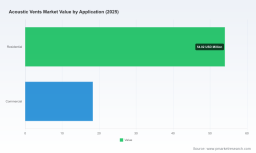
For executives planning capital allocation, product roadmaps or channel investments in 2026, the strategic imperative is clear: convert acoustic performance into a specification advantage while protecting margin through disciplined sourcing and value-added product features. The full PW Consulting Acoustic Vents Market study supplies the detailed regional and application splits, supplier benchmarking scores, pricing curves and financial models you will need to operationalise these recommendations. To access the granular data and interactive scenario tools that underpin this preview, please consult the full report.
For detailed analysis of this topic, please visit the official page: Acoustic Vents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


