



PW Consulting: EDI Software Market to Grow at 9.8% CAGR Through 2032

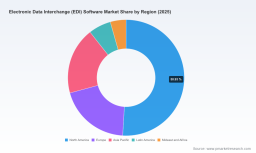
Electronic Data Interchange (EDI) Software Market: Strategic Preview for 2026 Decision-Makers
As organizations finalize their 2026 technology budgets and supply‑chain modernization roadmaps, understanding the economics and competitive dynamics of the EDI software market is now a strategic imperative. PW Consulting’s latest market study — anchored to base year 2025 — synthesizes a decade of vendor behavior, deployment shifts, regulatory friction points, and adoption economics into a practical intelligence package intended to reduce vendor risk, accelerate integration outcomes, and improve negotiated total cost of ownership (TCO) for enterprise buyers.
Electronic Data Interchange (EDI) Software Market
Market Trajectory: What the numbers tell procurement and IT leaders
The EDI software market has moved from niche, on-premise integrations to a mainstream component of digital supply‑chain stacks. Our historical series shows clear expansion from the early 2020s into 2025, with the market accelerating as cloud and hybrid models became operationally mature. By the 2025 base year the market had reached approximately USD 1.62 billion (revenue unit: Million), and our forecast through 2032 projects continued expansion to roughly USD 3.11 billion, driven by cross‑industry automation, regulatory digitization, and greater interoperability demands. The forecast period (2026–2032) is modeled at a 9.8% compound annual growth rate (CAGR), which positions EDI software as one of the more resilient middleware categories in the enterprise integration layer.
Electronic Data Interchange (EDI) Software Market
Two practical implications flow from this trajectory. First, the market growth rate signals that vendor viability risk is lower than in earlier cycles, but it also invites consolidation activity by both strategic incumbents and private equity. Second, sustained growth will translate into rising expectations for automation, analytics, and API/EDI convergence — putting a premium on integration platforms that can both modernize legacy trading partner networks and instrument them for real‑time decisioning.
Electronic Data Interchange (EDI) Software Market
What this study delivers — a practical, actionable toolkit
This report is intentionally operational. Executive summaries and headline charts are accompanied by tactical assets that procurement, IT, and line‑of‑business leaders can deploy during vendor selection and contract negotiations:
- Vendor assessment framework: qualitative scoring across architecture, scalability, multi‑protocol support (EDI, APIs), partner network depth, and professional services.
- TCO model templates: scenario‑based calculators that quantify upfront migration costs, integration labor, per‑transaction economics, and multi‑year vendor price escalations.
- Integration playbooks: step‑by‑step paths for cloud migrations, hybrid coexistence strategies, and ERP‑centric deployments (including common pitfalls and mitigation controls).
- Regulatory compliance checklists: coverage of emerging e‑invoicing and public‑sector certification requirements, with practical evidence requirements for auditors and procurement panels.
- Implementation KPIs: recommended SLAs, monitoring metrics, and maturity checkpoints to measure EDI health across trading‑partner networks.
- Negotiation levers: contractual tactics to limit per‑transaction escalators, cap professional services billable rates, and secure upgrade pathways.
We deliberately stop short in this preview of publishing micro‑segmentation tables and line‑item pricing benchmarks — these are retained for subscribers who require the full dataset, vendor scorecards, and the interactive model that powers scenario testing.
Competitive landscape — who to watch and why
The market shows moderate concentration. Our analysis reports a top‑three concentration in the mid‑30s percentage range and a top‑five approaching the high‑40s, which signals a competitive field where leading players exert influence but meaningful space remains for specialized and regional challengers. Strategic buyers must evaluate both the market leaders for scale and resilience, and specialist providers for vertical fit and faster time‑to‑value.
- Cleo Communications (United States) — Cleo’s Integration Cloud positions EDI within an AI‑enabled orchestration layer that converges EDI and API flows. Their recent product extensions emphasize self‑service management and automation for complex trading networks, which reduces integration labor and accelerates time to onboard new partners.
- SPS Commerce (United States) — SPS focuses on cloud‑native connectivity for retail ecosystems, with strengths in supplier compliance and retail partner networks. Their go‑to‑market is optimized around marketplaces and large retail trading hubs, making them a frequent choice where retail compliance is the dominant procurement criterion.
- TrueCommerce (United States) — TrueCommerce’s cloud EDI suite is distinguished by rapid ERP and eCommerce marketplace integrations. Notably, in 2025 they launched an integration with SAP S/4HANA Cloud Public Edition, signaling intensified support for ERP‑first migration strategies and opening pathway architectures for SAP customers.
- OpenText (Canada) — OpenText combines classic trading‑grid capabilities with cloud Business Network offerings. Their 2025 introduction of a cloud EDI solution for healthcare demonstrates the vendor’s move to package industry‑specific compliance and security controls for regulated verticals.
- IBM (United States) — IBM’s Sterling B2B Integrator remains a go‑to for enterprise deployments that require advanced routing, B2B transaction governance, and deep ERP adjacency. Sterlings’ positioning caters to complex, high‑transaction environments that prioritize throughput and enterprise governance.
Recent vendor developments underline the strategic moves you should expect: product launches that simplify self‑service EDI, ERP integrations that shorten migration cycles, and targeted vertical solutions for sectors like healthcare that are navigating specific regulatory requirements. These shifts have material procurement implications — vendors now bid not only on core capabilities, but on the speed of adoption and the degree to which they reduce downstream operational costs.
Market dynamics and “noise” — factors that will shape 2026 decisions
Three themes require explicit attention when building RFPs and migration roadmaps for 2026:
- Integration labor and hidden costs: EDI programs can be deceptively expensive. Beyond license fees, buyers face integration labor, per‑transaction fees, and the potential for routine annual price increases in the 5–10% range from some enterprise vendors. Our TCO templates make these line items explicit and provide sensitivity analyses that should be run for every vendor under consideration.
- Regulatory acceleration: Evolving e‑invoicing mandates and public procurement certification regimes — especially in parts of Europe — are raising the bar for compliance. The practical outcome: vendors that can deliver certification artifacts and audit trails with minimal custom development will materially reduce the buyer’s time‑to‑compliance and risk exposure.
- Hybrid EDI + API modernization: The market’s innovation frontier is at the intersection of EDI and APIs. Hybrid architectures that enable legacy partner connectivity while exposing real‑time, API‑driven services for modern trading partners will define winners. Investment in orchestration platforms that normalize both EDI and API payloads is now a competitive necessity, not a nice‑to‑have.
How to use this intelligence in your 2026 planning cycle
PW Consulting’s study is structured to convert market intelligence into procurement action. For teams drafting 2026 initiatives we recommend three practical steps:
- Run parallel TCO scenarios: Use the report’s TCO model to compare at least three trajectories — “lift and shift” (cloud replacement), “phased hybrid co‑existence,” and “greenfield integration” with API‑first architectures. Each scenario surfaces different labor profiles, compliance milestones, and vendor lock‑in risks.
- Prioritize regulatory readiness: Require vendors to demonstrate evidence of compliance for applicable jurisdictional regimes and to commit to contractually defined upgrade paths as new certifications emerge.
- Demand integration accelerators: Shortlist vendors that provide ERP connectors, marketplace adapters, or pre‑built partner maps for your industry. These accelerators are the fastest way to reduce onboarding costs and to validate projected ROI within your fiscal planning window.
Closing — what this preview leaves for the full report
This preview outlines the strategic backdrop, vendor dynamics, and tactical checklists that will shape EDI procurement and integration choices in 2026. To preserve the value of our forensic analysis and interactive models, we have intentionally withheld the full segmentation tables, granular regional and industry splits, and the detailed vendor scorecards from this summary. The full report contains:
- Granular segment revenue models and interactive forecast inputs
- Complete vendor scorecards with capability heatmaps and reference client verifications
- Downloadable TCO workbooks and contract clause templates
For procurement teams, CIOs, and operational leaders preparing for 2026, the full dataset and playbooks accelerate decision cycles and materially reduce execution risk. Access to the complete report enables scenario testing across deployment archetypes (cloud, on‑premise, hybrid), industry demand curves, and vendor portfolios — the precise inputs you need to finalize budgets and enter negotiations with leverage.
Contact PW Consulting to obtain the full EDI Software Market report and the accompanying implementation toolkit. Use the decision window in Q1–Q2 2026 to convert this market momentum into measurable operational and financial outcomes for your organization.
For detailed analysis of this topic, please visit the official page: Electronic Data Interchange (EDI) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


