



PW Consulting: Hybrid Adhesive & Sealant Market to hit USD 12.67B by 2032 (6.5% CAGR)

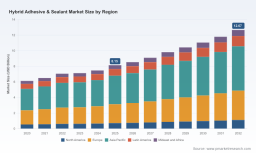
Hybrid Adhesive & Sealant Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive snapshot
As PW Consulting’s senior industry analysts, we present an executive preview of our new Hybrid Adhesive & Sealant Market study (base year 2025, historical 2020–2025, forecast 2026–2032). The market demonstrates resilient expansion driven by material innovation, regulatory realignment and cross-industry demand for lightweight, durable joining solutions — supporting a compounded annual growth rate (CAGR) of 6.5% across the forecast window. From a $X billion footprint in 2025, the market is poised to develop materially through 2032, creating strategic opportunities and operational risks that corporate decision-makers must address in 2026.
Hybrid Adhesive & Sealant Market
Why this study matters for 2026 decision cycles
2026 is the year many industrial organizations will finalize three- to five-year R&D budgets, make capital investments in production footprint and decide on mid-cycle M&A targets. Our brief translates market growth trajectories, supplier positioning and technology shifts into actionable guidance for those choices. Key strategic levers informed by the study include:
Hybrid Adhesive & Sealant Market
- R&D prioritization: where to allocate formulation work for low-VOC and bio-based hybrids that meet tightening emissions rules
- Procurement and supply chain: which feedstock exposures to hedge, and how transportation surcharges and tariffs can reshape sourcing footprints
- Commercial go-to-market: which end‑use segments and performance claims unlock premium pricing and faster adoption
- M&A and partnership screening: how to interpret concentration metrics when sizing bolt-on targets or joint-venture partners
Market trajectory — the big-picture numbers (what we disclose)
Our topline analysis synthesizes historical performance (2020–2025) and forward-looking scenarios (2026–2032). The market demonstrates steady compound growth at an expected 6.5% CAGR through 2032, reflecting a combination of replacement demand, new-specification adoption and expansion into adjacent applications such as advanced battery assembly and hybrid vehicle platforms. These topline dynamics underpin revenue and margin planning across manufacturing, distribution and OEM channels.
Hybrid Adhesive & Sealant Market
What we do not reveal here — and why
In keeping with the “trailer” principle of this preview, we deliberately withhold granular subsegment tables and region/application revenue line items that are included in the full report. Those breakdowns are necessary for precision budgeting and supplier risk models; access to them is available through the full report. The summary below nevertheless conveys the directional drivers, structural constraints and competitive signals critical to boardroom decisions.
Key dynamics shaping 2026 strategies
- Raw-material volatility: Hybrid formulations depend on petrochemical-derived feedstocks. Price swings and input shortages during 2025–2026 have compressed margins and led manufacturers to re-evaluate long-term procurement contracts, supplier diversification and strategic inventory buffers.
- Regulatory push toward low-VOC and sustainability: Tightened VOC limits in Europe and North America are accelerating reformulation toward low-VOC and bio-based hybrid chemistries. This trend creates both a compliance imperative and a competitive advantage for early movers who can demonstrate performance parity.
- Transportation and tariff pressures: Transport surcharges and recent tariff adjustments have shifted the landed cost calculus for certain polymer feedstocks. Organizations must re-run total-cost-to-serve models and consider nearshoring or alternate raw-material strategies to preserve margins.
- Labor and capability constraints: Production of moisture‑curing hybrid sealants requires specialized skills. Rising labor costs and skill shortages are increasing the value of process automation, employee retention programs and regional center-of-excellence investments.
Competitive landscape — concentration and strategic positioning
The market exhibits moderate concentration: the top three players account for a meaningful minority share, with the top five firms consolidating less than half of total market revenues. This fragmented-to-consolidated profile creates distinct strategic opportunities: large incumbents can extract scale advantages via technical sales and distribution networks, while nimble specialists can capture premium pockets through targeted innovation and service models.
Company-level implications and observed behaviors
- Henkel AG & Co. KGaA (Düsseldorf, Germany) — With established brands focusing on MS‑polymer and silane‑terminated systems for automotive lightweighting and EV battery assembly, Henkel’s recent launch of a flame‑resistant, sustainability‑oriented hybrid product signals a two‑pronged strategy: defend core industrial customers while penetrating new safety‑sensitive niches. For competitors, Henkel’s move reinforces the premiumization path in performance claims.
- Sika AG (Baar, Switzerland) — Sika’s portfolio emphasis on construction and marine applications, and the 2025 introduction of a versatile silane‑terminated hybrid designed for above- and below‑waterline use, demonstrates segmentation-driven product architecture. Expect Sika to leverage application engineering and channel depth to grow share in infrastructure and specialty marine projects.
- 3M Company (St. Paul, MN) — 3M’s Scotch‑Weld hybrid lines reflect a system‑selling approach toward construction, automotive and industrial assembly. Their advantage lies in portfolio breadth and fast cross-sell into adjacent tape and adhesive systems; rivals must prioritize differentiated formulation claims to compete on technical merit rather than distribution alone.
- H.B. Fuller Company (St. Paul, MN) — Focusing on performance-driven structural bonding and battery assembly, H.B. Fuller is positioned to capture opportunities in EV and industrial OEM supply chains. Their emphasis on acoustic sealing and assembly performance highlights a go‑to‑market play that ties product specifications to end‑user performance metrics.
- Dow Inc. (Midland, MI) — Dow’s hybrid silicone-based offerings align with transport and construction segments that require long-term weathering and sealing performance. Dow’s integration into upstream chemistry development provides an R&D edge in tuning silicone-hybrid interfaces.
- Wacker Chemie AG (Munich, Germany) — Wacker’s hybrid lines illustrate a classical industrial manufacturer strategy: stable supply, formulation expertise and local production. Their technical depth is an asset where regulatory compliance and consistent quality are non-negotiable.
- Arkema Group (Bostik, Paris, France) — Bostik’s hybrid polymers target construction and automotive niches with a focus on installation efficiency and bond durability. Arkema’s playbook frequently emphasizes channel partnerships and installer education to accelerate specification adoption.
Recent developments as strategic signals
- Henkel’s March 2026 launch of a flame‑resistant, sustainable Teroson MS hybrid highlights the intersection of safety performance and environmental claims — a blueprint for premium product positioning in regulated applications.
- Sika’s October 2025 Sikaflex-591 silane‑terminated hybrid for marine use underscores product differentiation via application-specific formulation, enabling specification capture in high‑value projects.
Operational playbook for leadership teams
Executives should treat the hybrid adhesives and sealants category as both a performance materials market and a regulatory arena. Our study recommends a three-track operational response for 2026 planning:
- Risk mitigation: Reassess supplier concentration for key monomers and silane feedstocks; model transport and tariff contingencies; negotiate flexible contracts with volume and price collars.
- Capability investment: Accelerate formulation work on low‑VOC and bio‑based hybrids; invest in analytical labs to shorten product qualification cycles; upskill production teams in moisture‑curing process control.
- Commercial execution: Reframe value propositions around lifecycle cost and regulatory compliance rather than unit price; pilot specification programs with OEMs in battery assembly and lightweight structural bonding where adoption curves are steepest.
Where M&A and partnerships create asymmetric value
Given the market’s moderate concentration, strategic acquisitions remain a powerful means to acquire formulation IP, regional capacity and channel relationships at scale. Our deal-readiness assessment in the full report highlights target archetypes: formulation-centric SMEs with validated low‑VOC platforms, regional producers with strategic logistics footprint and specialty application houses with deep OEM relationships. For partnerships, co‑development agreements with OEMs and raw material suppliers allow de‑risking of feedstock exposure while accelerating time‑to‑market.
Scenario planning and sensitivity analysis (what we model)
Our full study provides deterministic and probabilistic scenarios that quantify the impacts of feedstock price shocks, regulatory tightening and accelerated EV adoption on revenue, gross margin and capital requirements. These tools enable CFOs and strategy teams to stress-test investment cases — a capability that will be particularly valuable as 2026 budgets are finalized under persistent macro uncertainty.
Closing guidance and next steps
For companies active in or adjacent to the hybrid adhesive and sealant market, 2026 will be a decisive year to shift from reactive to proactive strategy. Priorities include locking in raw-material resilience, embedding low‑VOC product roadmaps into R&D pipelines, and selecting M&A or partnership plays that accelerate access to high-value applications. PW Consulting’s full report equips leaders with the quantitative subsegment tables, supplier maps, risk heatmaps and scenario models needed to convert these imperatives into executable plans.
Accessing the full intelligence
This preview intentionally emphasizes strategic insight while withholding the granular subsegment metrics and region/application tables that many teams require for tactical execution. To obtain the complete dataset, including comprehensive segmentation, supplier shares, price curves and downloadable scenario models, consult the full Hybrid Adhesive & Sealant Market report on our website or contact PW Consulting’s market intelligence desk.
For detailed analysis of this topic, please visit the official page: Hybrid Adhesive & Sealant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


