



PW Consulting: Laboratory Automation Equipment Market to Expand at 5.26% CAGR Through 2032

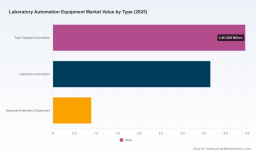
Laboratory Automation Equipment Market 2026: Strategic Preview for Executive Decision-Making
As laboratory workflows continue their rapid shift from manual benchwork to integrated, automated systems, executives face a pivotal decision year in 2026: accelerate investment to capture operational advantage, or consolidate capabilities while preserving optionality against regulatory and technology risk. PW Consulting’s latest Laboratory Automation Equipment Market research — anchored on a 2025 base year and a 2026–2032 forecast horizon — synthesizes market sizing, competitive dynamics, regulatory inflection points, and executable go-to-market scenarios to inform those choices.
Laboratory Automation Equipment Market
Snapshot: macro trajectory you need to know
The market’s recent momentum is steady and measurable. Total industry revenues grew from approximately USD 6.95 million (base 2020) to roughly USD 9.0 million in 2025, and our model projects continuation of that trajectory to an estimated USD 12.89 million by 2032. The compound annual growth rate across the 2026–2032 forecast window is 5.26%. These macro indicators signal a market that is neither hyper-explosive nor stagnant — instead offering predictable expansion driven by steady demand for throughput, traceability, and integration across clinical, pharma, and research laboratories.
Laboratory Automation Equipment Market
Why this research matters for 2026 decisions
- Capital allocation clarity: The mid-single-digit CAGR and the market’s scale profile help CFOs contrast laboratory automation investments against alternative uses of capital (digital triage, bioprocessing capacity, acquisitions).
- Procurement prioritization: Procurement and operations teams can use the directional sizing and vendor mapping in this research to time large capex deployments (phased vs. all-in) and secure favorable supplier terms during predictable upgrade cycles.
- Risk and compliance planning: With major regulatory shifts underway, the report quantifies the compliance premium and outlines mitigations that teams must budget for in 2026 to avoid rework or delayed certifications.
- M&A and partnership signaling: Buyers and targets benefit from our competitive-concentration analysis to identify consolidation opportunities and white-space partnerships that can unlock cross-selling into adjacent laboratory workflows.
Key market dynamics shaping 2026 strategy
- Standards-driven interoperability: In May 2025 the U.S. FDA formally recognized multiple CLSI laboratory automation standards covering specimen barcoding, operational requirements, and instrument communications. This recognition is already accelerating demand for “standards-compliant” integrations and favoring vendors that demonstrate open connectivity and traceability features.
- Regulatory tightening on diagnostics and quality systems: Recent regulatory activity — including a May 2024 final rule on laboratory-developed tests and the October 2025 Quality Management System Regulation (QMSR) amendments — elevates the compliance bar for vendors and purchasers alike. Device manufacturers supplying lab automation equipment will face expanded Good Manufacturing Practice expectations, affecting lead times, supplier selection, and total cost of ownership.
- AI governance and software risk: The EU AI Act (entered into force August 2024) imposes obligations on high-risk AI systems, including certain healthcare laboratory applications. Buyers must factor algorithm transparency, validation, and lifecycle management into procurement specifications; vendors must invest in compliant development and documentation frameworks.
- Consolidation and market concentration: The market shows notable concentration: the top three firms account for an estimated ~65% share, and the top five roughly ~75%. This concentration increases the importance of competitive benchmarking and creates advantages for incumbents with broad installed bases and service networks.
- Technology convergence: The intersection of liquid handling robotics, sample traceability, workflow orchestration software, and cloud-enabled analytics is redefining value propositions. Buyers increasingly evaluate holistic solutions rather than point instruments, driving demand for integrated platforms with modular upgrade paths.
Competitive landscape — who matters and what they offer
The competitive field blends global conglomerates with specialized automation specialists. The following synthesis highlights strategic positions and recent moves that will influence market outcomes in 2026; PW Consulting’s full profiles contain deeper benchmarking and deal-level implications.
Laboratory Automation Equipment Market
- Beckman Coulter (Brea, CA; beckman.com): A strong presence in total lab automation, with recent regulatory and product momentum — including an FDA-cleared clinical analyzer introduced in 2025 and partnerships extending analytical capabilities — positioning Beckman to push integrated pre-analytical solutions.
- Danaher Corporation (Washington, DC; danaher.com): Leveraging a portfolio approach, Danaher continues to deliver end-to-end automation across clinical labs through acquisitions and platform integration, making it a natural partner for large health systems seeking standardized deployments.
- Thermo Fisher Scientific (Waltham, MA; thermofisher.com): Offers comprehensive automation stacks spanning sample handling to analysis; their scale and service footprint make them competitive for multi-site rollouts and pharma high-throughput projects.
- Siemens Healthineers (Munich; siemens-healthineers.com): Focused on diagnostic workflow automation, Siemens couples clinical diagnostics expertise with total lab automation systems favored in hospital networks.
- PerkinElmer, Tecan, Agilent, Bio‑Rad, Abbott, Roche Diagnostics: Each brings distinct strengths — from liquid handling and high-throughput analytics to modular diagnostic automation — enabling tailored partnerships depending on buyer priorities (e.g., throughput, assay breadth, service models).
- Automation specialists (Hamilton, QIAGEN, Eppendorf, Sartorius, Inpeco, Biosero): These firms differentiate through robotic platforms, sample-prep automation, open connectivity, and software orchestration. Notably, Inpeco has introduced a next-generation open-connectivity total lab automation system, reflecting a strategic push toward interoperability.
Recent market signals to factor into 2026 plans
- Product and partnership activity: New product introductions and collaborations in 2024–2025 (including FDA-cleared systems and cross-disciplinary partnerships) are expanding the capability set available to labs without requiring in-house systems integration expertise.
- Standards and trade show momentum: Industry forums (e.g., SLAS Europe 2026) and the formal recognition of standards underscore the industry’s shift toward modular, interoperable automation ecosystems. Expect procurement specifications in 2026 to increasingly mandate standards compliance.
- Service and lifecycle economics: As systems become more software-dependent, service contracts, remote validation, and upgrade pathways will represent a growing portion of lifetime value. Suppliers with robust digital support and validated update mechanisms will capture a premium.
Strategic implications and recommended actions for 2026
- Rebase capital planning around modularity: Favor platforms that allow incremental automation additions and software-enabled feature activation to reduce upfront risk and preserve flexibility as assay volumes evolve.
- Prioritize standards compliance in procurement: Require documented adherence to recognized laboratory automation standards and AI governance practices. This reduces integration risk and facilitates faster regulatory approvals.
- Lock in service and validation pathways: Negotiate multi-year service-level agreements that include remote monitoring, software validation support, and clear responsibilities for regulatory-document updates tied to QMSR-like changes.
- Use vendor concentration to your advantage: Where scale justifies, standardize on incumbent platforms to simplify maintenance, training, and consumables sourcing. Conversely, consider diversifying across best-of-breed suppliers for innovation-critical workflows.
- Explore strategic partnerships and bolt-ons: Mid-size vendors and system integrators present attractive targets for bolt-on acquisitions or exclusive distribution to rapidly expand capability without in-house R&D churn.
- Align procurement with regulatory timelines: The regulatory environment is dynamic; time major deployments to accommodate compliance milestones (e.g., anticipated validation cycles tied to recognized standards) to avoid costly rework.
- Invest in workforce change management: Automation success depends on people. Allocate budget to train staff on new workflows, data management, and AI governance to capture productivity gains promised by automation.
What PW Consulting’s full report delivers
This article is a strategic preview — intentionally focused on executive insights and decision levers. The full Laboratory Automation Equipment Market report goes further, providing operational and transactional intelligence for 2026 planning, including:
- Detailed market sizing and validated forecast models (2020–2032) with scenario-based sensitivity analyses.
- Granular vendor profiling with technology roadmaps, go-to-market strategies, and channel footprints.
- Validated buyer requirements and procurement scorecards tailored for clinical, pharmaceutical, and academic purchasers.
- Regulatory impact assessments and compliance playbooks for devices, software, and AI components.
- Dealflow intelligence and M&A playbooks highlighting white-space opportunities and valuation benchmarks.
- Implementation templates (RFP language, integration checklists, SLAs) to accelerate procurement and deployment.
To preserve the tactical value of these deliverables for clients and partners, this preview omits core segment-level breakdowns and proprietary pricing matrices contained in the full report. Those granular insights — essential for bid preparation, capital approvals, and supplier selection — are available in the complete PW Consulting publication.
How to use this preview in your 2026 planning cycle
- Use the macro trajectory and regulatory timelines herein to set investment calendars, aligning capital requests with compliance milestones and vendor roadmaps.
- Share the strategic implications with procurement, lab operations, and IT to harmonize requirements around modularity, standards, and lifecycle support.
- Engage with potential vendors early to validate interoperability claims and secure phased implementation pilots tied to performance-based contract terms.
PW Consulting’s Laboratory Automation Equipment Market study was developed to support actionable decision-making in 2026 and beyond. For procurement teams, technology officers, corporate development executives, and lab leaders seeking the complete dataset, vendor scorecards, and implementation playbooks, the full report provides the operational detail required to convert strategic intent into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Laboratory Automation Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


