



PW Consulting: PTC Thermistors Market to Reach USD 437M by 2032 at 5.1% CAGR

PTC Thermistors Market: Strategic Outlook for 2026 — A PW Consulting Preview
As companies prepare strategic roadmaps for 2026, Positive Temperature Coefficient (PTC) thermistors are moving from a niche passive component to a decision-point technology across automotive, consumer, industrial, telecom and medical domains. PW Consulting’s latest market study synthesizes macro trajectories, competitive moves, supply-chain stressors and actionable playbooks that senior executives and product leaders need to translate component-level dynamics into corporate advantage.
Positive Temperature Coefficient (PTC) Thermistors Market
Why this study matters for 2026 strategic decisions
The PTC thermistors market has demonstrated steady expansion through the mid-2020s and is forecast to continue on a stable growth path over the coming cycle. From an established base in our 2025 reference year, our forecast shows continued expansion at a 5.1% compound annual growth rate across the 2026–2032 window, culminating in a materially larger addressable market by 2032. These headline trends mask several inflection points—material cost volatility, regulatory and certification gateways, and capacity investments—that will determine winners and losers in 2026.
Positive Temperature Coefficient (PTC) Thermistors Market
For C-suite teams and product leaders, the strategic value of this research is threefold:
Positive Temperature Coefficient (PTC) Thermistors Market
- It turns macro demand curves into operational priorities: where to allocate capital in manufacturing, which products to fast-track for automotive or EV qualification, and which suppliers to engage for dual-sourcing.
- It converts supplier and technology intelligence into procurement and pricing strategies that protect margin against tariff-driven input cost shocks.
- It provides a pragmatic roadmap for M&A, partnerships and in-house capability building aligned to expected growth pockets—without relying on raw volume bets alone.
What the preview reveals (and what we reserve for subscribers)
In this introduction we present the high-level signals you need to prioritize decisions in 2026; the full report contains the granular, proprietary datasets and scenario models that underpin these recommendations. Below are the types of insights you will gain immediately from the study, followed by the deeper outputs available in the full deliverable.
- Market trajectory and sizing: a clear timeline from a 2025 base through 2032 that quantifies market momentum and the sensitivity of that momentum to macro inputs (commodity prices, tariffs, and regional capacity).
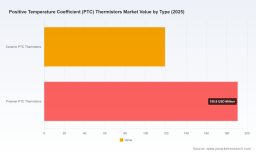
- Segment-level dynamics: technology and application narratives that explain where ceramic and polymer PTC technologies are winning today, and why—aligned with design trends across EVs, telecom, and miniaturized consumer electronics. (Note: detailed segment-by-region shares and precise dollar splits are available only in the full report.)
- Competitive posture analysis: fact-based profiles of leading vendors, their product series, engineering strengths and strategic moves—enough to benchmark suppliers and prioritize technical partnerships without disclosing our full scoring matrices in this preview.
- Supply-chain risk map: raw materials, production concentration, lead-time heatmaps and tariff impact scenarios that quantify margin exposure and inventory policy trade-offs.
- Executable playbooks: supplier scorecards, certification roadmaps (e.g., automotive-grade qualifications), cost-to-serve estimators, and scenario-based go/no-go decision frameworks for 2026 investments.
Key market forces driving 2026 outcomes
Our integrated analysis identifies five high-leverage forces to watch when making capital, product and sourcing decisions next year:
- Electrification and safety requirements: Automotive and EV architectures continue to demand robust overcurrent and thermal protection solutions. Certification attainment—both automotive and safety standards—creates durable vendor advantage.
- Miniaturization and surface-mount adoption: Consumer and telecom OEMs continue to push for smaller footprints and tighter integration, favoring suppliers with advanced SMD PTC offerings and consistent high-volume supply.
- Raw material concentration: Ceramic PTCs depend on doped barium titanate supply chains concentrated in specific processing clusters. That concentration drives lead-time asymmetry and price elasticities that must be hedged.
- Trade and tariff noise: New tariff measures introduced in 2025 have already increased input costs for ceramic powders and precious-metal electrodes. Procurement strategies that do not account for tariff volatility risk margin erosion in 2026.
- Capacity rebalancing: Incremental capacity additions—such as new manufacturing lines and plant expansions—will shift regional supply curves. Early movers secure preferred allocation; late entrants encounter longer lead times.
Competitive landscape — who to watch in 2026
The market is moderately consolidated: the top three producers command a meaningful portion of supply, and the top five extend that control further. This concentration creates both supplier leverage and visible partnership opportunities for OEMs willing to engage in collaborative roadmaps.
Our analysis of primary players highlights differentiated strategic positions:
- TDK Electronics AG — Offers a broad ceramic PTC portfolio aimed at inrush current limiting, overcurrent protection and heating applications. Recent product catalog updates and production-process changes (notably a marking method PCN) suggest ongoing SKU rationalization and manufacturing optimization.
- Murata Manufacturing — Strong in compact ceramic PTC designs and expanding capacity with new production facilities coming online. Their focus on miniaturized SMD sizes makes them an attractive partner for high-density consumer and telecom applications.
- Vishay Dale — Competitive in surface-mount and radial PTC families, with strengths in broad distributor networks and engineered part support for legacy platforms.
- Amphenol Advanced Sensors (Thermometrics) — Positioning PTCs for motor protection and automotive/industrial sensing, valuable where integrated sensor-systems are required.
- Bourns and Littelfuse — Notable for polymer PTC (PPTC) resettable fuses and discrete PTC products; key targets for OEMs requiring resettable protection and thermal management solutions.
- Regional specialists (Semitec, KOA, YAGEO, Microtherm) — Offer vertical strengths from automotive-grade certification to integrated resistor-thermistor products. Recent milestones, like YAGEO’s achievement of UL1434A with AEC-Q200 qualification, materially shift competitive dynamics in automotive-grade protection.
Recent industry developments that change the 2026 decision set
- YAGEO’s dual certification (UL1434A and AEC-Q200) for an automotive-grade PPTC thermistor accelerates qualification timelines for EV battery and on-board protection—raising the bar for suppliers without similar credentials.
- TDK’s product-process notices—marking method changes and catalog updates—signal ongoing cost optimization and possible SKU lifecycle adjustments that can affect long-tail availability for some parts.
- Murata’s forthcoming production expansion will alter regional lead-time dynamics from mid-2026 onward, particularly for SMD ceramic PTCs.
- Tariff implementations since 2025 have measurable impact on raw-material cost build-ups—this factor should be embedded into 2026 pricing and supplier-contract negotiations.
Actionable recommendations for executives planning 2026
Based on our scenario modeling and supplier intelligence, here are prioritized actions for decision-makers:
- Immediate (0–6 months): Lock in dual-source agreements for critical ceramic powders and electrode materials; initiate cost-pass clauses in new supply contracts to protect margins from tariff swings; begin certification gap analyses for products targeting automotive customers.
- Near term (6–12 months): Accelerate qualification of alternative PTC technologies (polymer vs. ceramic) for specific applications where cost or lead time pressures dominate; negotiate inventory-buffer programs with strategic suppliers to smooth 2026 demand peaks.
- Medium term (12–24 months): Evaluate opportunistic capacity investments or joint ventures in regions with favorable trade regimes; prioritize suppliers with demonstrated certification achievements and capacity expansion roadmaps.
- Strategic (24+ months): Consider targeted M&A to gain critical materials-handling capability or to internalize certification-heavy product lines that are key to your system-level differentiation.
What the full PW Consulting report delivers
The complete market study delivers the datasets and tools necessary to execute the recommendations above:
- Proprietary market-size time series (2020–2032) with scenario toggles for tariff, raw-material shocks and accelerated electrification.
- Segment-level dashboards (technology, application, region) with deterministic and probabilistic forecasts—available to subscribers for detailed commercial planning.
- Supplier heatmaps, scorecards and sample contract language templates for strategic sourcing teams.
- Certification pathway templates (including automotive standards) and product qualification timelines to reduce time-to-revenue for safety-critical designs.
- Playbooks for pricing, hedging, and inventory optimization tailored for component manufacturers and OEM buyers.
Closing: what to act on now
2026 will be a year where component-level decisions have outsized system-level consequences. With the PTC thermistors market on a steady growth trajectory and subject to concentrated supply, certification gatekeepers and trade-policy noise, executives must prioritize: (1) supplier diversification and certification alignment, (2) cost protection against raw-material and tariff volatility, and (3) selective capacity partnerships to secure long-term allocation. PW Consulting’s full report equips leadership teams with the quantified scenarios, supplier intelligence and executable templates required to make those choices confidently.
For a complete set of data tables, supplier scorecards, and the scenario model underpinning these recommendations, access the full PW Consulting PTC Thermistors Market report. Our clients use that granular intelligence to embed defensible assumptions into budgets, supplier contracts and R&D roadmaps—so their 2026 commitments are both opportunistic and resilient.
For detailed analysis of this topic, please visit the official page: Positive Temperature Coefficient (PTC) Thermistors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


