



PW Consulting: Smart TV-led TV Market to Reach USD 364.8M by 2032 at 6.98% CAGR

TV Market 2026: Strategic Preview for Corporate Decision‑Makers
PW Consulting’s latest TV Market research is built as a decision‑grade tool for boards, corporate strategy teams, and product leaders planning for 2026 and beyond. This preview synthesizes the highest‑value strategic conclusions from the full study: the macro trajectory, the operational and regulatory dynamics that will shape winners and losers, competitive posture of leading OEM integrators, and the pragmatic, near‑term priorities every executive should adopt. The full dataset, granular regional/type/application splits, and our financial model are available on the report landing page — this article intentionally surfaces interpretation and implications while withholding core segment detail to preserve the full report’s commercial value.
TV Market
Macro trajectory you can build a plan around
Using 2025 as the base year, the global TV Market sits at approximately USD 228.61 Million (revenue unit: Million) and has expanded consistently since 2020. From a solid historical baseline, the market enters a forecast window (2026–2032) with an expected compound annual growth rate (CAGR) of 6.98%, reaching roughly USD 364.77 Million by 2032 under our central case. That growth profile is robust enough to justify near‑term capex and product investment, yet not so rapid as to eliminate the need for disciplined portfolio prioritization — companies must choose where to concentrate R&D, manufacturing footprint, and channel investments to capture disproportionate value.
TV Market
Why 2026 is a strategic hinge year
- Acceleration of integration-led value: Automotive and large‑format use cases have shifted the competitive frontier from panel commodities to integrated display systems that combine hardware, software, and services. Decisions made in 2026 about platform architecture and supplier partnerships will lock in customer experience for multiple product generations.
- Regulatory and safety inflection: Functional safety, electromagnetic compatibility, and in‑vehicle light emissions standards are converging into mandatory engineering constraints that materially affect time‑to‑market and BOM design choices.
- Supply and technology squeeze: Incremental demand for higher‑quality displays coincides with capacity constraints in advanced panel fabs and a premium on integration expertise — creating a window for early movers to capture margin expansion.
Core dynamics shaping strategy
- From panels to experiences: Value is migrating away from raw panel supply to system‑level solutions — curved and panoramic systems, integrated infotainment, multi‑zone UX, and bundled content/services are where margins and differentiation now aggregate.
- Regulatory-driven product risk: UNECE standards for retro‑reflective materials and electromagnetic compatibility (R43 and R10), rules on blue light intensity (UNECE R65), and global expectations for FMVSS/ECE testing add both cost and certification timelines. Concurrently, ISO 26262 (functional safety) and ISO 21434 (cybersecurity) are gating factors for any in‑vehicle display deployment.
- Consolidation and supplier leverage: The market exhibits high concentration among a limited group of OEMs and Tier‑1 integrators. That structural reality increases negotiating power for established suppliers but also elevates entry barriers for specialist challengers who lack integration footprints.
- Software as a defensible moat: The platformization of displays — OTA update ecosystems, integrated media/content apps, and secure communication channels — creates recurring revenue and stickiness that hardware alone cannot replicate.
Competitive landscape: what the major manufacturers signal
Several automotive OEMs have become focal points for display innovation, and their public product strategies telegraph where investments are meaningful:
TV Market
- Tesla, Inc. (Austin, TX): Favors large‑format integrated displays and vehicle infotainment convergence. Their approach highlights the commercial opportunity for high‑integration suppliers who can deliver turnkey hardware plus content aggregation and connected services.
- BMW AG (Munich): Investing in panoramic vision systems that emphasize luxury UX and high fidelity displays — signaling demand for premium panel technologies coupled with advanced HMI software.
- Mercedes‑Benz Group AG (Stuttgart): Commercializing hyperscreen and curved display experiences that blend multiple zones and advanced graphics, underscoring the need for cross‑disciplinary systems engineering (mechanical, thermal, and software).
- Audi AG (Ingolstadt): Driving innovations around virtual mirrors and high‑resolution cluster systems, illustrating a move to replace mechanical components with software‑defined displays.
- General Motors Company (Detroit): Emphasizing large infotainment and instrument clusters across broad model portfolios, which increases scale opportunities for suppliers that can meet volume, cost and certification targets simultaneously.
The strategic takeaway: OEMs are no longer just customers of display glass — they act as integrators and product designers. Suppliers that can align to OEM systems‑integration roadmaps (hardware + software + compliance) will command superior terms.
Practical contents of the full PW Consulting report
For teams preparing investment memos, product roadmaps, or procurement strategies, the report provides action‑oriented deliverables, including:
- Market sizing and forecast with scenario variants (central, upside, downside) and an integrated financial model (2020–2032).
- Go‑to‑market playbooks for hardware OEMs, Tier‑1 suppliers, and software/service providers, keyed to three commercialization windows: 0–12 months, 12–36 months, and 36+ months.
- Competitive benchmark matrix covering capability, integration posture, route‑to‑market, and certification readiness for leading OEMs and supplier archetypes.
- Regulatory and standards impact assessment with compliance cost estimates and timeline implications tied to UNECE and ISO requirements.
- Supplier mapping and risk heatmap for component concentration, capacity constraints, and alternate sourcing scenarios.
- M&A and partnership shortlists generated by strategic fit algorithms and synergy modeling for multiples and integration costs.
- Templates for RFPs, acceptance tests, and contract clauses that protect IP, ensure cybersecurity, and allocate certification risk.
Actionable recommendations for 2026 corporate planning
- Prioritize system‑level investments: Redirect a portion of hardware R&D budgets into software platforms, UX toolchains, and OTA infrastructure. Even conservative scenarios in our model show higher lifetime margins for integrated offerings versus panel supply.
- Fast‑track certification planning: Begin ISO 26262 and ISO 21434 workstreams now; regulatory tests (UNECE R43/R10/R65 and FMVSS/ECE checks) add lead time and rework risk if started late. Allocate both budget and program management resources accordingly.
- Design for modularity and supplier optionality: Create product families with modular display units to enable multi‑supplier sourcing and mitigate capacity or technology disruptions.
- Forge content and services partnerships: Secure content aggregation and app partners early to populate integrated infotainment systems and capture recurring revenue streams.
- Use M&A tactically: Acquire small software teams or UX studios to accelerate capability-build; pursue bolt‑on purchases for niche certification expertise rather than large‑scale consolidation unless pursuing clear scale economics.
- Monitor KPIs that matter: Track time‑to‑certification, mean time to OTA deploy, supplier concentration ratio by BOM value, and software ARPU (for service‑enabled models).
Scenario sensitivities and what to watch next
Two main scenario levers will re‑shape forecasts and should be embedded in any investment decision: technology substitution pace (how quickly panels migrate to newer architectures and in‑vehicle standards evolve) and regulatory tightening (new testing requirements or cross‑jurisdictional harmonization). Our model provides sensitivity tables for both levers — those granular outputs and regional split analyses are held in the full report.
How to use this report in boardroom decision cycles
- Q1 2026 (Immediate): Baseline portfolio triage — classify SKUs into “must invest,” “maintain,” and “sunset” buckets based on integration fit and certification readiness.
- Mid‑term (12–24 months): Execute supplier consolidation or dual‑sourcing playbooks, begin certification projects, and run pilots with software/content partners.
- Longer term (24–60 months): Scale platform rollouts, integrate recurring service pricing, and evaluate M&A targets to pick up missing capabilities.
Final note — what you won’t find in this preview
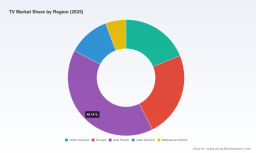
This article deliberately omits granular regional, type and application splits and the full competitive scorecards that underpin our valuation and scenario outputs. Those segmentation tables, contract‑level margin assumptions, and downloadable Excel workbooks are accessible on the report page and are essential for transaction due diligence or financial planning. If your team needs a tailored workshop (portfolios, procurement, or M&A screening), PW Consulting offers bespoke modules that operationalize the report into executable projects.
In a market that moves from commodity panels to integrated display experiences, 2026 will separate companies that merely sell components from those that own customer journeys. Use the next 12 months to lock in integration partners, accelerate certification, and build software moats — the full PW Consulting TV Market report gives you the granular maps and executable templates to do exactly that.
For detailed analysis of this topic, please visit the official page: TV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


